
Insurance Claim Information & Resources
Articles and newsletters from Homeland Public Adjusters, written for homeowners, condo owners, renters, landlords, business owners, commercial property owners, associations and property owners without coverage. Choose your section, or subscribe and we will send new articles to you.
Guest Experts
Attorneys, mitigation companies, contractors and other property professionals share what they see on the other side of a loss.

What Is Insurance Appraisal, and When Do You Need an Umpire?
Appraisal settles the dollar amount of a covered loss, not whether it's covered at all. A CPAU-designated appraiser and umpire explains how the process works, when it applies, and why the umpire has to stay neutral.
More guest voices coming soon
More guest voices coming soon
Guest articles reflect the author’s own views from their independent practice, are for general information only and are not legal advice.
Claims Process
✉ Subscribe to NewsletterReservation of rights letters, roof denials, depreciation, held-up checks, reopened claims, appraisal and mediation: what to do when a claim stalls.
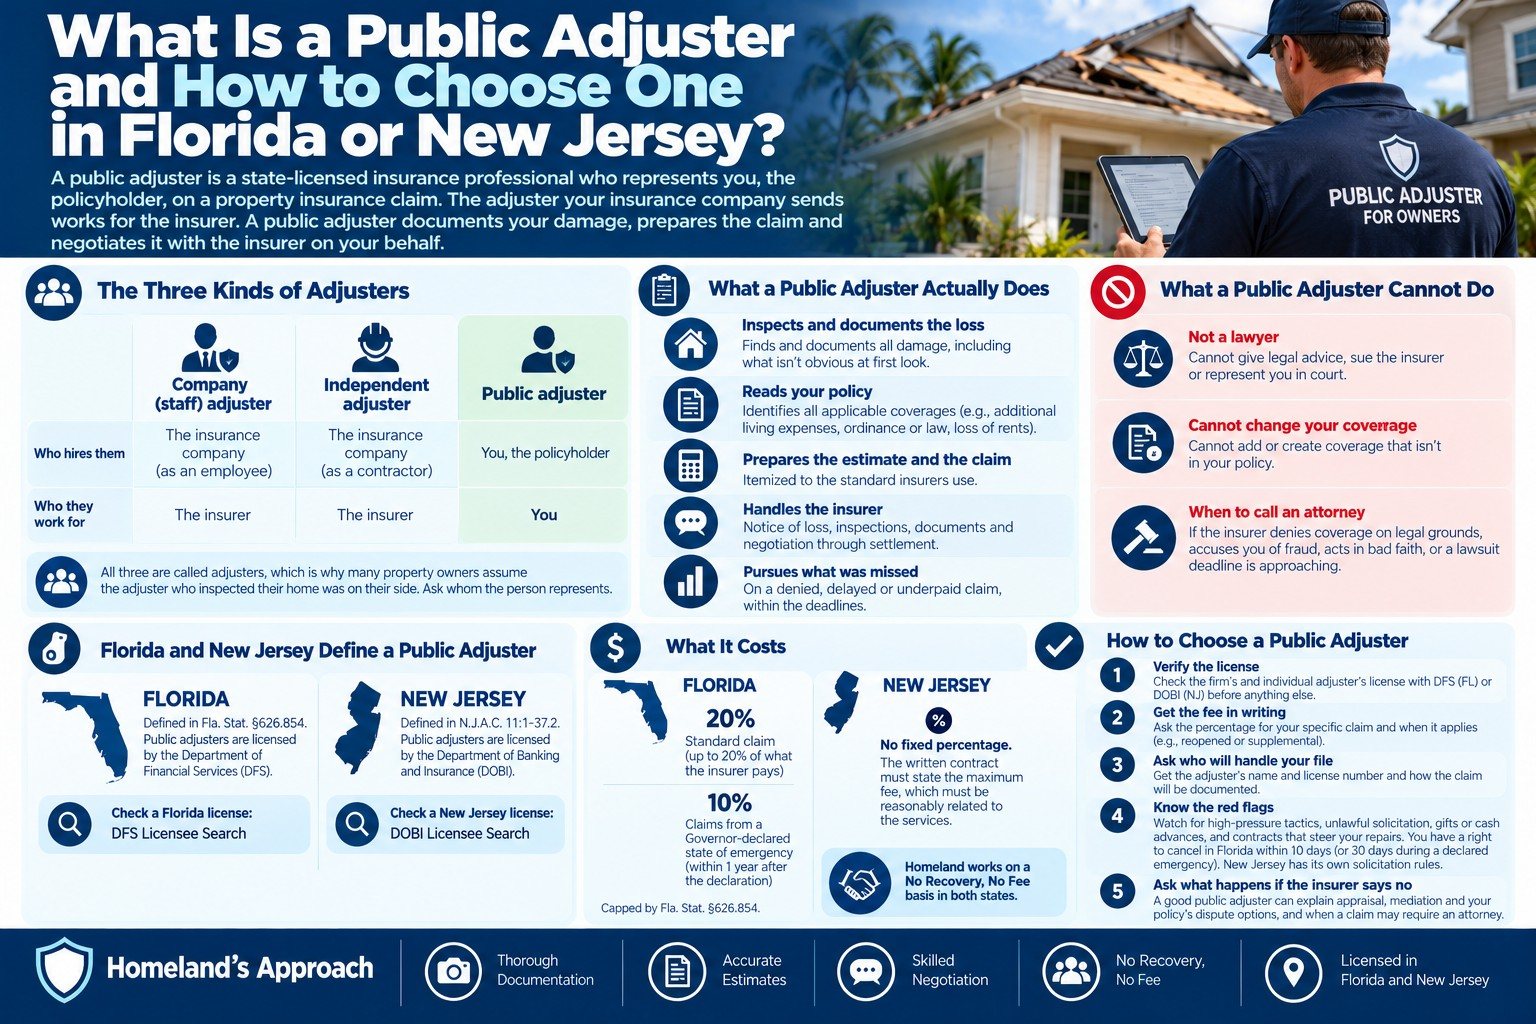
What Is a Public Adjuster and How to Choose One in Florida or New Jersey
A public adjuster is a state-licensed professional who represents the policyholder, not the insurer. What they do, what they cost, and how to choose and verify one in Florida and New Jersey.
By Nelson Avila
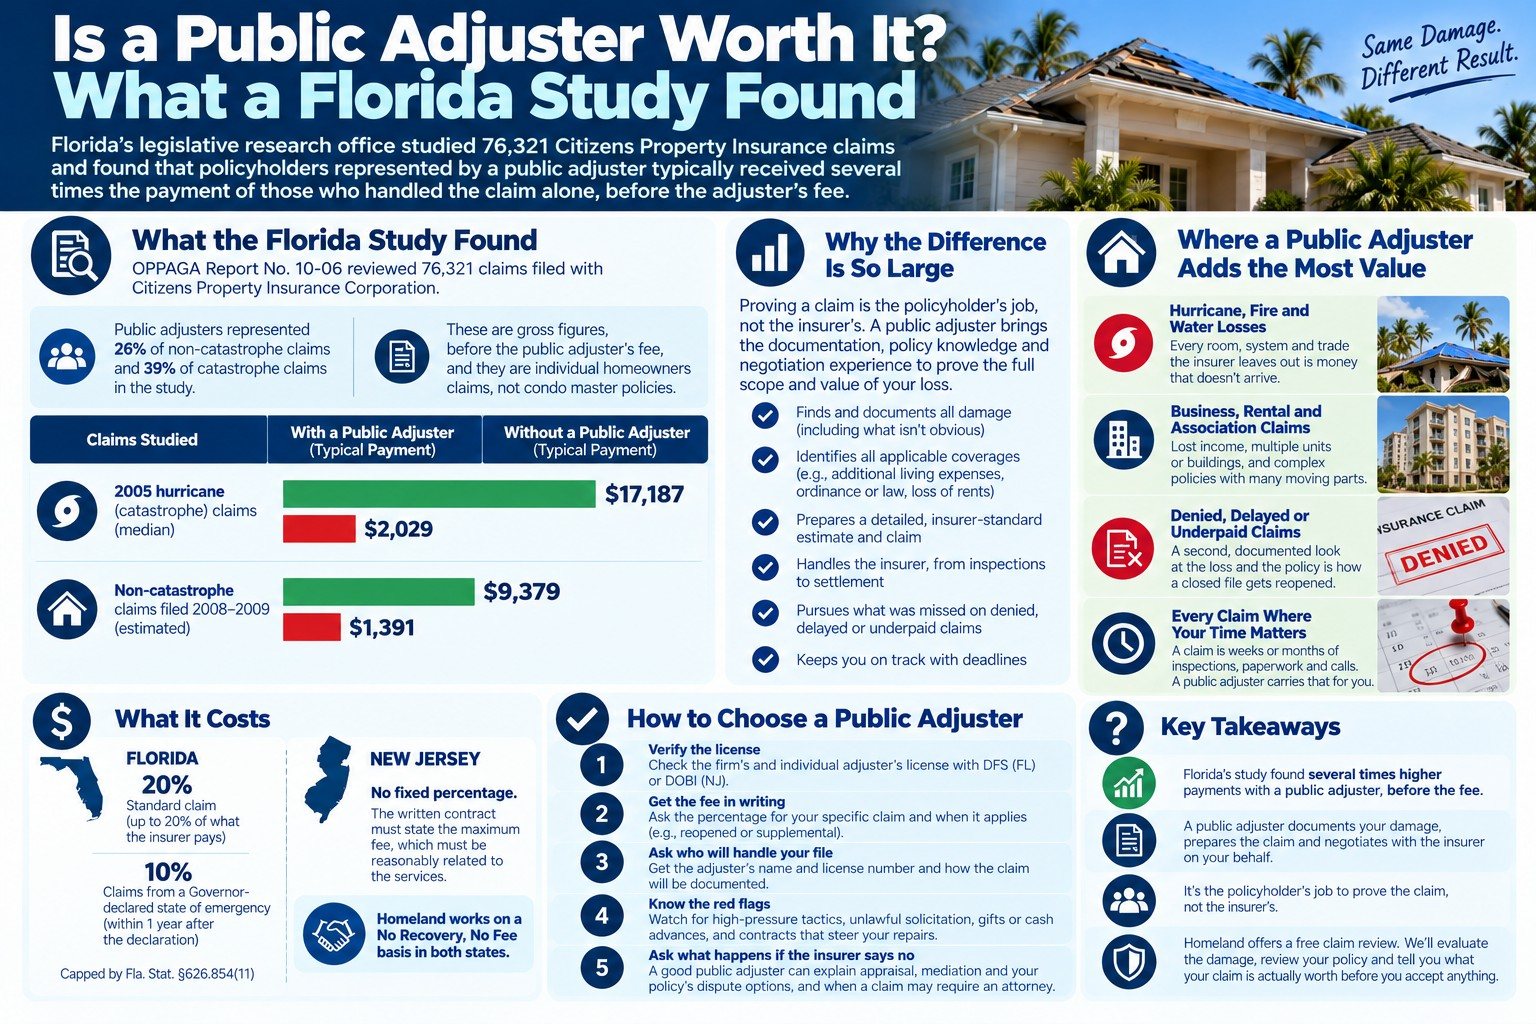
Is a Public Adjuster Worth It? What a Florida Study Found
Is hiring a public adjuster worth the fee? What Florida's legislative research office found about claim payments with and without one, and why proving the claim is the policyholder's job.
By Nelson Avila
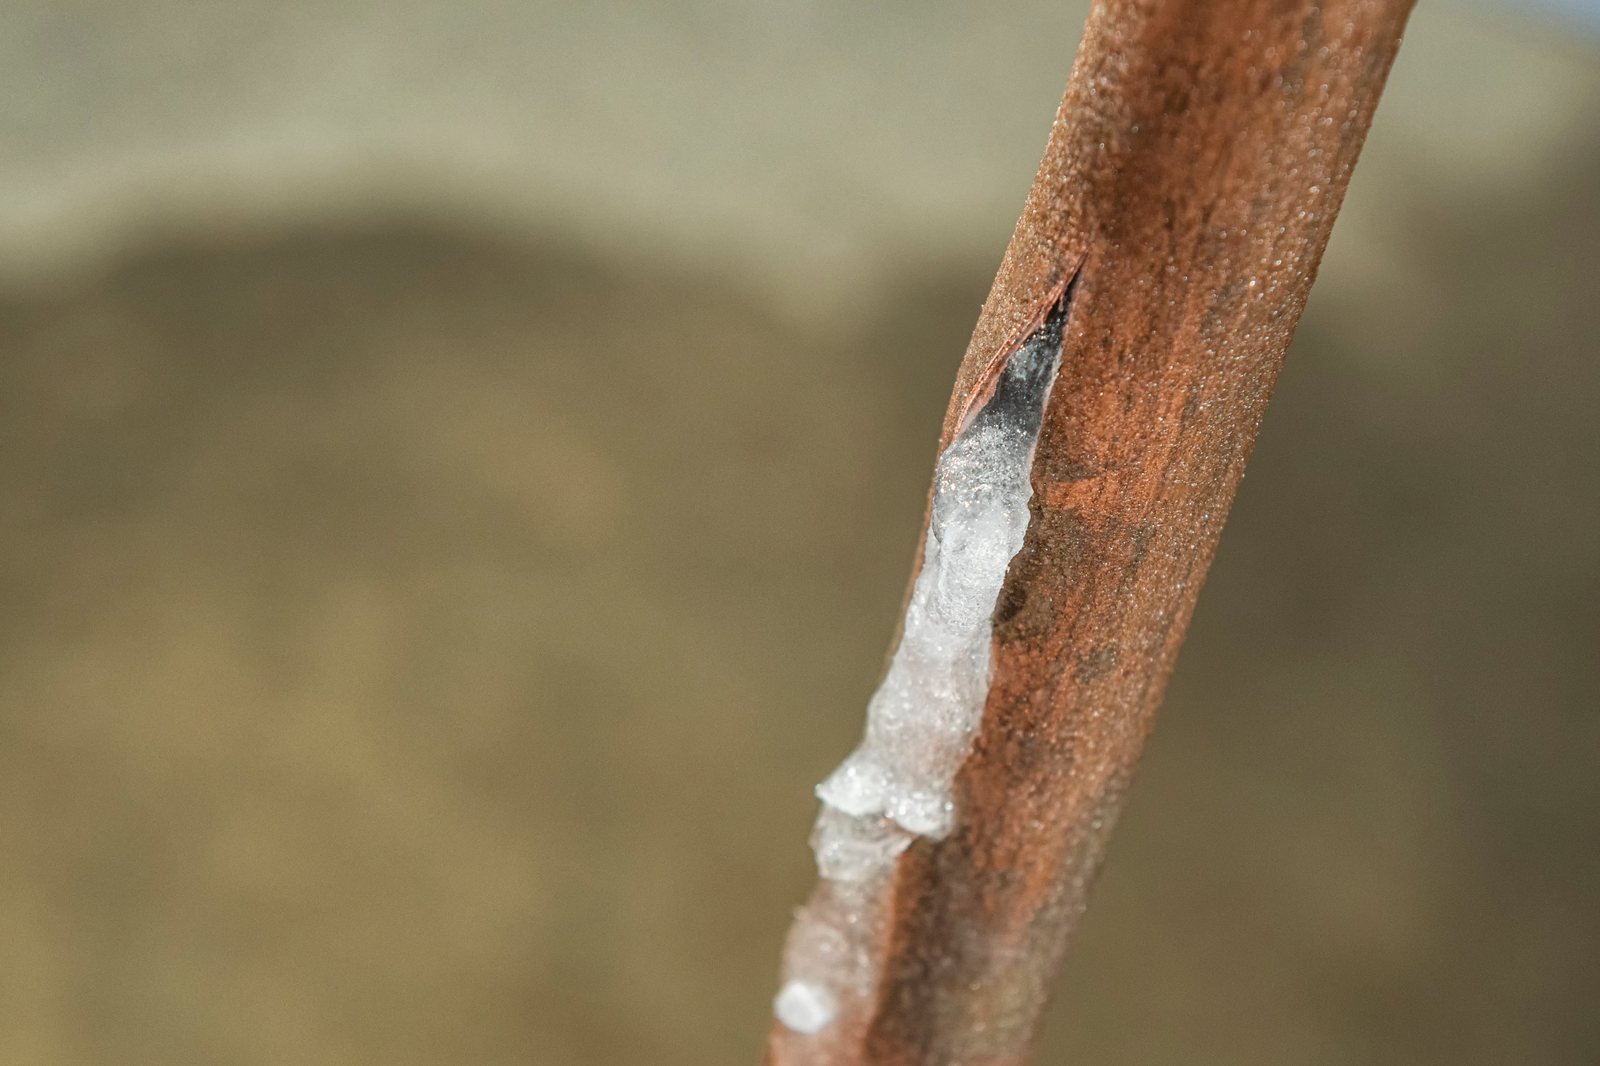
Does Homeowners Insurance Cover Burst Pipes?
Most homeowners policies cover sudden, accidental water damage from a burst pipe, but a pipe that froze is covered only if you took reasonable care. What to check in Florida and New Jersey.
By Nelson Avila
Reservation of Rights Letter: What It Means for Your Property Claim
A reservation of rights letter means your insurer is still investigating but may later deny coverage. What it means in Florida and New Jersey, and what to do next.
By Nelson Avila
Roof Claim Denied for “Wear and Tear” or “Cosmetic Damage”?
Why insurers deny roof claims as wear and tear or cosmetic damage, how storm damage is told apart from aging, and what Florida and New Jersey owners can do next.
By Nelson Avila
What Is Recoverable Depreciation on an Insurance Claim?
Recoverable depreciation is the part of a replacement cost claim the insurer holds back until repairs are done. How it works in Florida and New Jersey, with an example.
By Nelson Avila
Insurance Check Made Out to You and Your Mortgage Company
Why your insurance check names your mortgage lender, how lenders release repair money, and what Florida and New Jersey rules say about it.
By Nelson Avila
Claim Closed Without Payment? How to Reopen It
Why insurers close property claims without paying, and how reopened and supplemental claims work in Florida and New Jersey, including the deadlines.
By Nelson Avila
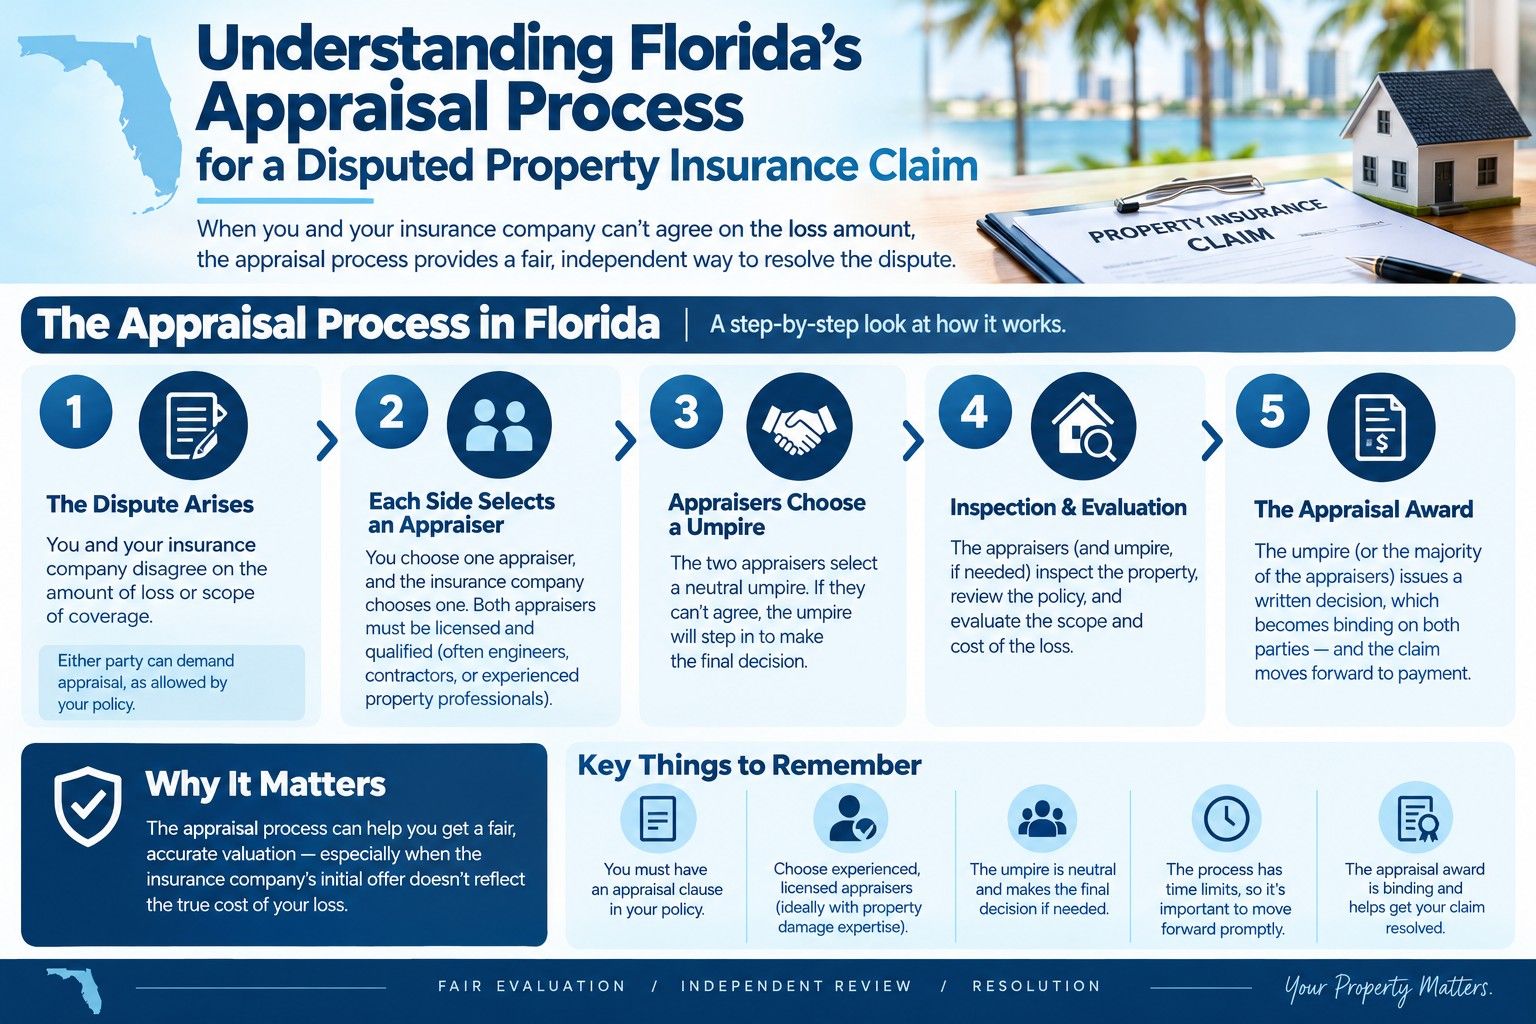
Understanding Florida's Appraisal Process for a Disputed Claim
How Florida's property insurance appraisal process works, when it's the right move, and what to know before invoking it.
By Nelson Avila
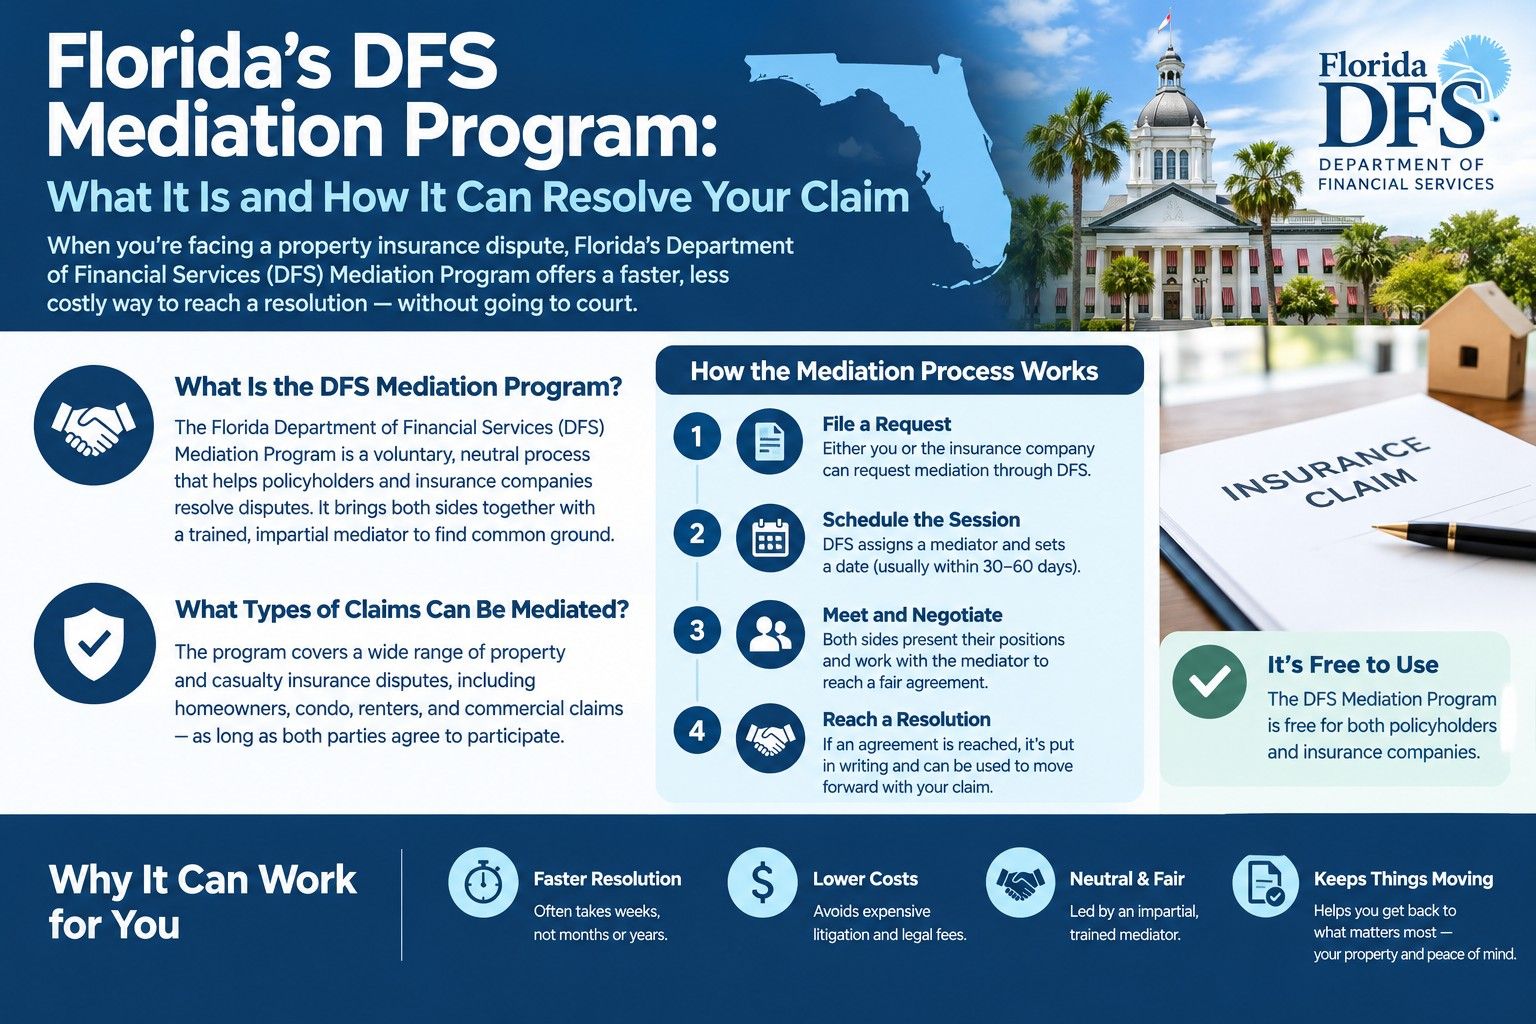
Florida's DFS Mediation Program: What It Is and How It Can Resolve Your Claim
A free, insurer-paid mediation program for disputed homeowners claims. How it works, and when it's worth requesting.
By Nelson Avila
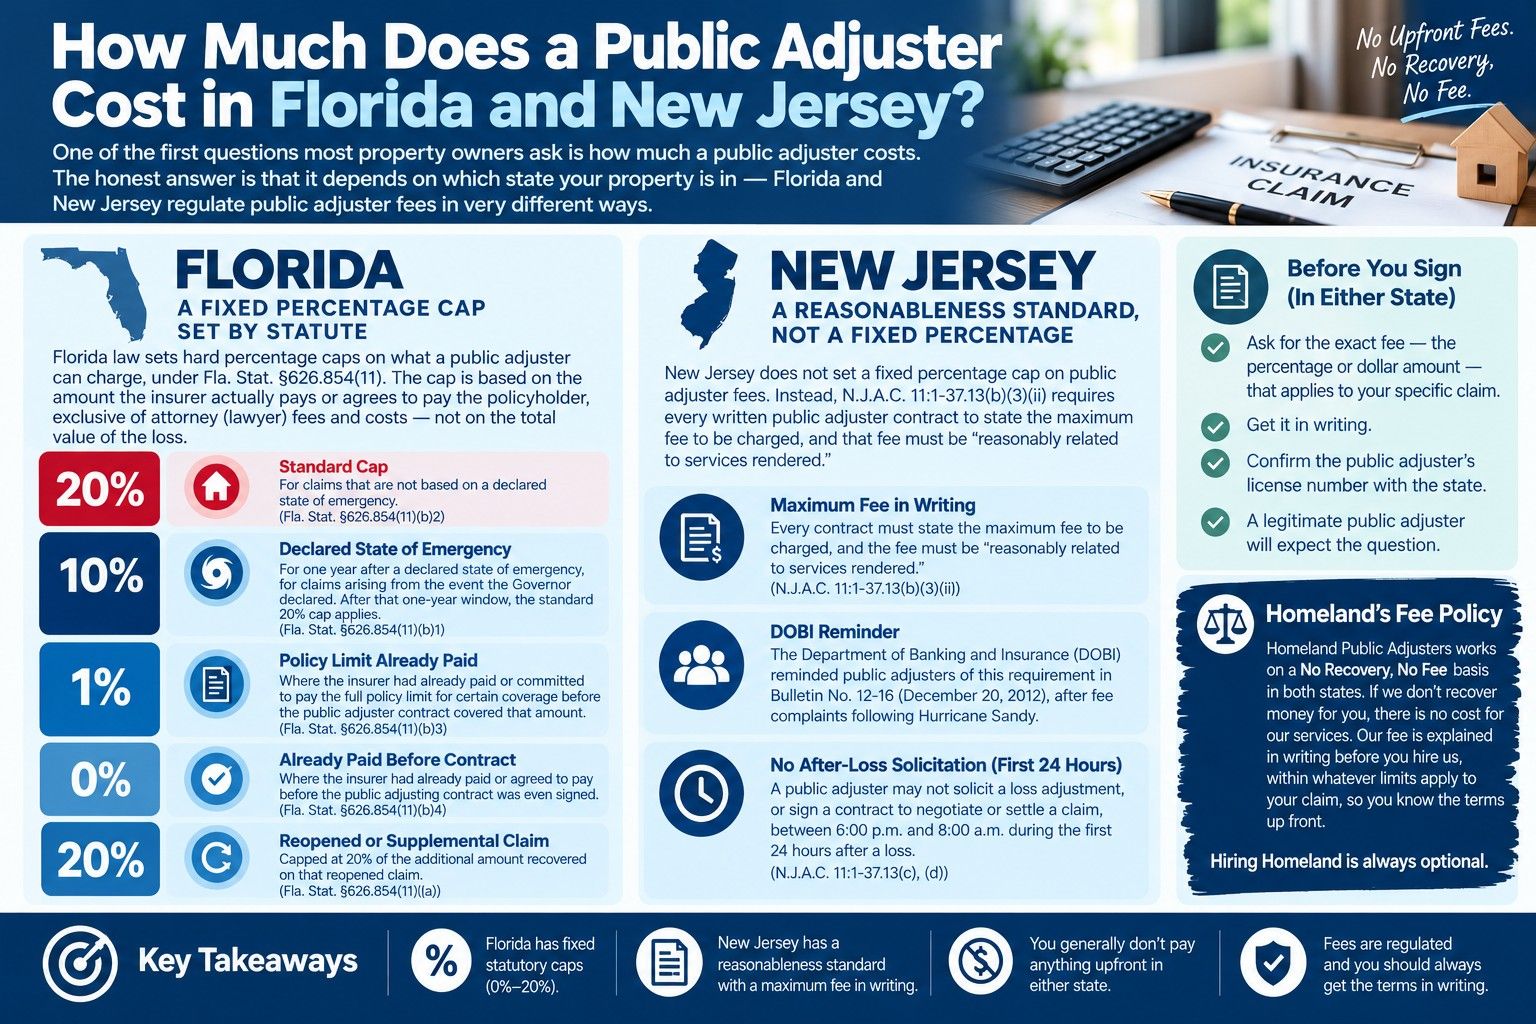
How Much Does a Public Adjuster Cost in Florida and New Jersey?
Florida caps public adjuster fees by statute. New Jersey uses a reasonableness standard instead of a fixed percentage. Here's how each state's rule actually works.
By Nelson Avila
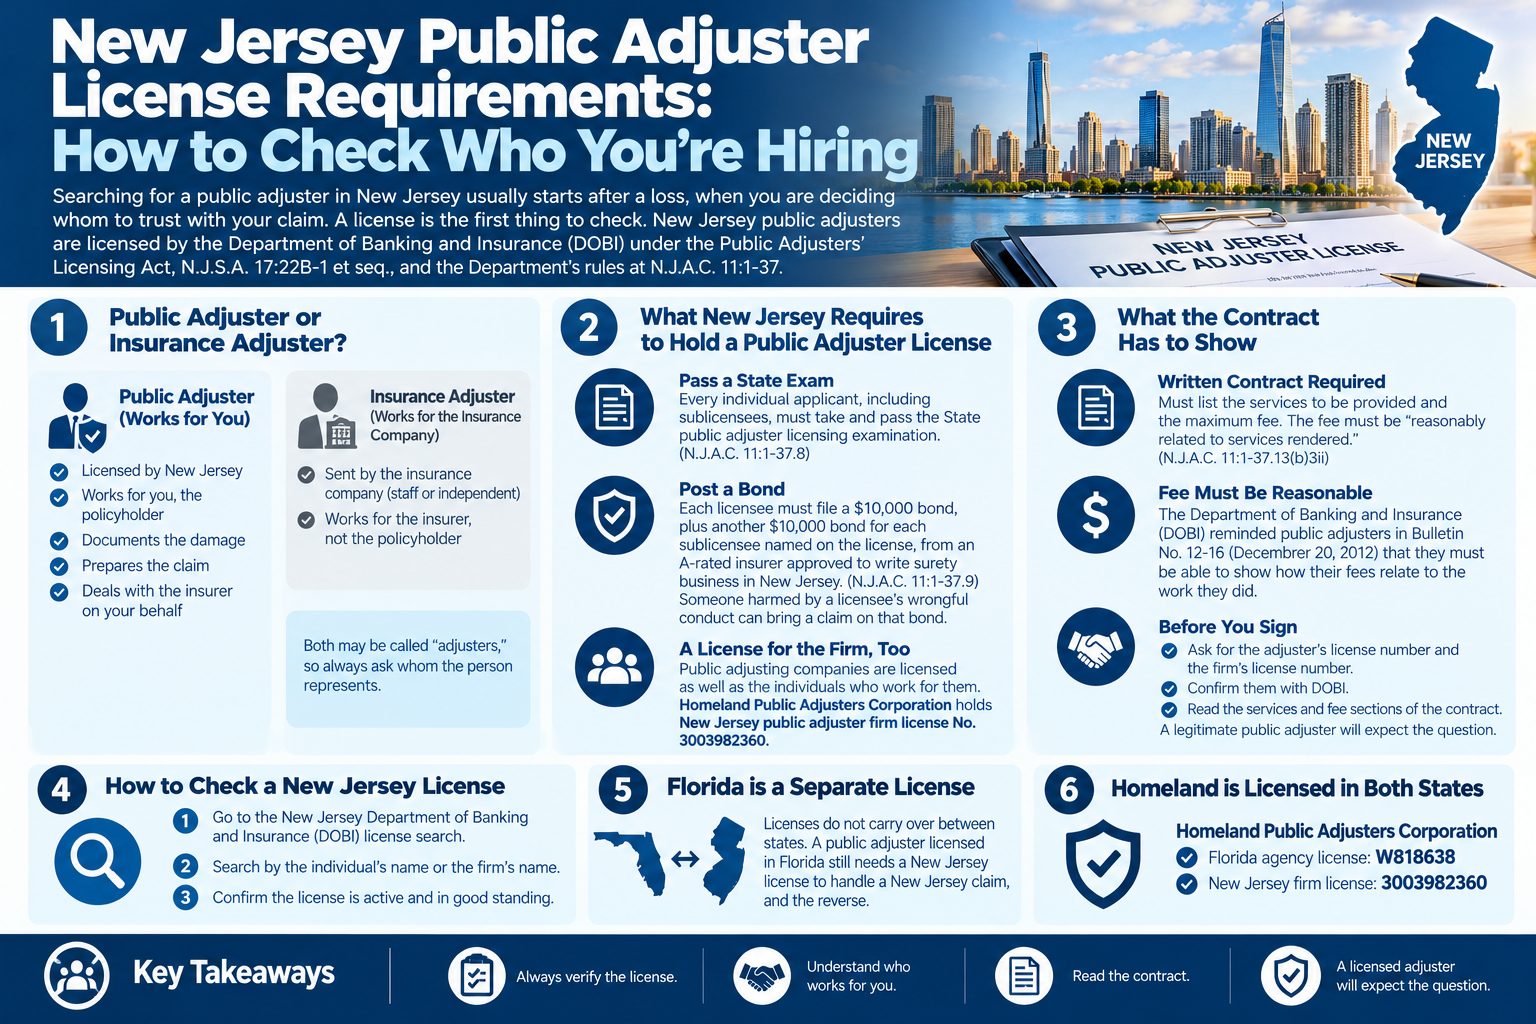
New Jersey Public Adjuster License Requirements: How to Check Who You’re Hiring
What New Jersey requires of a licensed public adjuster, from the state exam to the $10,000 bond and a written contract with a maximum fee, and how to confirm who you’re hiring.
 By Yeni Martinez
Deadlines, attorney (lawyer) fees and every option for a disputed claim in Florida and New Jersey.
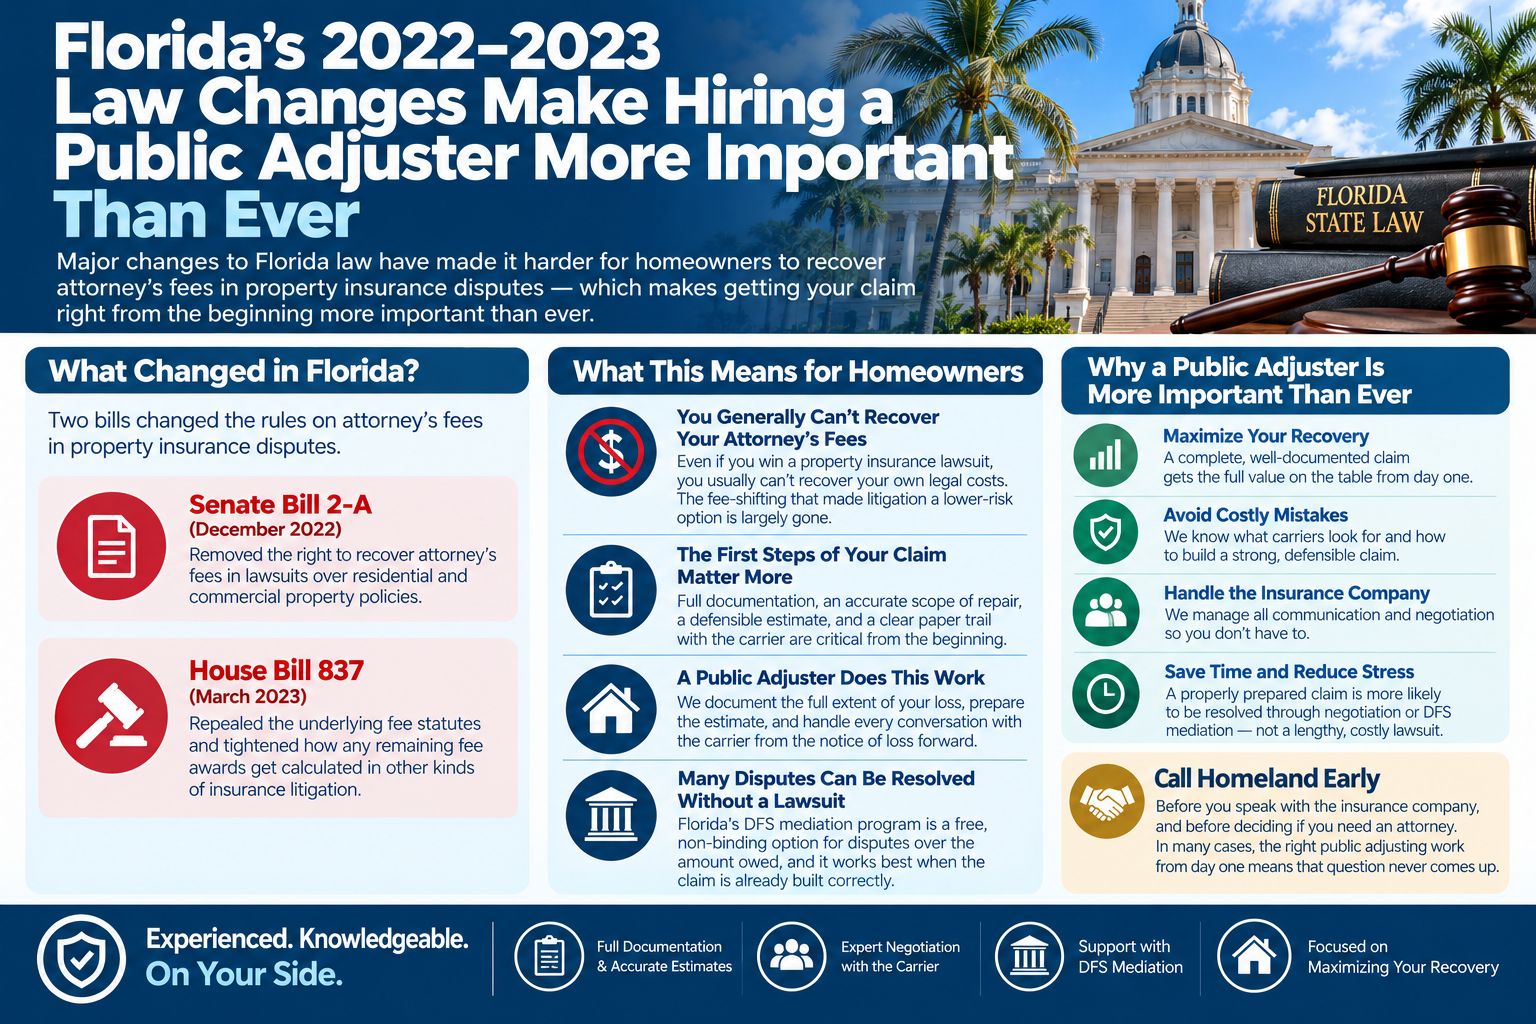
Florida's 2022–2023 Law Changes Make Hiring a Public Adjuster More Important Than Ever
Florida eliminated one-way attorney (lawyer) fees on property insurance lawsuits. Here's why getting your claim right from the start now matters more than ever.
By Nelson Avila
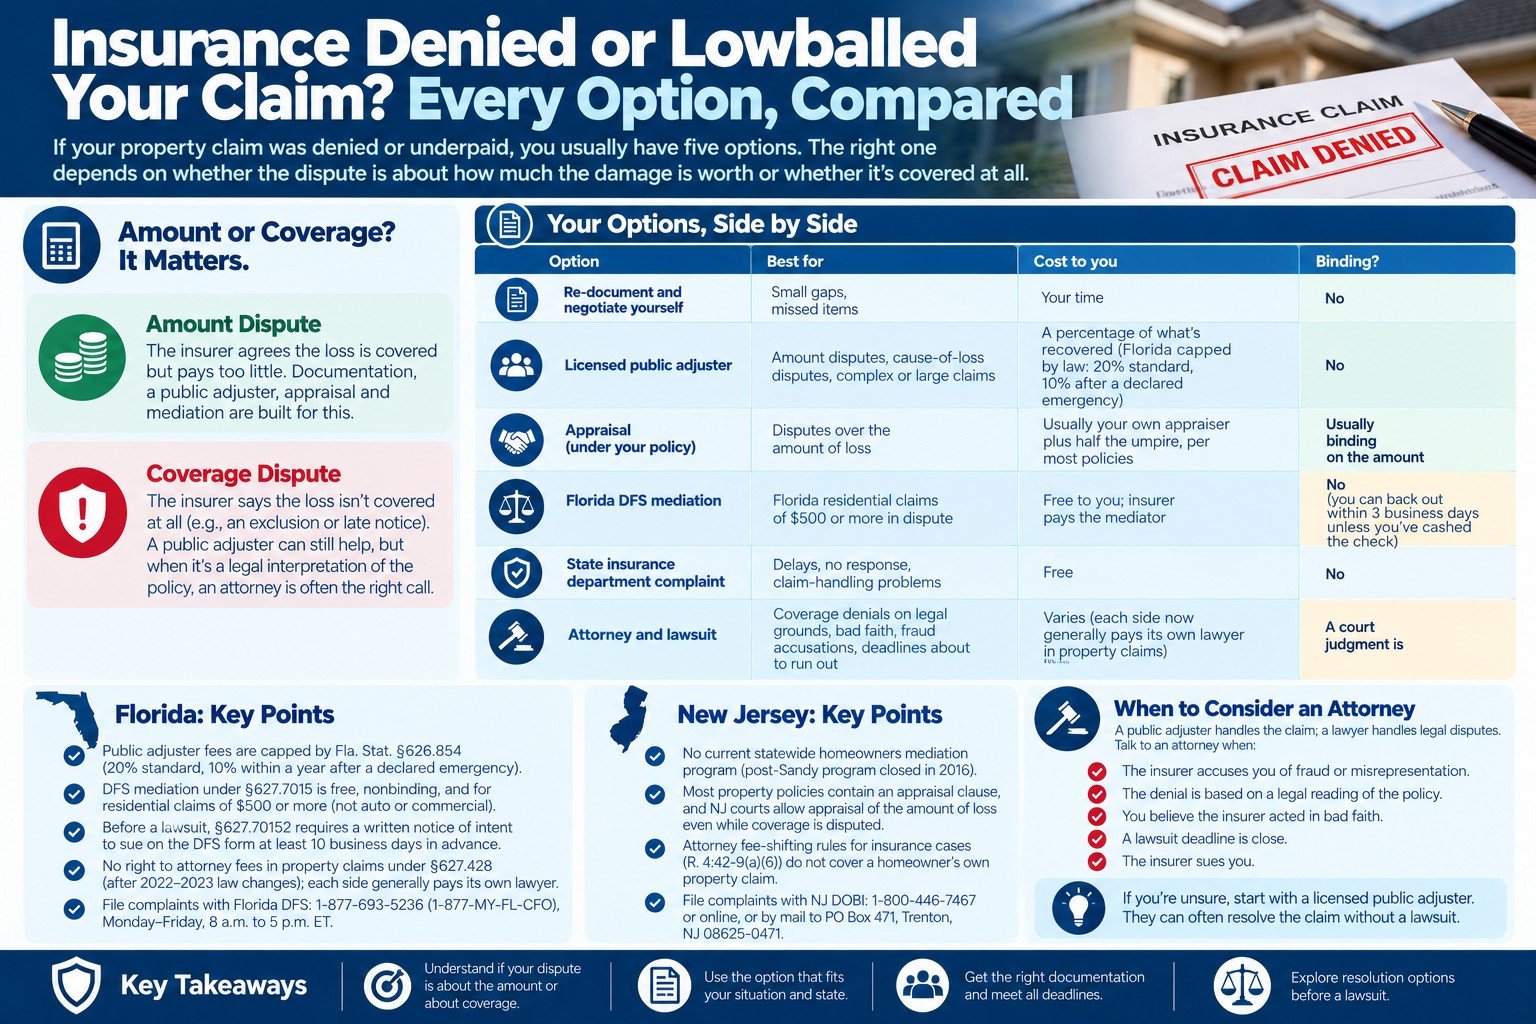
Insurance Denied or Lowballed Your Claim? Every Option, Compared
Public adjuster, appraisal, DFS mediation, a state complaint or an attorney: every way to fight a denied or underpaid property claim in Florida and New Jersey, side by side.
By Nelson Avila
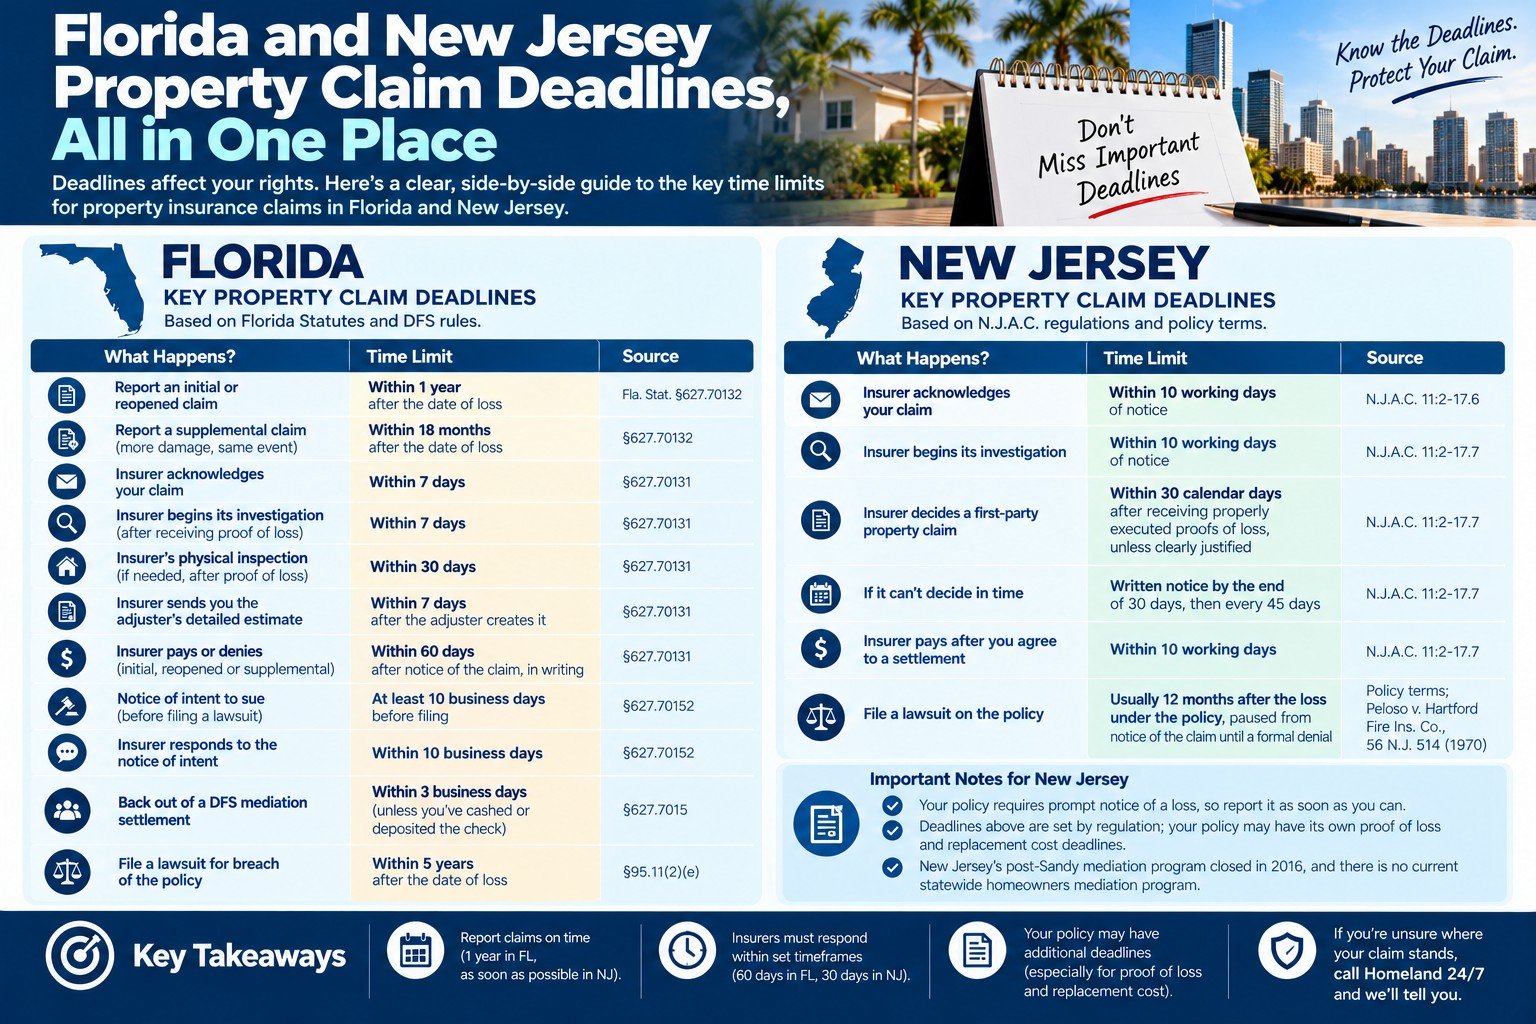
Florida and New Jersey Property Claim Deadlines, All in One Place
Every key property insurance deadline in Florida and New Jersey on one page: reporting a claim, insurer response times, reopening, and the time to sue, with sources.
By Nelson Avila
Policy Trends
✉ Subscribe to NewsletterSublimits, matching rules and roof-repair code changes: what's shifting in Florida policies right now.
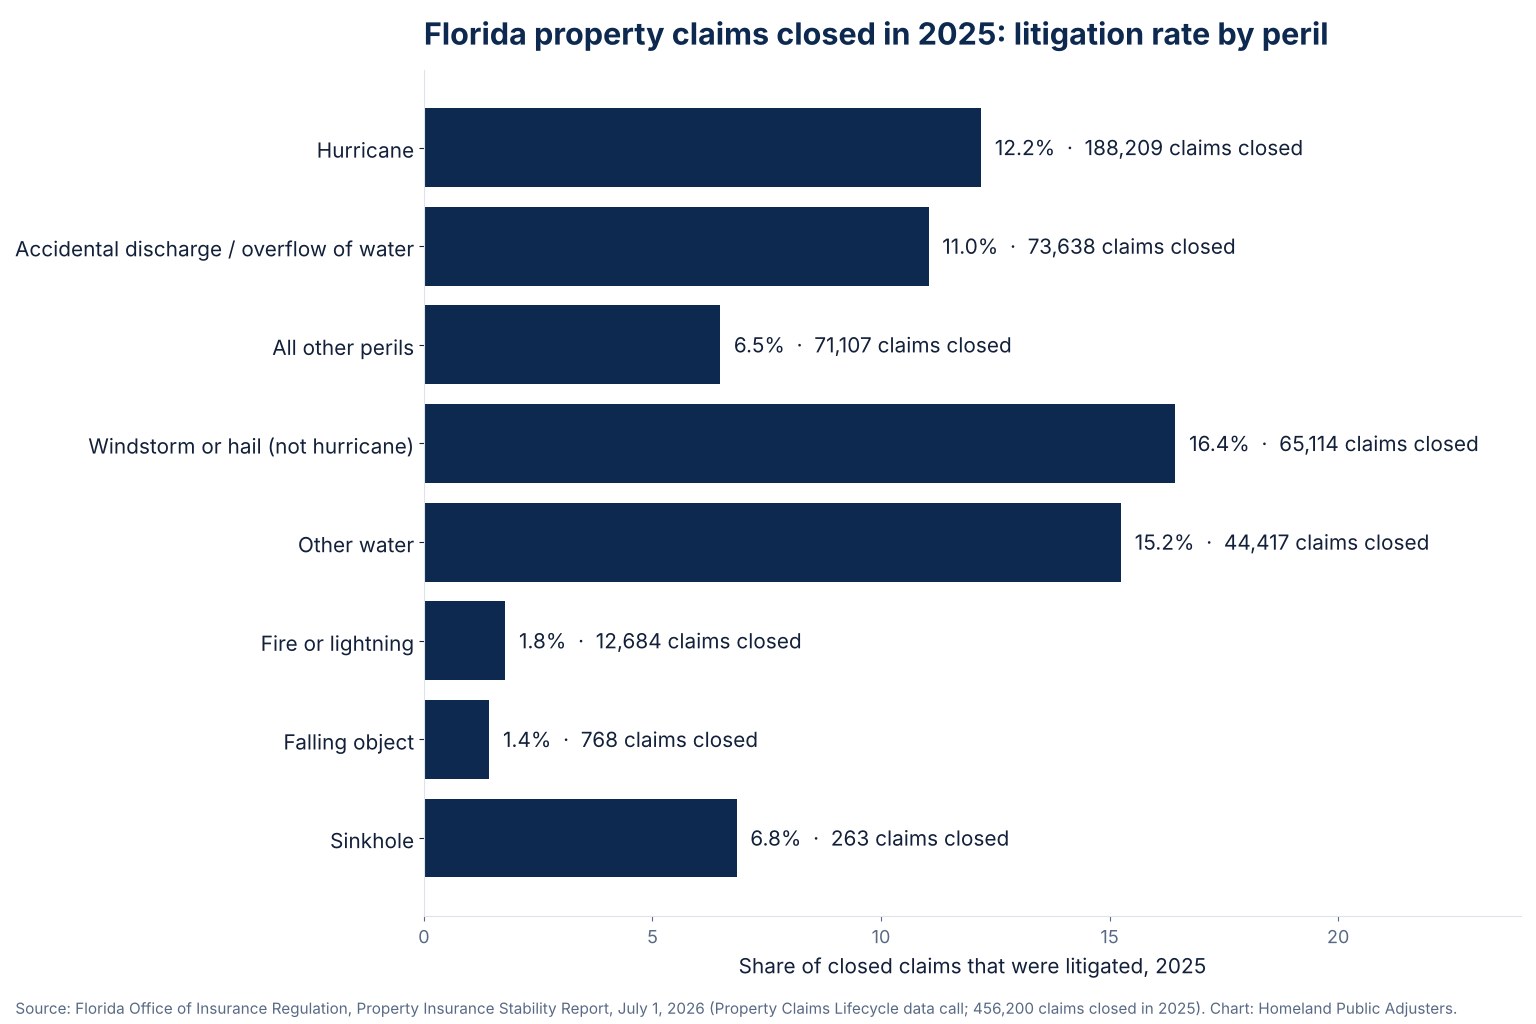
Florida Property Insurance Claims by the Numbers: What the State’s 2026 Report Shows
456,200 Florida property claims closed in 2025, 12% litigated, a median of 30 days to close, and the average homeowners premium in all 67 counties, from OIR's July 2026 Property Insurance Stability Report.
By Nelson Avila
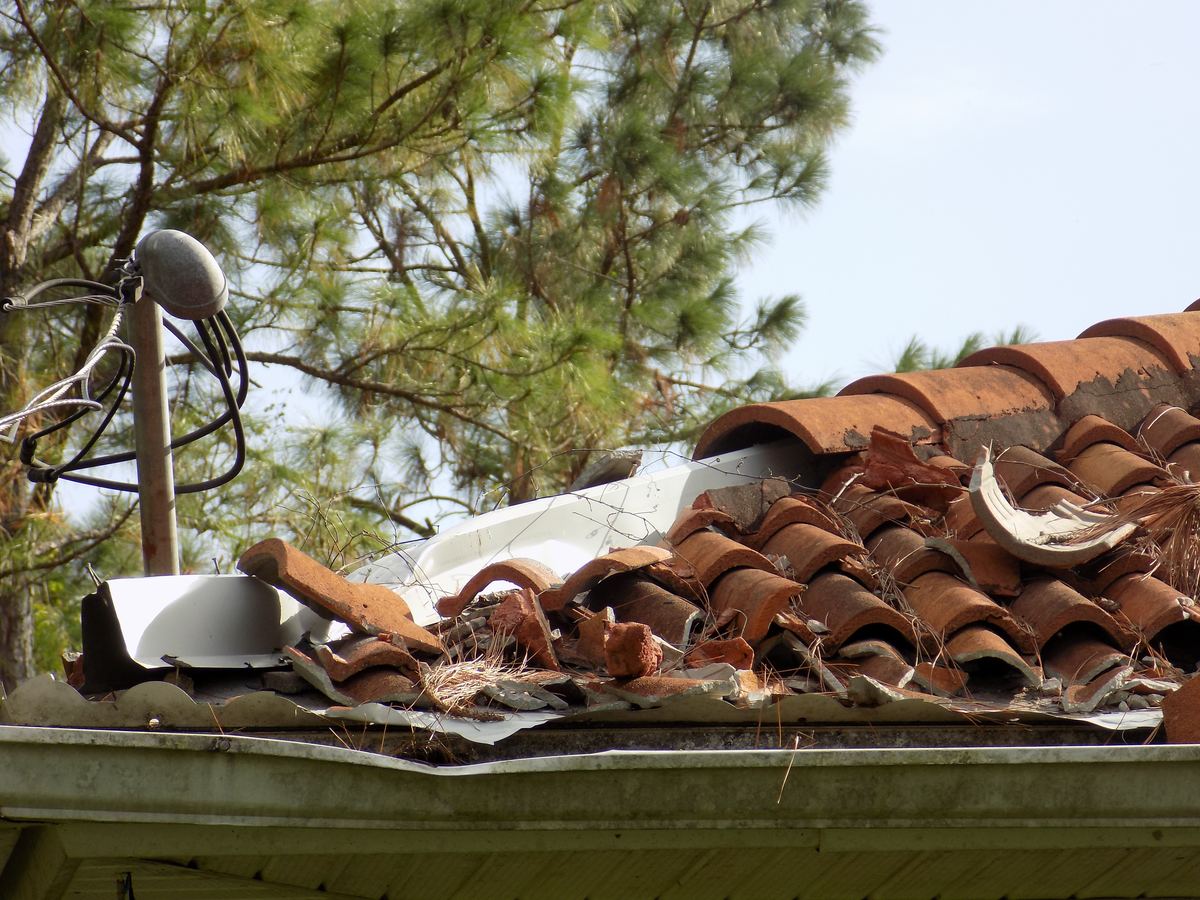
What Is a Hurricane Deductible? How It Works in Florida and New Jersey
A hurricane deductible is a separate, usually percentage-based deductible that applies only to hurricane losses. Florida's options, when it applies, and New Jersey's 74 mph rule.
By Yeni Martinez
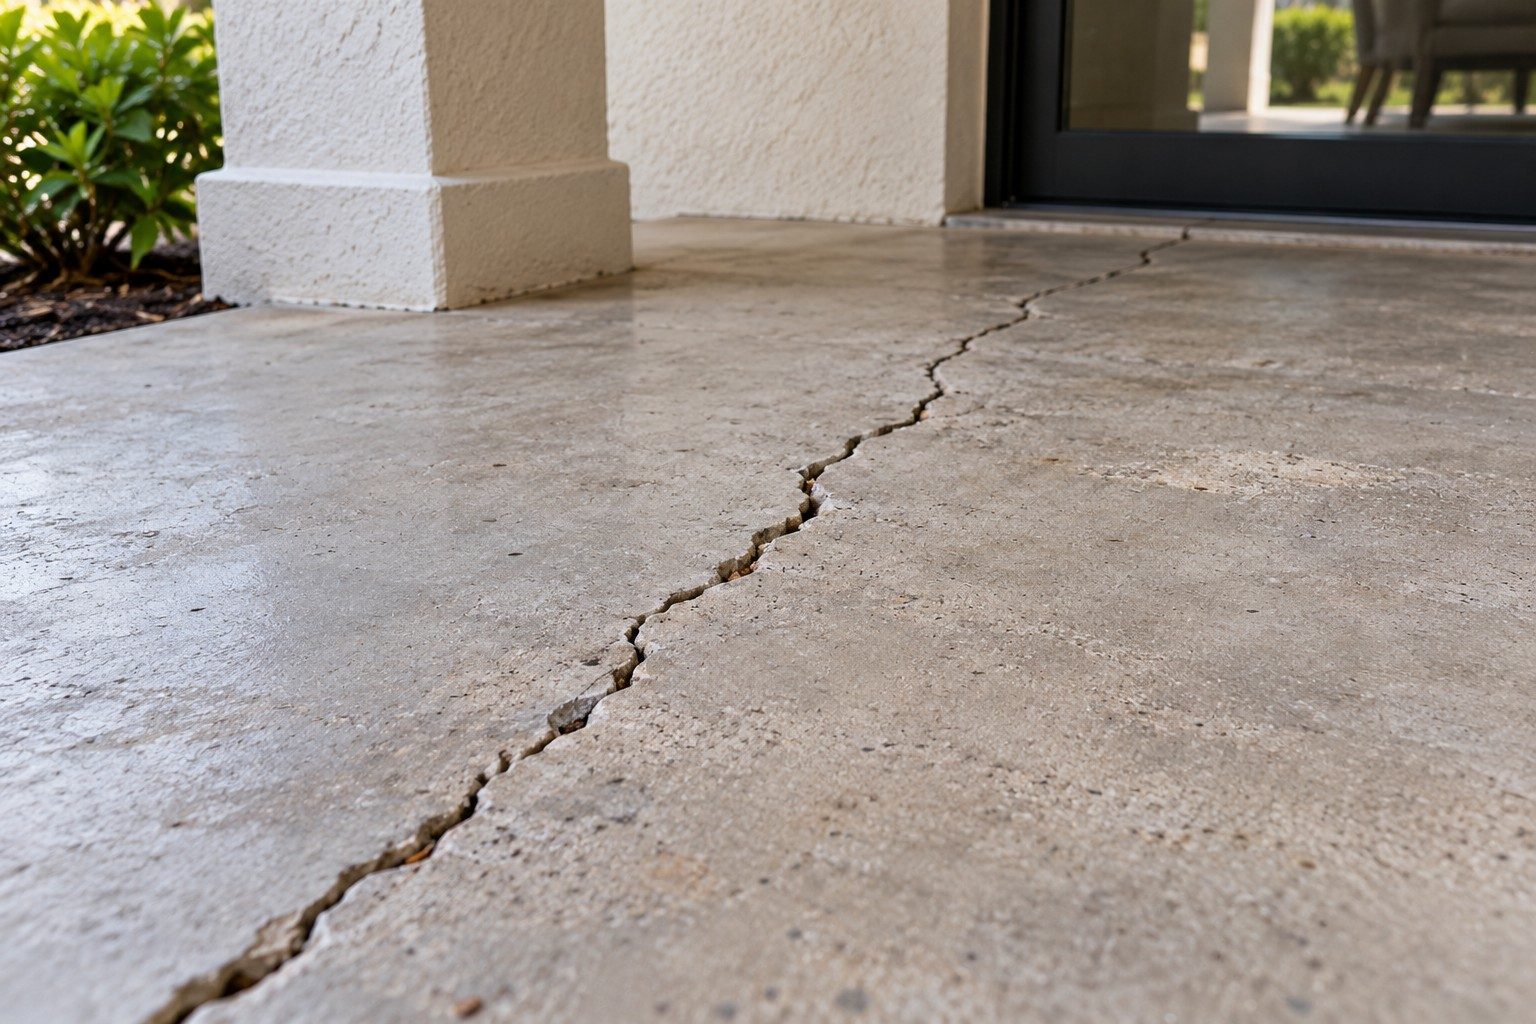
Warning Signs of a Sinkhole in Your Yard, and What Florida Insurance Covers
The warning signs of a sinkhole on your property, what to do first, and the difference between catastrophic ground cover collapse and optional sinkhole coverage under Florida law.
By Nelson Avila
Florida's $10,000 Water Damage Sublimit: What It Means for Your Claim
A growing number of insurers cap non-weather water damage at $10,000, and a restoration company's own emergency work can use up that cap before repairs even begin.
By Nelson Avila
Florida's Matching Law and the New 1% Payout Cap
Florida law requires repairs to reasonably match your home, but a new wave of endorsements caps what insurers pay for that matching at just 1% of your dwelling coverage.
By Nelson Avila
Florida's Roof Repair Rules Changed: Why a Full Replacement Isn't Automatic Anymore
A 2022 building-code change made it easier for insurers to approve a partial roof repair instead of a full replacement.
By Nelson Avila
How Mold Coverage Actually Works Under a Florida Homeowners Policy
Most homeowners don't realize mold coverage depends on whether the water loss that caused it was itself covered, and that it's usually capped separately even when it is.
By Nelson Avila
Fire Claims by Cause
✉ Subscribe to NewsletterEvery fire is a covered loss; every cause brings its own adjuster, exclusion argument and evidence. Electrical, lithium battery, kitchen, dryer, chimney, space heater, garage, brush fire, arson, and the smoke claim that outlives all of them.
Electrical Fire Insurance Claims: Panels, Wiring and the “Faulty Workmanship” Argument
An electrical fire is covered even when bad wiring or a defective panel started it. The faulty-workmanship argument, what the claim includes, and what to keep.
By Nelson Avila
Lithium Battery Fires: E-Bike, Scooter, Golf Cart and EV Fire Insurance Claims
An e-bike, scooter, golf cart or EV battery fire is a covered fire loss, usually a total one. Which policy pays for what, and what carriers argue.
By Nelson Avila
Kitchen and Grease Fire Insurance Claims: What Gets Paid After a Stove Fire
A stove or grease fire is covered even if you left the pan unattended. What the claim should include: cabinets, ceiling, smoke through the house and living expenses.
 By Alberto Enriquez
Dryer Fire Insurance Claims: Lint, Vents and Who Pays
A dryer fire is covered even when uncleaned lint caused it. What the claim includes, the manufacturer question, the vent code upgrade, and what to keep.
 By Yisel Dieguez
Chimney Fire Insurance Claims in New Jersey: Flue Damage, Attic Fires and the Inspection Record
A chimney fire is covered in New Jersey, even a contained flue fire that cracks the liner. The deterioration argument, the Level 2 inspection, and the claim clocks.
By Yeni Martinez
Space Heater Fire Insurance Claims: Covered, and Why the Scope Is the Fight
A space heater fire is covered for homeowners and renters. Who pays for the building and the belongings in a rental, and why the smoke scope is the fight.
By Nelson Avila
Car, Boat or Golf Cart Fire in the Garage: Two Policies, One Burned House
A car, boat or golf cart fire in the garage is an auto claim for the vehicle and a property claim for the house. How the two policies split the loss.
By Nelson Avila
Brush Fire and Wildfire Smoke Damage Claims in Florida and New Jersey
Brush fire and wildfire claims in Florida and New Jersey: fire is covered, and so are smoke, soot and ash from a fire that never reached the house.
By Nelson Avila
Arson and Tenant-Set Fires: Is an Intentional Fire Covered?
An intentional fire is covered unless an insured set it. The exclusion, arson investigations, examinations under oath, and the landlord's tenant-fire claim.
By Nelson Avila

Smoke Damage Insurance Claims: Why They Are Underpaid and How to Prove the Loss
Smoke damage is covered, and it is the most underpaid part of every fire claim. Soot types, odor, HVAC, contents, hygienist testing and what to claim.
By Yisel Dieguez
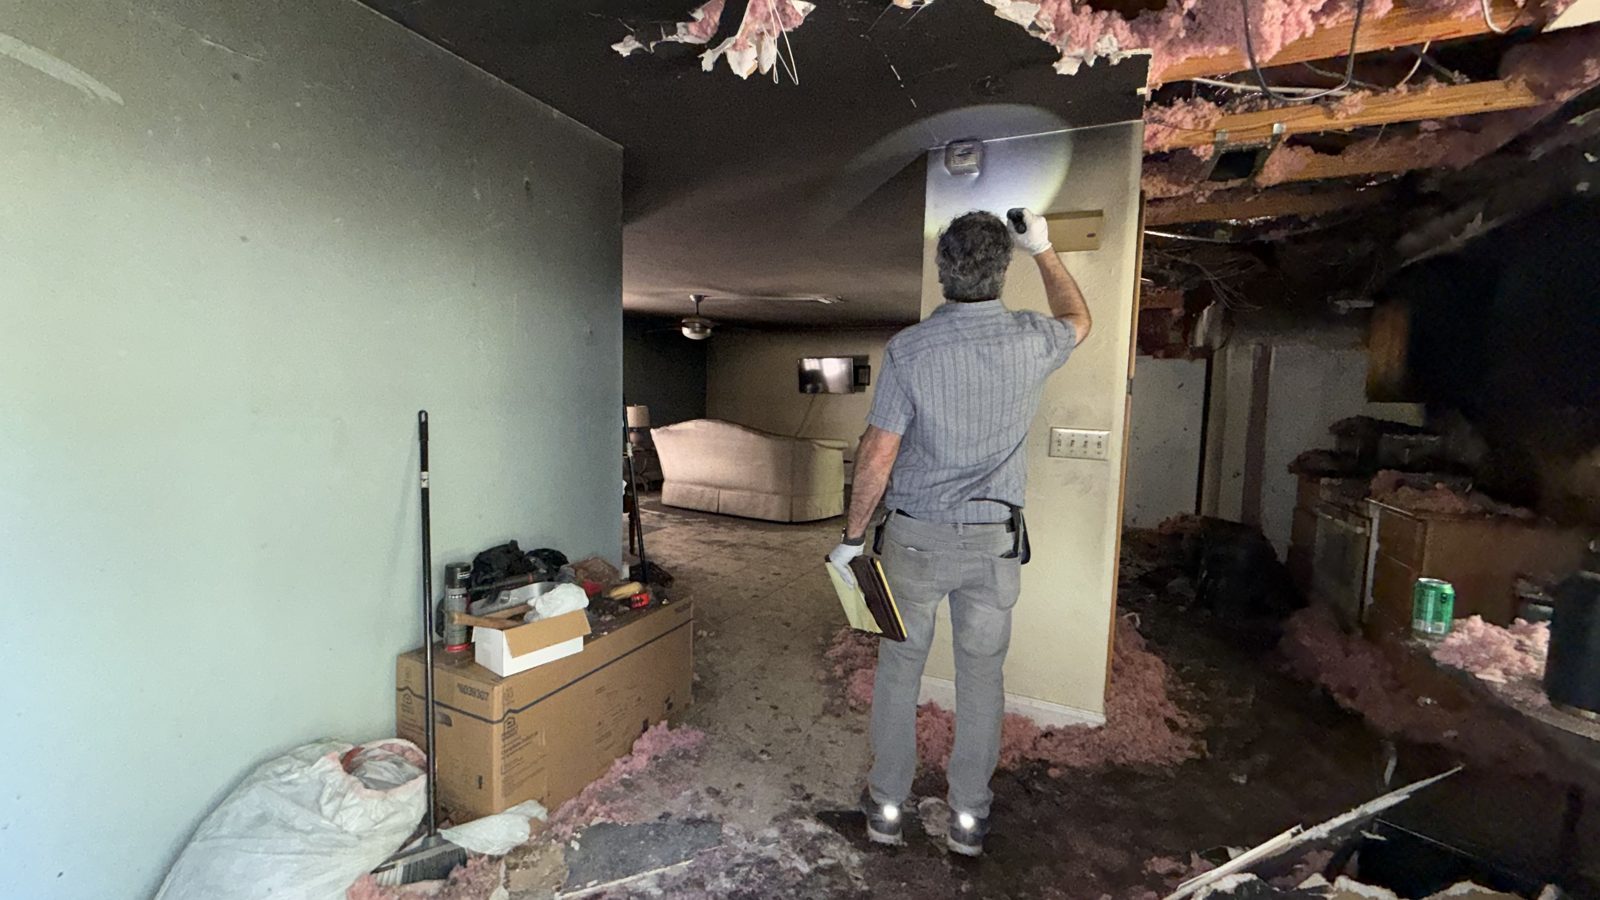
What to Do After a House Fire: The First 72 Hours and the Insurance Claim
The first 72 hours after a house fire in Florida or New Jersey: the fire report, loss of use, what not to throw away, the inventory, and who to call first.
By Nelson Avila
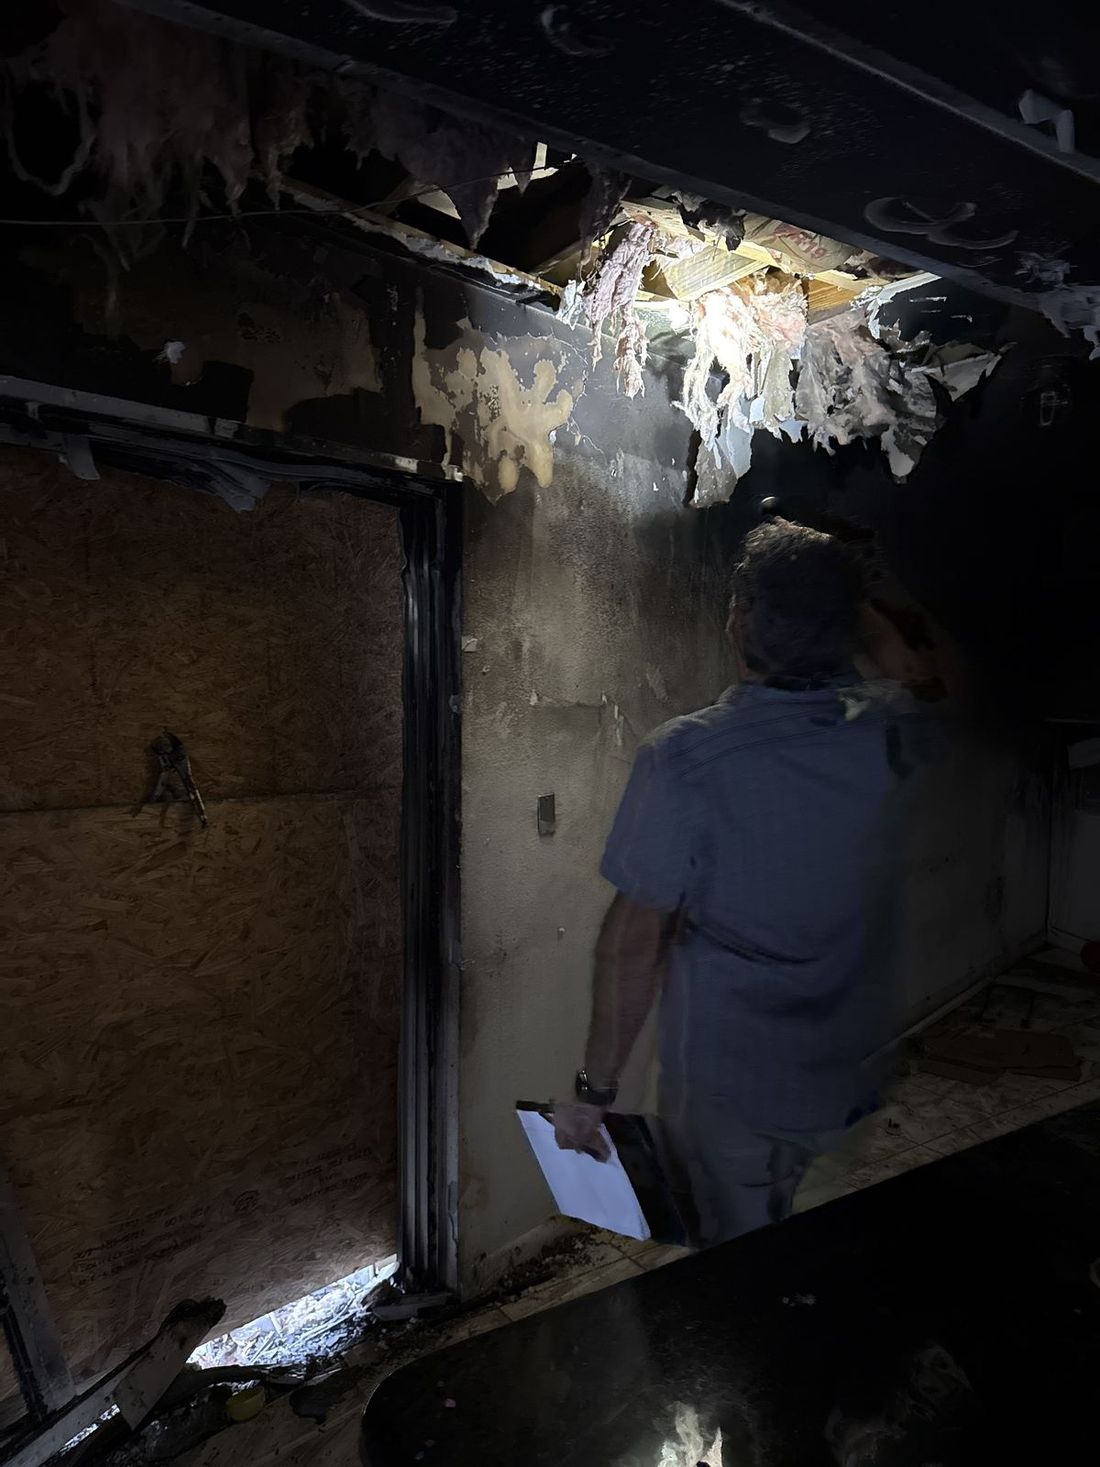
What Does a Fire Adjuster Do? The Carrier’s Adjuster, the Public Adjuster and the Fire Investigator
The carrier's fire adjuster, the origin-and-cause investigator and the public adjuster: what each does after a house fire, who they work for, and what it costs.
By Nelson Avila
Sudden Damage That Isn’t a Storm
✉ Subscribe to NewsletterA tree through the roof, a lightning strike, a water heater that lets go, a raccoon in the attic, a hailstorm, a collapse. The losses nobody expects, and what the policy actually pays.
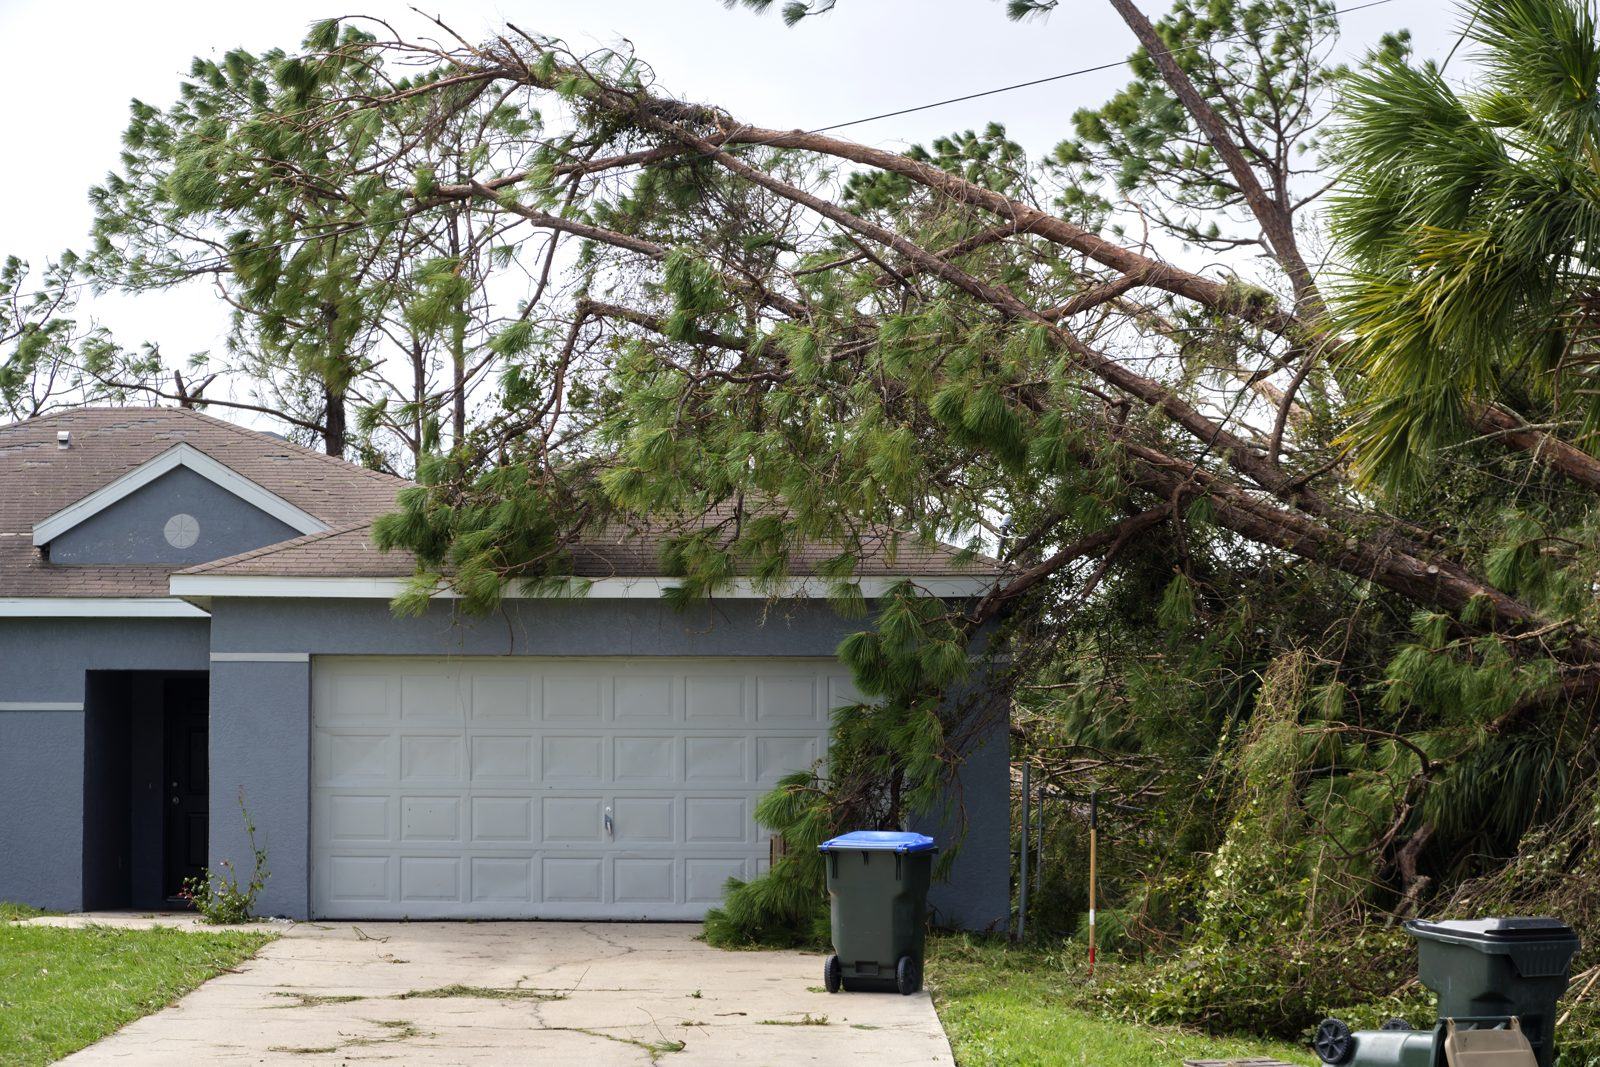
Neighbor’s Tree Fell on My House: Who Pays, and What About Removal?
Your own policy pays for the house whoever owned the tree; removal is capped near $500 or $1,000; the neighbor pays only if negligent. Florida and NJ rules.
By Alberto Enriquez
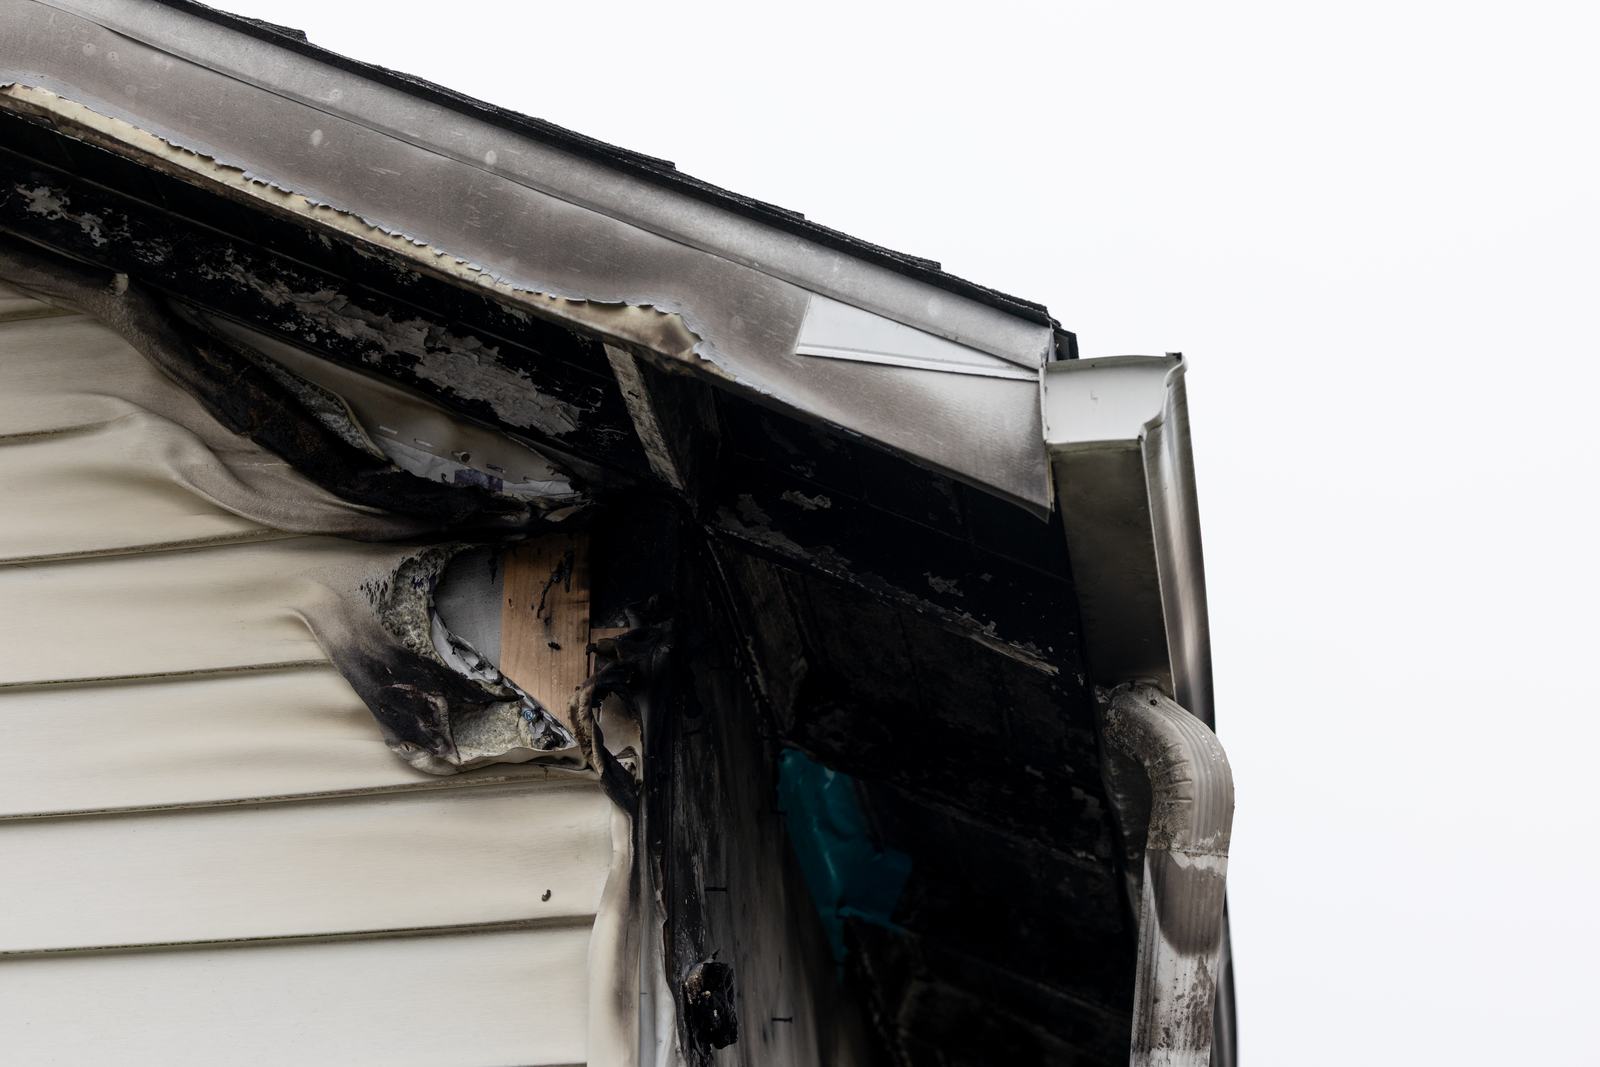
Lightning Strike and Power Surge Insurance Claims: A/C, Panels and Electronics
Lightning is a named peril on nearly every policy, and Florida leads the nation in lightning claims. What a strike or surge claim covers, and the proof that wins.
By Nelson Avila
Water Heater Leak or Burst: Is It Covered, and What the Claim Includes
A sudden water heater failure is covered; the heater itself usually is not, and a slow leak is excluded. What the claim includes and Florida's $10,000 water limit.
By Alberto Enriquez
Dishwasher, Washing Machine, A/C Line, Toilet or Refrigerator Leak: What Homeowners Insurance Covers
Sudden appliance leaks are covered; slow ones are not, and the appliance itself usually isn't. Dishwashers, washer hoses, A/C lines, toilets and icemakers explained.
By Nelson Avila
Roof Collapse and Structural Collapse Insurance Claims: What “Collapse” Coverage Pays
Collapse coverage pays for an abrupt falling down from hidden decay, insect damage, weight of snow or contents, not for sagging or cracking. FL and NJ inspection laws.
By Nelson Avila
Does Homeowners Insurance Cover Animal Damage? Rodents, Raccoons, Bears, Deer and Iguanas
Rodent, bird, insect and vermin damage is excluded; deer and bear damage is generally covered; the fire or water that follows chewed wiring usually is. FL and NJ specifics.
By Nelson Avila
Vandalism and Tenant Damage Insurance Claims: What’s Covered, What’s “Intentional”
Vandalism is covered unless the property sat vacant 60 days; the intentional-loss exclusion applies to the insured, not a tenant. Tenant damage, deposits and copper theft.
By Nelson Avila
Hail Damage Insurance Claims: Roof, Siding and the “Cosmetic Damage” Argument
Hail is covered under windstorm or hail; the fight is over cosmetic-damage endorsements, matching and roof deductibles. How hail damage is tested, FL and NJ rules.
By Nelson Avila
Homeowners
✉ Subscribe to NewsletterPreparing for a loss, living through one, and getting your claim paid fairly.

What to Do in the First 24 Hours After Property Damage
The first hours matter. Make the area safe, protect your property from further damage, document what you see, and call Homeland before you speak with the insurance company. Here is a clear checklist for what comes next.
By Nelson Avila
Surprising Things Your Homeowners Policy Might Actually Cover
An animal getting into the attic, a tree limb or other debris striking the house, a neighbor’s fire spreading to your property, even a vehicle or aircraft hitting your home: homeowners often assume these are on them. Many are handled the same way as other sudden, accidental damage.
By Nelson Avila
Ice Dams, Frozen Pipes and Snow-Load Roof Damage
Winter perils that barely register in Florida are routine in New Jersey. What to document for ice dams, frozen pipes and snow-load roof damage.
By Yeni MartinezCondo Unit Owners
✉ Subscribe to NewsletterYour unit, your policy and the association’s. Where one ends and the other begins.
Condo Owners: What the Association’s Policy Covers and What Yours Does
The association’s master policy generally covers the building and common areas, while your own policy is meant for what is inside your unit. Learn how to read the line between them.
By Nelson Avila
You Renovated Your Condo. Does Your Policy Know?
Unreported upgrades, like new floors or cabinets, can leave unit owners underpaid after a claim if the policy was never updated to reflect them.
By Nelson Avila
When a Neighbor’s Unit Catches Fire
Smoke and water damage from a fire that started in someone else’s unit is one of the most common multi-unit losses, and one of the most confusing to sort out between your policy, the association’s, and your neighbor’s.
By Nelson Avila
Buckled Tile, Warped Laminate: When Flooring Damage Is a Claim
Flooring that suddenly buckles or a laminate floor damaged by a leak can be a covered loss, but the cause matters. What separates a covered flooring claim from one insurers treat as gradual wear.
By Nelson Avila
Renters
✉ Subscribe to NewsletterYour belongings, your policy and your landlord’s. What renters should know.
Renters: Is Your Property Covered After a Loss?
Your landlord’s insurance generally protects the building, not your belongings. Learn what a renters policy may cover and what to keep on hand.
By Yisel Dieguez
A Neighbor’s Fire Damaged My Belongings. Now What?
When a fire starts in another unit but damages your things, whose policy responds, and in what order, is not always obvious. What renters should know before assuming nothing can be done.
By Yisel Dieguez
My Renters Claim Was Denied or Underpaid. What Are My Options?
Why renters claims get denied or lowballed, and what actually moves a decision when the inventory and documentation are strong.
By Yisel Dieguez
Landlords & Rental Property Owners
✉ Subscribe to NewsletterSingle-family rentals, multifamily and short-term rentals: protecting the property and the income.
Landlords: Documenting Damage and Lost Rent After a Loss
A rental loss affects the property, your tenant and your income. Learn what to document right away and which records to keep for the claim.
By Nelson Avila
Tenant-Caused Damage vs. a Covered Loss
Not all damage a tenant is involved in is treated the same way by a landlord’s policy. What’s usually covered, and where it gets contested.
By Nelson Avila
Vacant and Between-Tenancy Property Damage: Is It Covered?
Many landlord policies restrict coverage once a property has been vacant beyond a set number of days. Why the turnover window is a real exposure.
By Nelson Avila
Your Rental Was Used as an Unauthorized Grow Operation. What Happens to Your Claim?
A distinct damage pattern, and a claim that's easily mischaracterized if it's not handled carefully from the start.
By Nelson Avila
Business Owners
✉ Subscribe to NewsletterProtecting your property, your records and your income when a loss interrupts the business.
Keeping Your Business Records Ready for a Claim
A business claim is built on records. Learn which documents to keep together now, so they are ready if a loss interrupts your operations.
By Nelson Avila
Business Interruption: What Counts as Lost Income
Business interruption coverage replaces lost income while you get back to normal, but what counts as "normal" and "reasonable" often gets disputed.
By Nelson Avila
When a Supplier or Neighboring Business Closure Hits Your Bottom Line
Contingent business interruption coverage can respond to a loss that didn’t happen at your own property at all.
By Nelson Avila
Commercial Property Owners
✉ Subscribe to NewsletterLarger buildings, more moving parts. What owners and managers of commercial property should know.
Documenting a Commercial Property Loss: Where to Start
A commercial loss often involves tenants, contractors, multiple policies and a longer timeline. See how to document the damage and organize the claim from day one.
By Nelson Avila
Multi-Tenant Buildings: Whose Policy Covers What
A loss in a multi-tenant building rarely stays contained to one party’s responsibility. How it typically divides between owner and tenants.
By Nelson Avila
Code Upgrade and Ordinance-or-Law Coverage
Repairing to current building code can cost more than a standard policy pays for. Why this gap matters for older commercial buildings.
By Nelson Avila
Associations
✉ Subscribe to NewsletterFor condo, HOA, co-op and master association boards and managers.
Florida Condo Association Insurance Requirements (718.111(11)) and What Happens at Claim Time
What Fla. Stat. 718.111(11) requires the master policy to cover and exclude, the 3-year appraisal rule, how deductibles become assessments, and what it means at claim time.
By Nelson Avila
Before the Storm: What Your Association Should Have on File
Boards are responsible for the master policy and the common areas. Here is what to have on file before a storm, and who to call after one.
By Nelson Avila
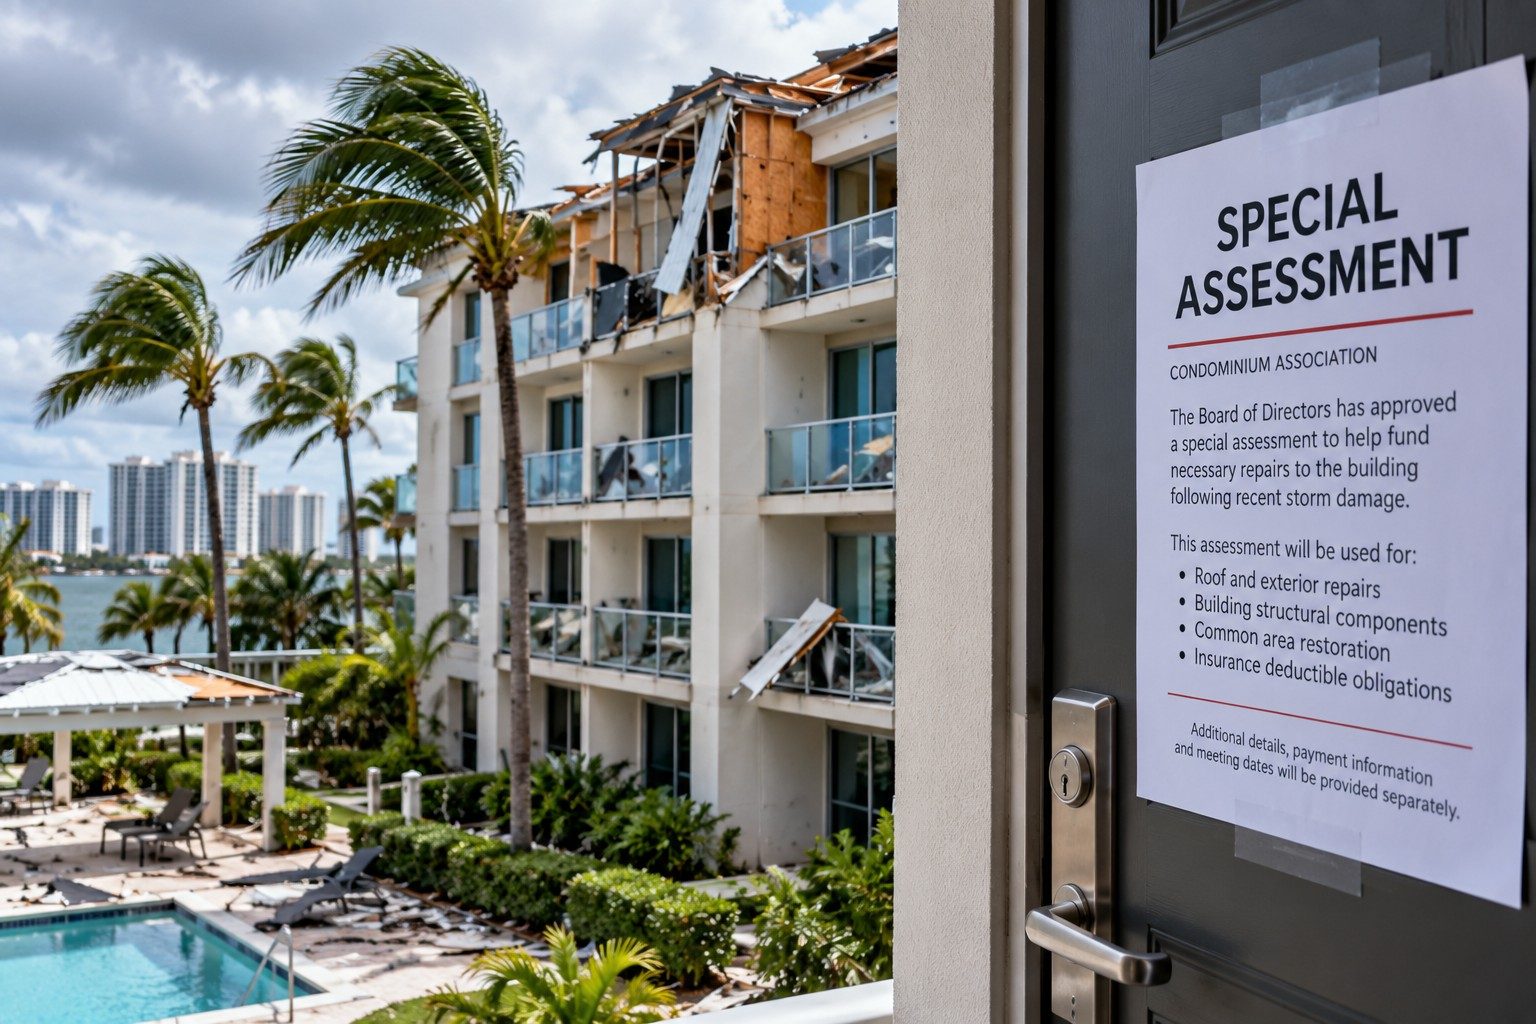
Special Assessments After a Major Loss
How an association’s insurance claim and a resulting special assessment typically interact, and why boards should coordinate them from the start.
By Nelson Avila
Common-Area Water Losses: Where the Policy Ends
A shared-system water loss can damage common areas and units at once. Where the master policy stops and a unit owner’s policy begins.
By Nelson Avila
Agricultural Property Owners
✉ Subscribe to NewsletterFor farms, groves, ranches, nurseries and stables across Florida and New Jersey.
Barn, Stable and Outbuilding Damage: What Your Policy Actually Covers
Barns, horse stables and equipment buildings carry their own coverage questions, separate from the farmhouse itself. What to check on your policy before a storm, not after.
By Nelson Avila
Open Land, Open Exposure: Wind and Tornado Risk on the Farm
Farmland and ranch structures sit in open terrain with little windbreak. Why that matters for wind claims, and how tornado-related damage is typically handled.
By Nelson Avila
Crop Insurance vs. Property Insurance: Where the Line Falls
Crop losses usually run through a separate USDA program, while barns, stables, irrigation systems and farmworker housing are property claims. Knowing which is which can save real time after a loss.
By Nelson Avila
Uninsured Clients
✉ Subscribe to NewsletterDamage without coverage does not always mean no options.
Damaged by Someone Else, With No Coverage of Your Own?
If someone else caused damage to your property and you are not covered, a claim against the responsible party’s insurance may be possible in Florida. Learn how the process starts.
By Nelson Avila
A Car, or a Plane, Hit My House. Who Pays?
A vehicle or aircraft striking a home is rare, but when it happens the driver or operator’s liability coverage, not just your own policy, may be the real path to getting made whole.
By Nelson Avila
A Contractor or Delivery Vehicle Damaged My Property. What Now?
Contractors, delivery trucks and service vehicles cause a specific, recurring kind of property damage. Whose insurance is supposed to respond.
By Nelson Avila

Your Insurance Company Has Adjusters. So Should You.™
Adjuster Advantage is a free membership with tools to know your coverage, keep your records ready and prepare before a storm, with a licensed Homeland public adjuster you can call.
For Property Owners
Policy Scan™, Safety Vault™, Certificate Pack™, Lifeline Card™, Renewal Radar™, 90DAY XPlus™, Prep Alerts and more.
Join Adjuster Advantage →For Community Associations
The master policy in plain words, a dated building record, reminders for the dates you enter, storm check-ins and a manager portfolio. Florida associations today.
Set Up Your Association →Joining Adjuster Advantage is free and does not create a contract or agreement with Homeland Public Adjusters for any claim. Hiring Homeland is optional and requires a separate written agreement.
Get Homeland Insights in Your Inbox
Pick the newsletters that fit you. Free, and you can unsubscribe anytime.
Free Claim Review
Have a loss or a claim question? Tell us about it.
Join Adjuster Advantage™
Know your coverage and keep your records ready, before the next loss.
Join Free