Multi-Tenant Commercial Buildings: Whose Policy Covers What

Homeland Public Adjusters · Last reviewed: October 2026
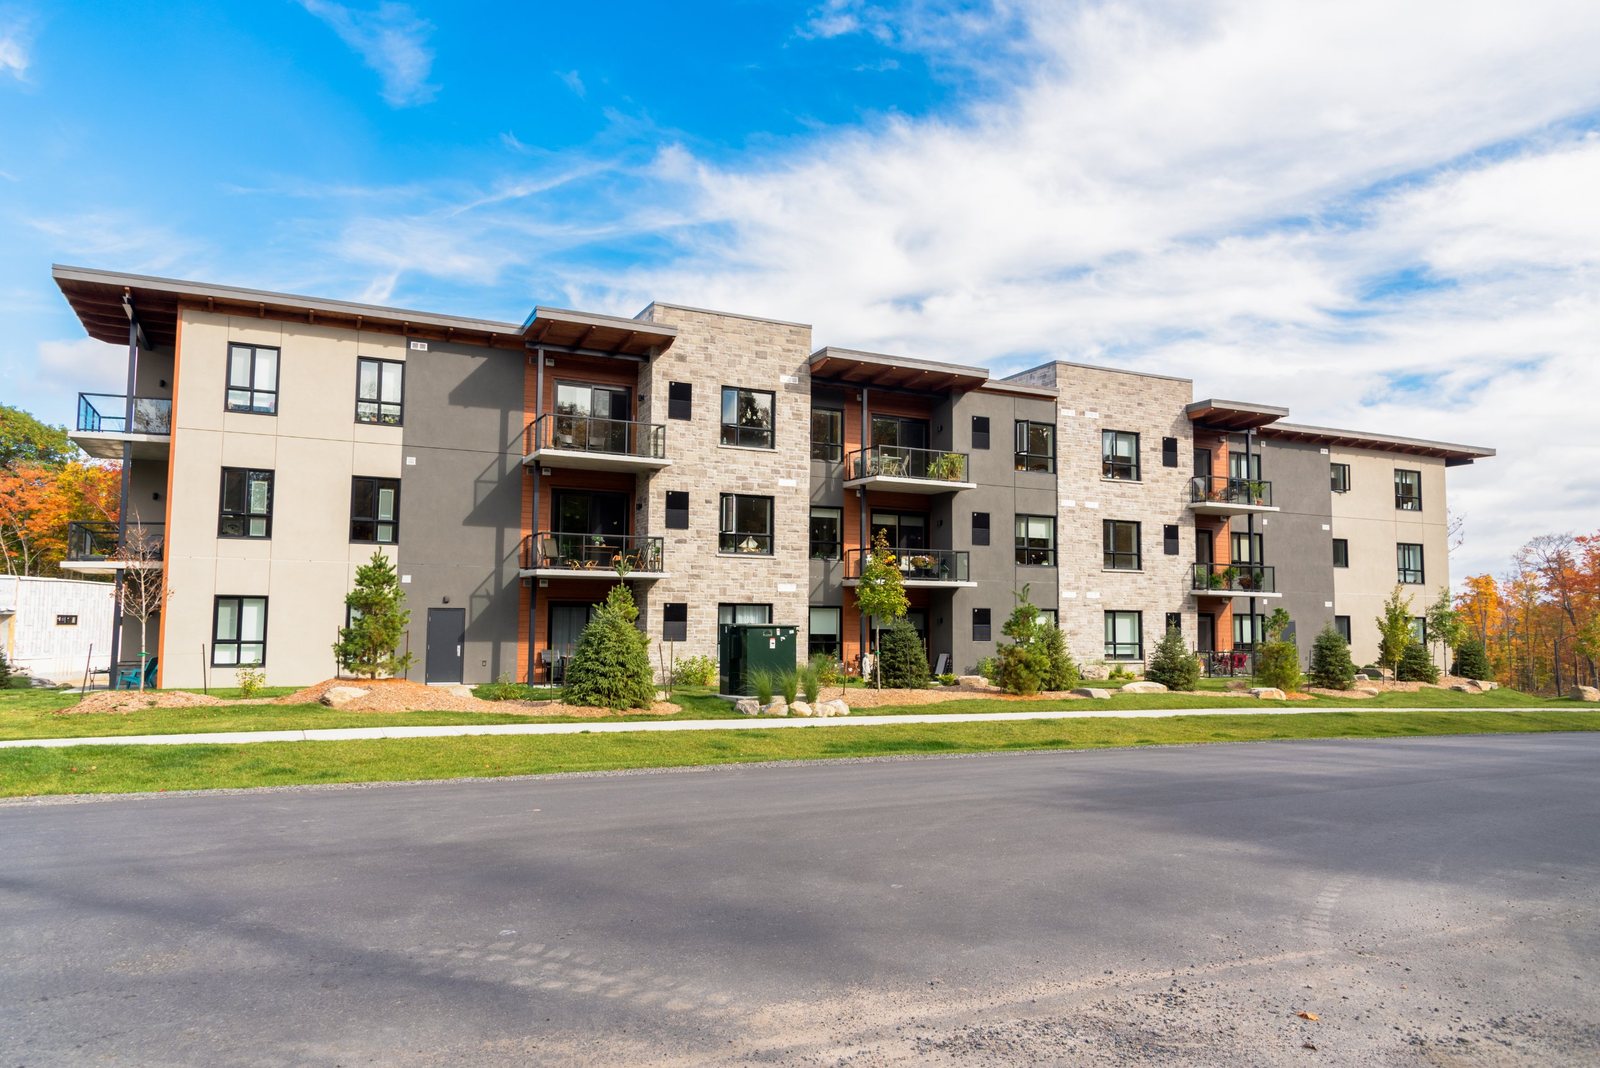
A fire, storm or water loss in a multi-tenant commercial building rarely stays contained to one party’s responsibility. The building owner’s policy, each affected tenant’s own business policy, and sometimes a tenant’s landlord-required liability coverage can all be in play on the same event.
Have a property claim anywhere in Florida? A licensed Homeland public adjuster comes to you within hours — no need to visit an office. Call (305) 783-3777 (Florida) or (732) 517-3777 (New Jersey), 24/7.
What the building owner's policy usually covers
Short answer: In a multi-tenant commercial building, the owner’s policy generally covers the structure, common areas and building systems, while each tenant’s policy covers its own improvements, business property and business interruption. The lease decides where the line falls, so one fire or water loss can mean several claims.
The structure itself, common areas and building systems — generally everything the lease defines as the landlord’s responsibility to maintain and insure.
What a tenant's own policy usually covers
The tenant’s own improvements and betterments, business personal property and equipment, and that tenant’s own business interruption.
When one tenant’s loss affects others, a fire or water loss that starts in one tenant’s space but spreads can leave neighboring tenants with their own claims against their own policies, even though they didn’t cause anything. If you’re a commercial property owner dealing with a multi-tenant loss, call Homeland before you speak with the insurance company. Sorting out which policy and which party is responsible for what is most of the early work on a claim like this.
Multi-tenant commercial buildings in Hialeah, Plantation and Elizabeth are a core part of Homeland's commercial caseload.
Frequently asked questions
Whose insurance pays after a loss in a multi-tenant commercial building?
Does the commercial lease affect who pays for damage?
This article is for general information only and is not legal or insurance advice. Every policy and every claim is different — call Homeland. We review your policy language with you at no cost.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewThis topic often comes up alongside Documenting a Commercial Property Loss: Where to Start. If your situation involves this kind of loss, see our Business & Commercial page for how Homeland can help with the claim itself.