Crop Insurance vs. Property Insurance: Where the Line Falls

Homeland Public Adjusters · Last reviewed: October 2026
A single storm can hit a farm on two fronts at once: the crops themselves, and the buildings and equipment that support them. These losses are almost always handled through two completely separate systems, and treating them as one claim — or filing in the wrong place — can slow down recovery on both.
Crop losses run through federal crop insurance
Losses to the crops themselves — yield loss from drought, flooding, wind, freeze or hail — are typically covered, if at all, through the USDA’s Federal Crop Insurance Program, administered through approved private insurers but backed by federal reinsurance and subsidy. This is a specialized system with its own enrollment deadlines, adjusters and claims process, separate from any standard commercial or farm property policy.
Buildings and equipment are property claims
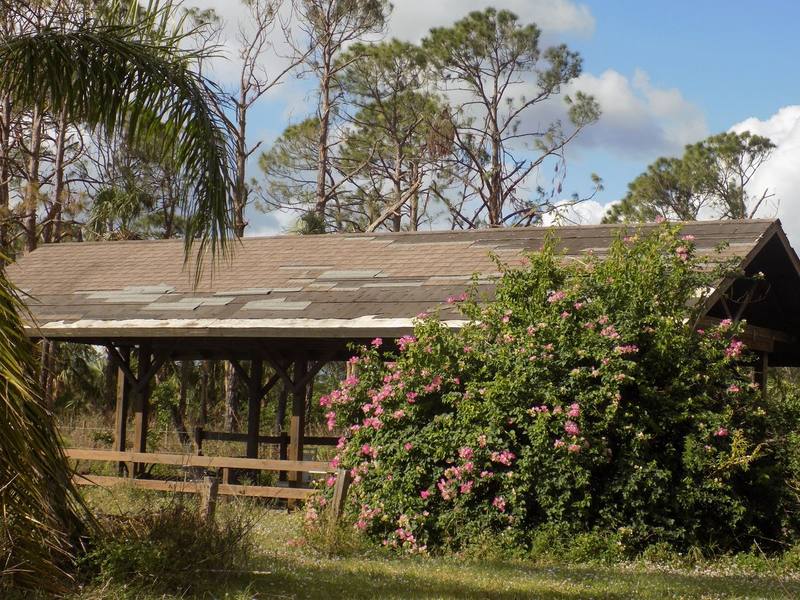
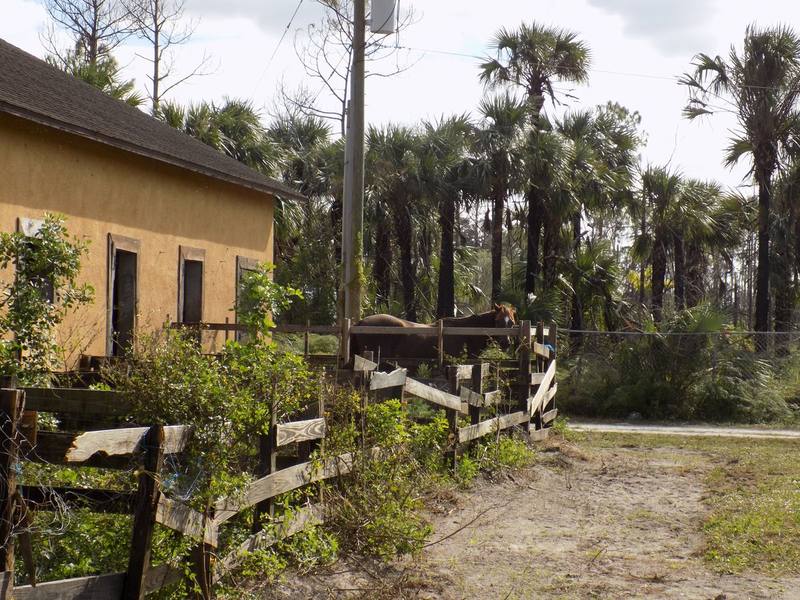
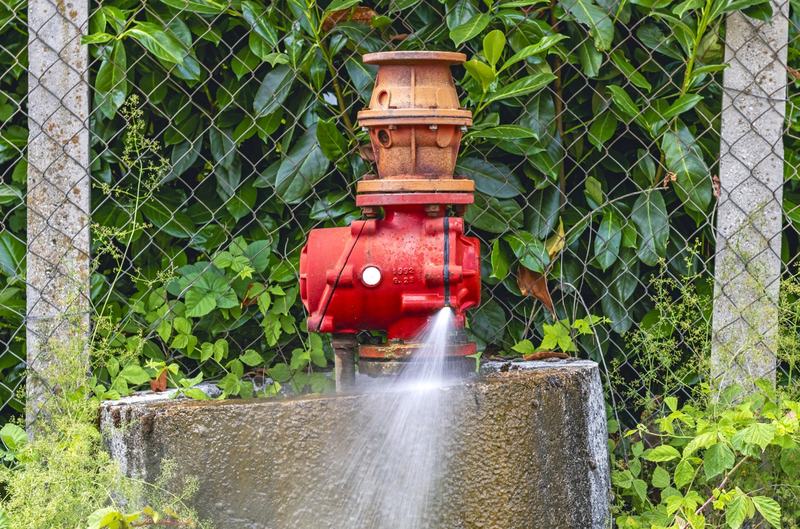
Barns, equipment sheds, irrigation systems, wells and pump houses, packing and storage facilities, and farmworker housing are property, not crops — and they’re covered (or not) under your farm or commercial property policy, the same as any other structure. A storm that knocks out an irrigation system’s wiring or damages a well pump is a property claim, even though the downstream effect is crop loss, and even though both losses stem from the same storm.
After a loss affecting both
Document structural and equipment damage the same way you would for any property claim — photos, repair estimates, a timeline of when the damage occurred — and file that claim with your property insurer. Separately, report crop losses to your crop insurance agent as soon as possible, since federal crop insurance programs often have strict notice deadlines that don’t align with property claim timelines.
Growers in Immokalee, Homestead and Belle Glade call Homeland when a storm damages the buildings and equipment behind the crop.
Frequently asked questions
Is crop loss covered by my farm property insurance?
Is storm damage to an irrigation system a crop claim or a property claim?
What should I do if one storm damages both my crops and my farm buildings?
This article is for general information only and is not legal or insurance advice. Every policy and every claim is different — always review your own policy language or speak with a licensed public adjuster about your specific situation.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Car or Plane Hit My House: Who Pays?
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewThis topic often comes up alongside Barn, Stable and Outbuilding Damage: What Your Policy Actually Covers. If your situation involves this kind of loss, see our Agricultural Properties page for how Homeland can help with the claim itself.