
Scan My Policy
What the Scan Tells You
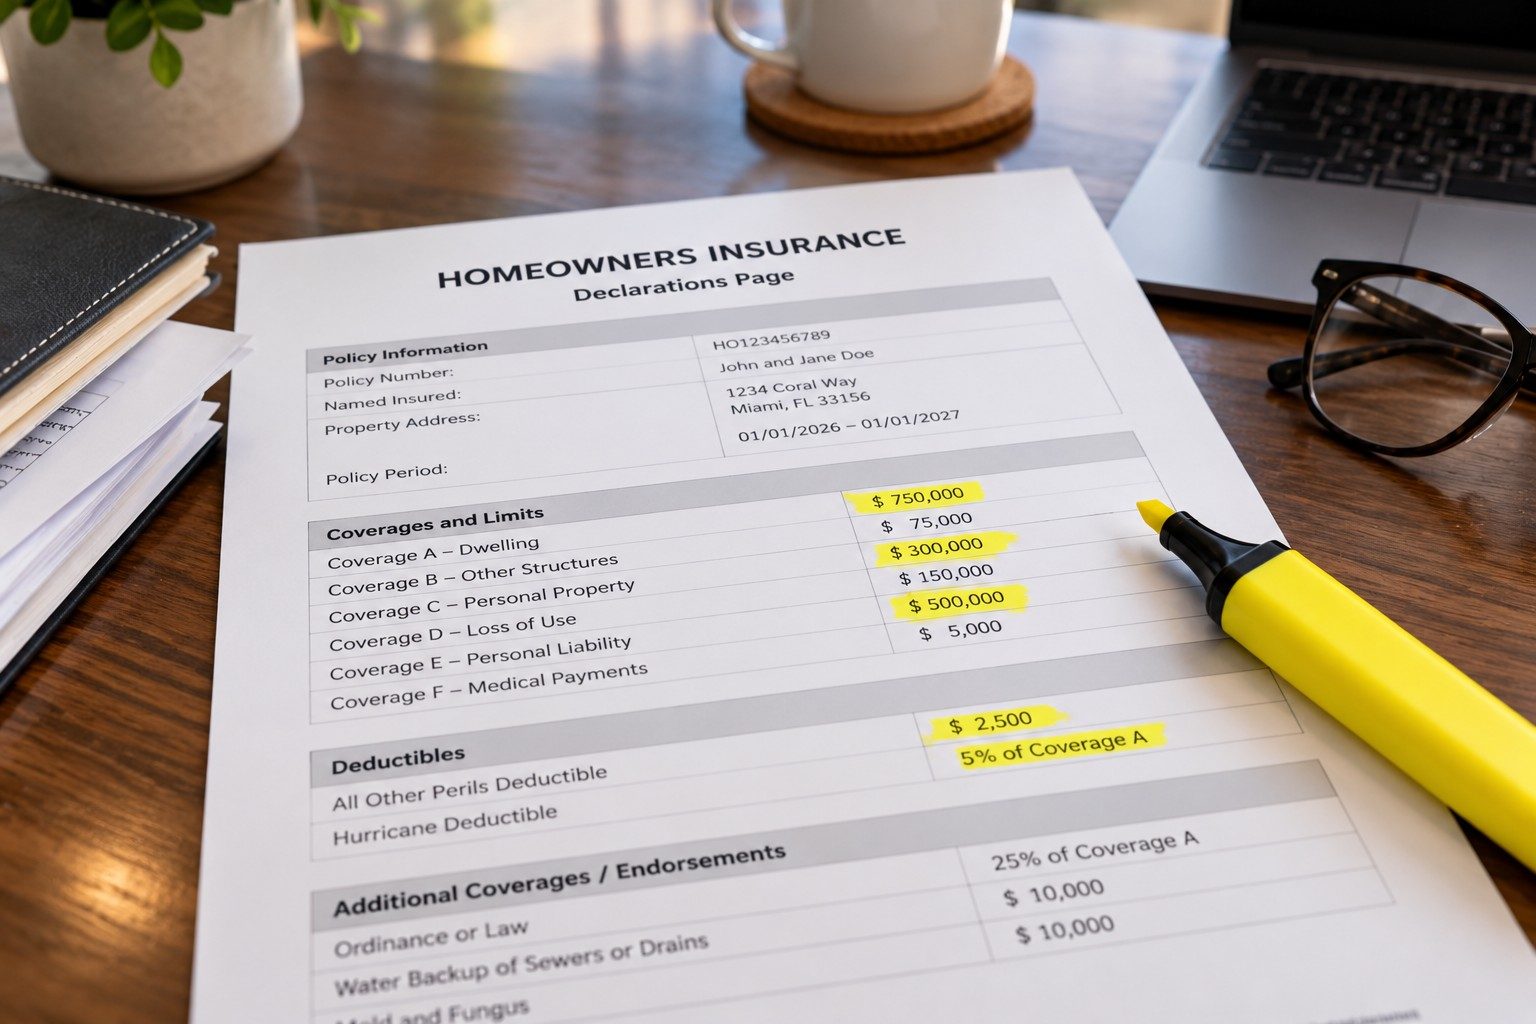
The declarations page is the one or two pages at the front of your policy that list your coverages, limits, deductibles and endorsements. It is also where the surprises live: the hurricane deductible that is a percentage, the water-damage sublimit, the roof paid at actual cash value, the cosmetic-damage exclusion. Homeland's licensed public adjusters read these pages on every claim. Policy Scan reads yours now.
How It Works
Watch a sample policy get scanned
Scroll down. Each gap lights up on the declarations page and the score drops, the way Policy Scan scores it.
Every policy starts at 100.
How well your policy covers the common gaps Policy Scan checks for. Every policy starts at 100 and loses points for each gap. It is not your Claim Readiness.
Water damage is capped at $10,000 per loss
A water loss bigger than this amount won’t be paid in full, even though your dwelling limit is higher.
The wording in this sample policy: "The most we will pay for all damage caused by the discharge or overflow of water or steam is $10,000 per loss, regardless of the Coverage A limit shown in the Declarations."
Right to repair: the insurer can choose to repair instead of paying
The insurer can send its own contractor instead of paying you, so you lose control over who repairs your home and how.
The wording in this sample policy: "If we elect to repair, we will select the contractor. Our election to repair replaces your right to receive payment for the cost of repairs."
Roof paid at actual cash value once it’s 10 years old
Once the roof reaches that age, roof damage is paid minus depreciation, which can leave you paying for much of a new roof.
The wording in this sample policy: "When the roof surface is 10 years old or older at the time of loss, we will pay actual cash value for damage to roof surfacing."
Hurricane deductible is 5% = $17,500
You pay this amount on a hurricane claim before the policy pays anything. The target is 2%.
The wording in this sample policy: "Hurricane: 5% of Coverage A ($17,500). All Other Perils: $2,500."
Matching is limited to 2% of Coverage A
The policy limits what it pays to make repaired areas match the rest (roof shingles, flooring, cabinets).
The wording in this sample policy: "The most we will pay to repair or replace undamaged material so it matches is 2% of the Coverage A limit."
Mold coverage is only $5,000
Mold removal often costs more than $10,000.
The wording in this sample policy: "The most we will pay for fungi, wet or dry rot is $5,000 per loss, as additional coverage."
62 / 100: Significant gaps.
Six gaps worth confirming, found before any storm, while there is still time to change the policy at renewal.
Questions about your policy or a claim? Call Homeland first: (305) 783-3777 Florida · (732) 517-3777 New Jersey.
Sample policy with a made-up insurer, scored with the same rules as Policy Scan in the Adjuster Advantage app. Policy Scan and the Coverage Preparedness Score are educational assessments under the Adjuster Advantage by Homeland Public Adjusters framework. They are based on the policy review provided and do not guarantee coverage or claim payment.
Your Policy Summary
Read from the page you uploaded. Anything the page did not show is marked "not shown."
How do I find out what my property policy actually covers?
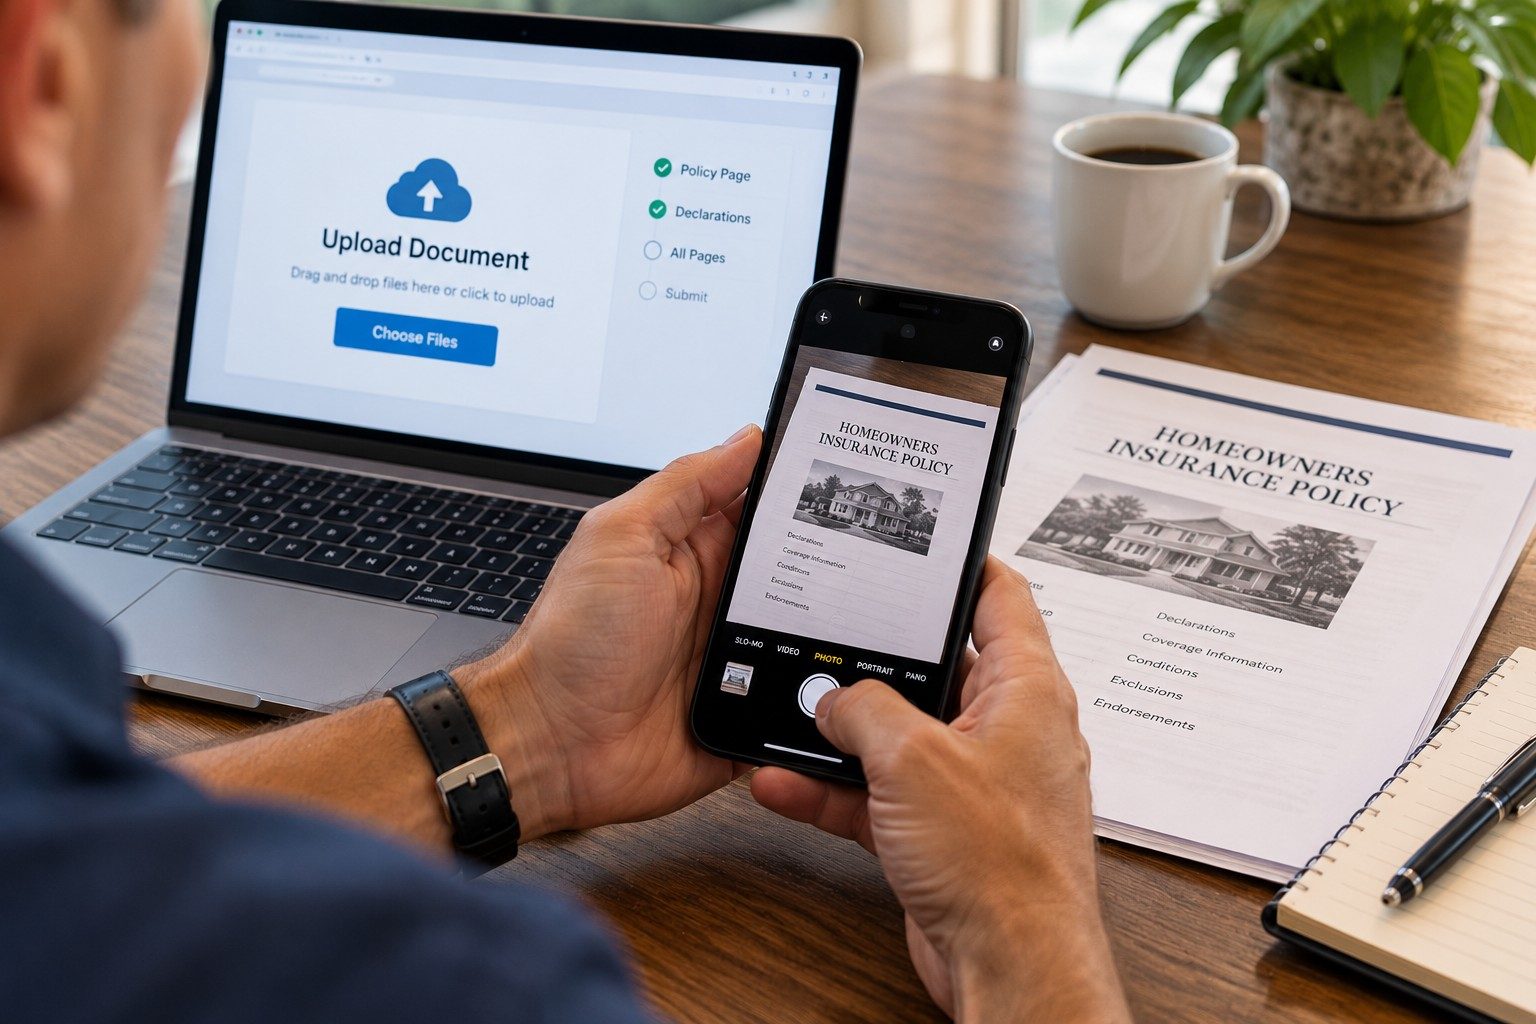
Most policyholders find out what their policy covers after the loss, from the insurer. Policy Scan reads your declarations page before the loss and tells you, in plain English, your coverage limits, every deductible in dollars, and the endorsements and sublimits most likely to reduce a claim payment. Free, no obligation, and the document is never stored.
Policy Scan FAQs
Is Policy Scan free?
Is my policy document stored?
What should I upload?
Is the summary insurance or legal advice?
I already have damage. Should I use Policy Scan or call?
What does Policy Scan look for?

Adjuster Advantage: the perfect complement to your insurance
The Policy Scan is one tool. Adjuster Advantage app users get the full set to prepare for any loss before it happens: a dated record of the home and its contents, storm prep and check-ins, deadline reminders, and a licensed public adjuster on call when something does happen. Free to join.