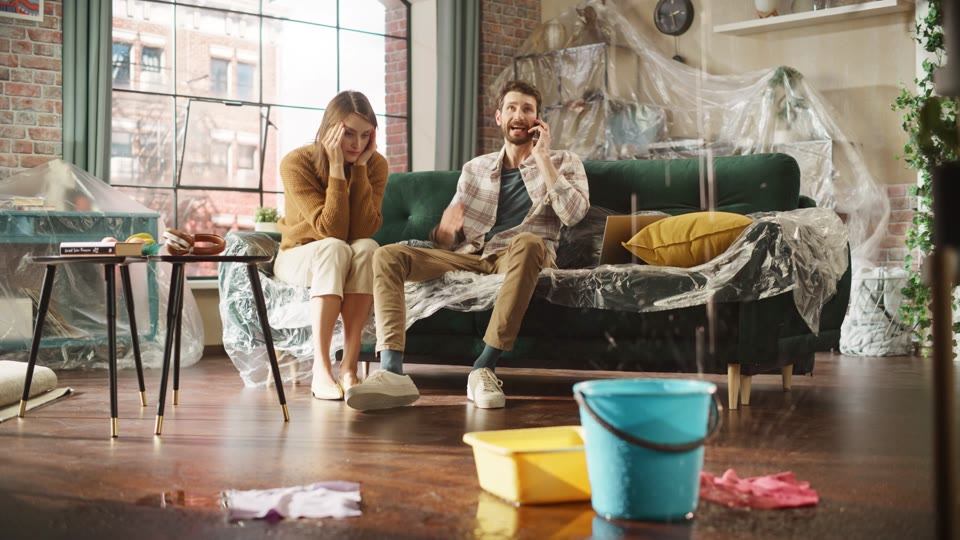
Couple sitting on a plastic-covered sofa with a bucket catching a water leak in their rental
CLIENTS SERVED

Renters Insurance Claims

Renters insurance claims in Florida and New Jersey. Your landlord insures the building — your belongings are on you.

Renting, with damage anywhere in Florida? A licensed Homeland public adjuster comes to you within hours — no need to visit an office. New Jersey: we come to you statewide.

Homeland Public Adjusters helps renters in Florida and New Jersey after fires, water damage, storms, and break-ins. We document your belongings and your living expenses, review your renters policy, and present the claim to the insurance company on your behalf.

Last reviewed: October 2026

How Can We Help You Recover, or Prepare?

FLORIDA

Renters Insurance Claims in Florida

Florida renters face hurricane and wind damage, water leaks from the unit above, fires, and break-ins, and they often learn after the loss that the landlord’s insurance covers the building but not their belongings. Homeland represents renters with contents and living-expense claims, in Miami-Dade, Broward, Palm Beach and across the state.
NEW JERSEY
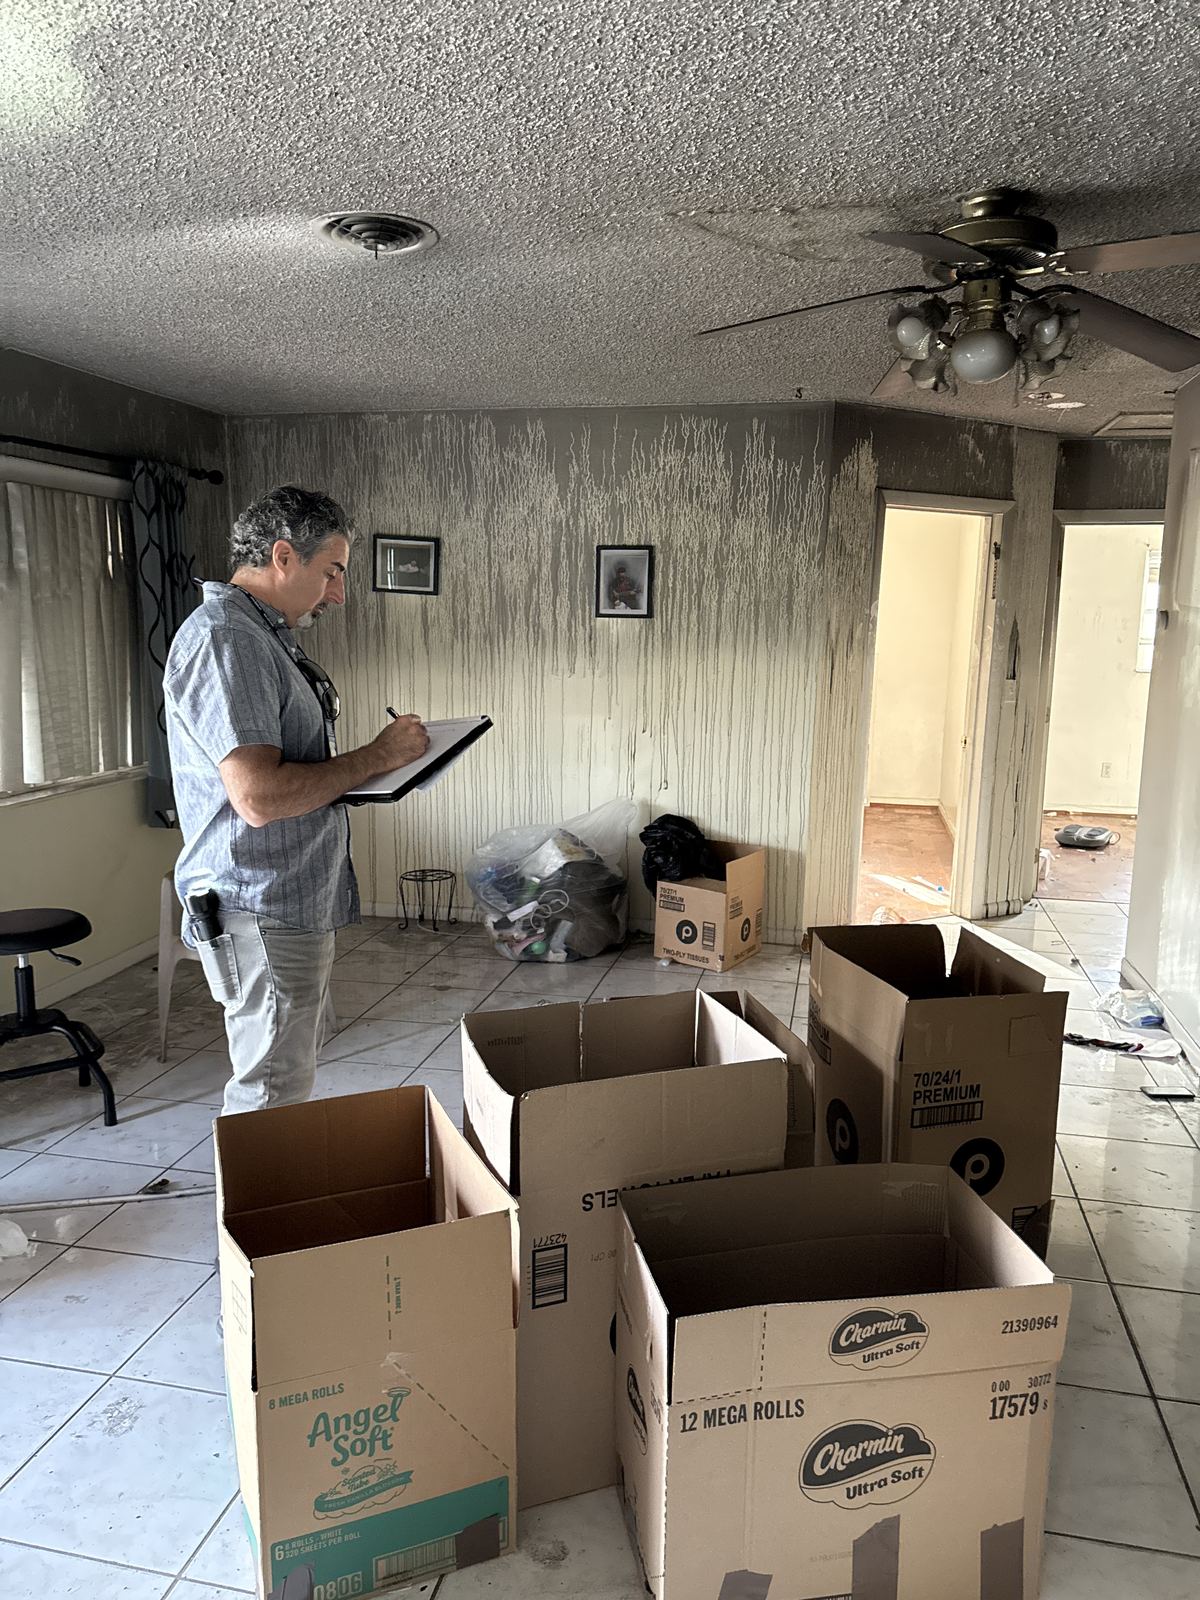
Public adjuster photographing and listing damaged personal property for a renters insurance contents inventory
A renters claim is a contents claim. Every item is photographed, described and priced before the inventory goes to the insurer.

Renters Insurance Claims in New Jersey

New Jersey renters in apartments, townhomes and shore rentals deal with nor’easters, flooding, fires, burst pipes and water from neighboring units, and theft. Homeland represents New Jersey renters with these losses, in New Brunswick, Elizabeth and across the state.

Handling a Renters Insurance Claim

A renters policy generally covers your belongings, may pay for temporary living costs if a covered loss makes your home unlivable, and may include personal liability coverage. It usually does not cover the building itself, which is your landlord’s responsibility and your landlord’s policy. Limits, deductibles, and special limits on items like jewelry, cash, and electronics vary by policy.

Homeland Public Adjusters helps renters document what they owned, what was lost or damaged, and what it costs to replace it, and presents the claim to the insurance company on your behalf.
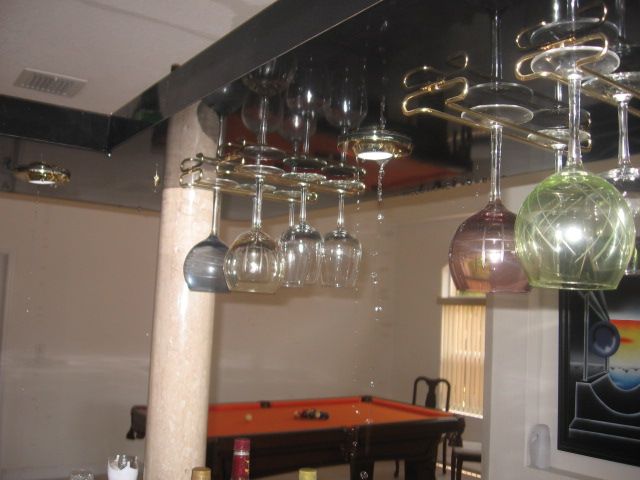
Water dripping from the ceiling onto a glass rack and bar area from the unit upstairs
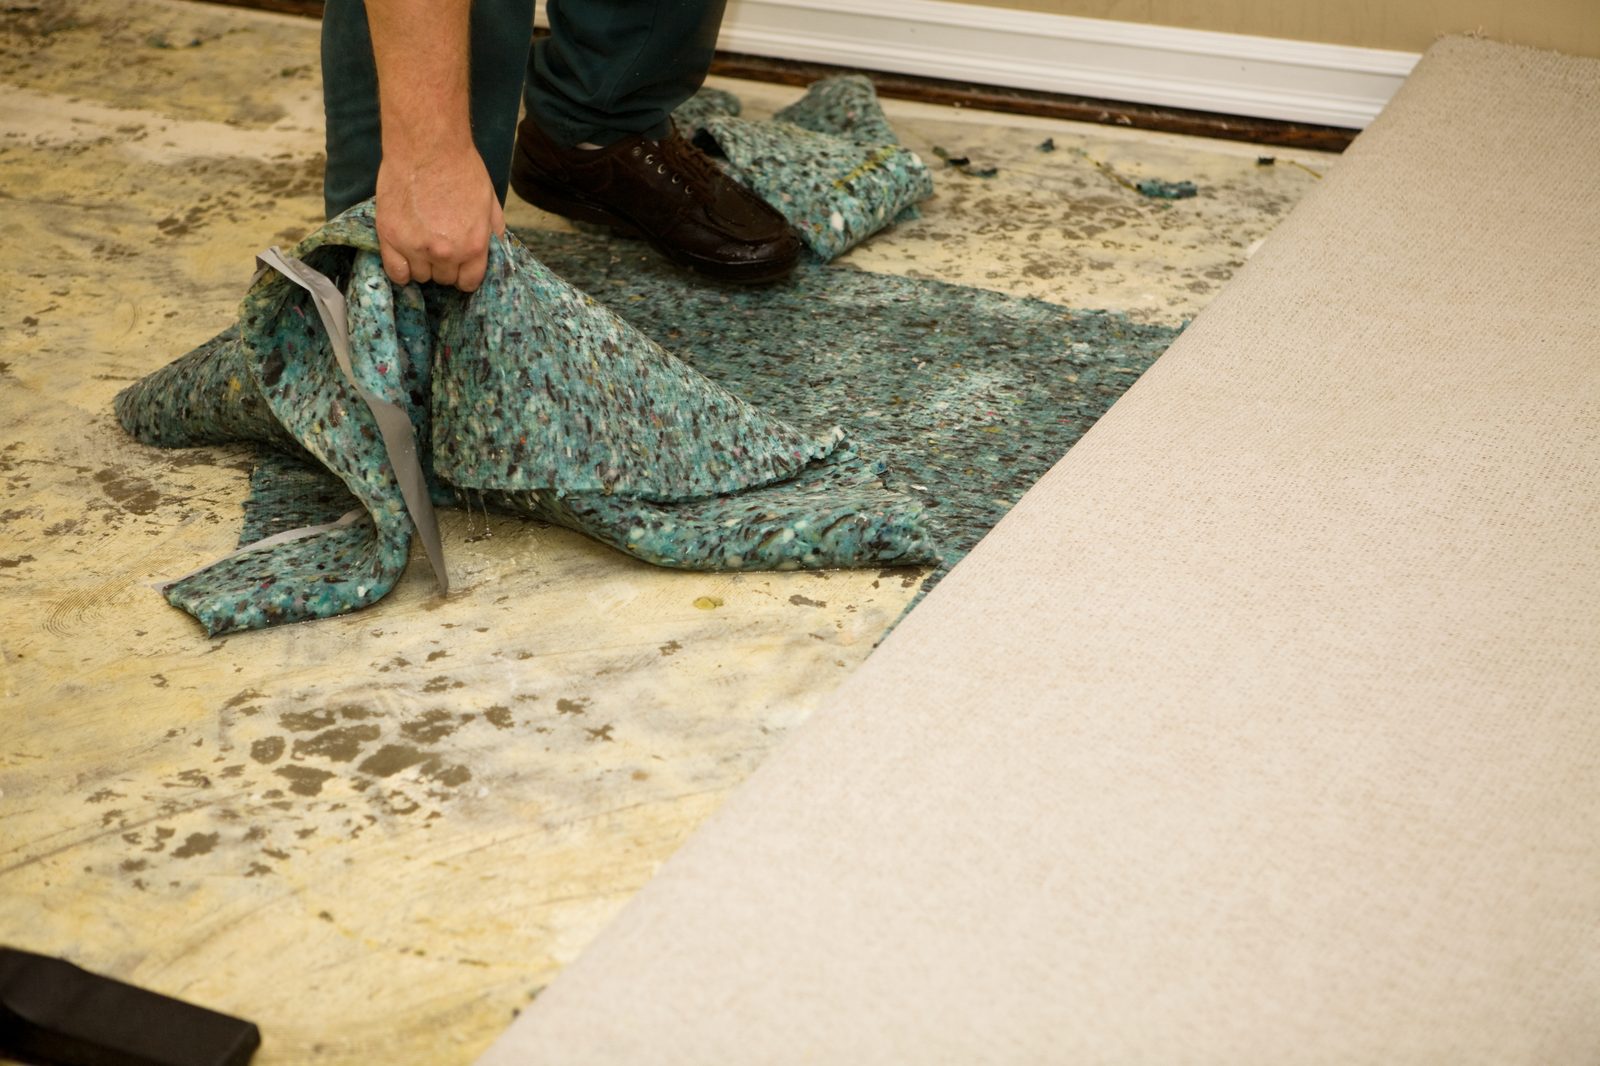
Pulling up moldy, water-damaged carpet in a rental unit

Your Policy and Your Landlord’s Policy

Your renters policy is for your belongings, your living expenses if you cannot stay, and your liability. Your landlord’s policy is for the building. After a fire, a leak or a storm, the landlord’s insurance may repair the structure, but it generally does not replace your furniture, clothing, electronics or other belongings. That is what your renters policy is for. If you do not have one, see the last question below.

Common Renters Losses

Fire and smoke in your unit or building
Water from a neighbor’s unit or a burst pipe
Roof leaks and wind-driven rain
Hurricane and storm damage to belongings
Theft and burglary
Vandalism
Lightning and power surges
A vehicle striking the building
Belongings damaged during repairs
A home that is unlivable after a covered loss

Proving What You Owned

Contents claims depend on a clear inventory. Go room by room and list each item with a description, age, and value, then add photos, receipts, serial numbers, and bank or card records where you have them. Some policies pay replacement cost and others pay actual cash value, which subtracts depreciation, so check which one yours is. Dated photos taken before a loss make this far easier, which is what Safety Vault™ is for.

Living Expenses When You Cannot Stay Home

If a covered loss makes your home unlivable, your policy may pay additional living expenses, often called loss of use: a hotel or temporary rental, extra costs beyond your normal rent, and similar expenses, subject to the policy’s limits and time period. Keep every receipt and a record of your normal monthly costs.

What to Do After a Renters Loss

1
Make safety the priority: Get everyone, including pets, to a safe place and stay out of unstable or damaged areas.
2
Notify your landlord or manager in writing: Report the damage and keep a copy, with the date.
3
Let Homeland notify the carrier: Call us before you speak with the insurance company. Hire us, and we’ll submit the notice of loss and handle every carrier conversation from there.
4
Document the damage: Photograph and video the damage and your belongings before cleanup, and keep damaged items until they are documented.
5
Protect what you can: Move undamaged belongings to a safe place and take reasonable steps to prevent more damage.
6
Start your inventory: List what was lost or damaged, room by room, with descriptions, ages and values.
7
Keep every receipt: Save receipts for emergency purchases, a hotel or temporary housing, and other costs caused by the loss.
8
Report theft or vandalism: Call the police and keep the report number. Save any camera footage.
9
Keep your communications: Save emails, texts and letters with your landlord, the building manager and the insurer.
10
Speak with a public adjuster: Contact Homeland Public Adjusters before accepting a settlement or signing a release so we can review the claim and the policy.
ADJUSTER ADVANTAGE™ · FREE APP

You Don’t Have to Remember All of This. Adjuster Advantage Has You Prepared.

The best way to prepare for a loss as a renter is the free Adjuster Advantage app, so your belongings are documented before anything happens.

Safety Vault™
Dated photos and documents of your belongings in one place.
Policy Scan™
A licensed Homeland adjuster explains your policy in plain words.
Damage Guide™
Safety first, how to document, and how insurance works.
Lifeline Card™
Shutoffs and emergency contacts, available offline.
Renewal Radar™
See what changed from one policy year to the next.
90DAY XPlus™
Reminders before the dates you enter, such as your policy renewal.
FOR CONDO, HOA, CO-OP AND MASTER ASSOCIATIONS

Does your building have a condo or HOA board?

Boards and managers can join too. AA Associations gives them the master policy explained in plain words, a dated building record, reminders and Building Storm Check-in. For Florida associations today.

Get the App for Your Association →

Joining Adjuster Advantage is free and does not create a contract or agreement with Homeland Public Adjusters for any claim. Public adjusting services require a separate written agreement.

Renters Claims by the Numbers

Renters by the numbers
55%Share of renter households with renters insurance; nearly half have no coverage (National Apartment Association via Harvard JCHS)
0.2%Share of residential NFIP flood coverage held by renters, who occupy 34.8% of U.S. homes (JCHS)
$171Average annual renters insurance premium in 2022 (III)
32% / 36%Renter-occupied share of homes in Florida and New Jersey (Census, 2020–24)

The Coverages That Decide a Renters Claim

A renters policy (HO-4) is short, and the parts that matter after a loss are these:

ProvisionWhat it doesWhere claims go wrong
Personal property (Coverage C)Your furniture, clothing, electronics and belongings, usually paid at actual cash value unless replacement cost was addedDepreciation on everything; inventory limited to what you remember without photos and receipts
Loss of useHotel, temporary rent above your normal rent, meals and moving costs while the unit is uninhabitableCut off early, or not offered because the landlord’s adjuster never mentions it
Landlord’s policyCovers the building only; it does not cover your contents or your living expenses, even when the building is at faultTenants wait on the landlord’s claim and miss their own policy’s notice conditions
Special limitsCaps on jewelry, cash, firearms, business property and property away from the premises (often 10% of Coverage C)High-value items paid at the sublimit without a schedule
Improvements and bettermentsSmall limit (often 10% of Coverage C) for upgrades you paid for inside the unitNot claimed at all
FloodNot covered by a renters policy; an NFIP contents-only policy is separate and has a 30-day waiting periodGround-floor renters in flood zones assume the building’s policy covers them

Deadlines to Know

Florida. Florida law requires notice of an initial or reopened property claim within 1 year after the date of loss, and notice of a supplemental claim within 18 months. Your insurance company generally must acknowledge your claim within 7 calendar days and pay or deny within 60 days after receiving notice, and Florida defines residential coverage to include tenant policies. Your policy may include its own requirements, so call Homeland first: we give your insurer notice and meet every deadline for you.
Sources: Sections 627.70132, 627.70131 and 627.4025, Florida Statutes.

New Jersey. New Jersey regulations require insurers to begin an investigation within 10 working days of notice of a claim, and set a 30-calendar-day period, running from receipt of a properly executed proof of loss, for first-party claims. If more time is needed, the insurer must explain why in writing, with updates every 45 days, unless a clear justification or other law provides otherwise.

Why Choose Homeland for a Renters Claim?

Policyholder-only representation: Homeland works for renters, homeowners, businesses and associations, not insurance carriers.
Contents documentation: We help organize inventories, photos, receipts and records so every item is supported.
Living expense support: We help document additional living costs when a home is unlivable.
Policy review: We review your coverage, limits, deductibles and special limits.
Carrier communication: We communicate with the insurance company and its adjusters for you.
Denied and underpaid claims: We review claims that were denied or paid less than expected.
Florida and New Jersey: We represent renters in both states.
Serving property owners since 2006.
No Recovery, No Fee.

In the News: A Real Renters Claim

In the News. According to NBC 6 South Florida, when a fire caused part of a Miami-Dade apartment building to collapse in January 2023, displacing nearly 200 people, the building manager made a point that every renter should hear: a landlord's or association's insurance policy — if one even exists — does not cover a tenant's own furniture, electronics, clothing, or documents. Without a separate renter's insurance policy, those losses simply aren't reimbursed by anyone. The lesson for any renter in Florida or New Jersey is that personal belongings need their own coverage, separate from whatever the building carries, and that filing a renter's insurance claim after a fire, storm, or burst pipe can still be a confusing, adversarial process. If an insurer is undervaluing or delaying a renter's claim for lost belongings, Homeland Public Adjusters can help renters understand their policy and fight for a fair settlement.

Renters FAQs

Does my landlord’s insurance cover my belongings?
Your own renters policy is what covers your belongings. The landlord’s policy is for the building, so it generally does not cover them.
What is loss of use or additional living expense?
If a covered loss makes your home unlivable, your renters policy may pay certain extra living costs, such as a hotel or temporary rental, subject to its limits and time period. Keep every receipt.
Replacement cost or actual cash value?
Replacement cost coverage pays to replace an item with a similar new one. Actual cash value subtracts depreciation. Your policy says which applies, and we review it with you.
How do I prove what I lost?
Build a room-by-room inventory with descriptions, ages and values, then add photos, receipts, serial numbers and card or bank records. Dated photos taken before a loss, for example in Adjuster Advantage Safety Vault, make this much easier.
The damage came from my neighbor’s unit. Can I still file?
Yes. Your renters policy may cover your belongings no matter whose unit the water or fire started in. Call us first, document the damage, and we will handle reporting it to your insurer.
I do not have renters insurance. Can Homeland help?
Without a policy there is no claim under your own insurance. In Florida, if someone else’s insured loss damaged your property, see Third Party Uninsured Damage Claims. This service is not available in New Jersey.
Can a public adjuster help with a renters insurance claim?
Yes. A renters policy is a property policy, and the same rules apply: you have to document what was damaged and what it's worth, the insurer's adjuster works for the insurer, and the burden of proving the claim is on you. A public adjuster carries that work for you: inventorying your belongings, valuing them under your policy's replacement-cost or actual-cash-value terms, documenting loss of use and negotiating the claim. Homeland handles renters claims in Florida and New Jersey on a No Recovery, No Fee basis, and both states protect you with fee rules: Florida caps public adjuster fees by statute and New Jersey requires the contract to state the maximum fee.
More Questions? See Our Full FAQ →

Insights

View All Posts

Renters Claims We Handle Across Florida & New Jersey

Homeland handles renters claims throughout Florida and New Jersey. Wherever you rent in either state, call us 24/7.

Related Coverage
Damage happening now? In Florida
Call (305) 783-3777, 24/7
In New Jersey
Call (732) 517-3777, 24/7

Talk to a Public Adjuster

How Can We Help You Recover, or Prepare?

Tell us about your loss. We’ll call you back.

Claims We Handle

Hurricane & Wind Damage→Flood Damage→Fire Damage→Water Damage→Winter Storm & Roof Damage→Theft & Vandalism Damage→Vehicle Impact Damage→Business & Commercial→Other Claims→Denied & Underpaid→
FREE APP

Get the Adjuster Advantage™ App

Get the App
Board or manager? AA Associations →

Other Property Damage Claims We Handle

Renters’ losses usually begin with a specific type of damage. Homeland Public Adjusters assists renters with each of these covered losses.

How Can We Help You Recover, or Prepare?

Need Help With a Renters Claim?

Losing your belongings and your home at once is hard enough without a complicated insurance claim. Call us 24/7 or request a free review, and we will explain your options and the next steps.

Or call 24/7: (305) 783-3777 Florida · (732) 517-3777 New Jersey. Hablamos español.

We Handle
Business Interruption Claims
We Serve
Cargo & Fleet
We Serve
Daycare & Child Care Owners
We Serve
Law Firms
We Handle
Water Damage
We Serve
Church, School & Nonprofit Owners
We Serve
Spoilage & Power Outage
We Serve
Third Party Uninsured Property Owners
We Handle
Vehicle Impact Damage
We Serve
Builders Risk
We Serve
Contractor's Equipment
We Serve
Cyber & Systems Losses (FL)
We Handle
Lightning, Falling Tree & Other Sudden Damage
We Serve
Homeowners
We Handle
Winter Storm & Roof Damage
We Handle
Power Surge Damage
We Handle
Business & Commercial Claims
We Handle
Commercial & Specialty Claims
We Serve
Hotel & Motel Owners
We Handle
Sewer & Drain Backup Damage
We Serve
Auto Shop & Dealership Owners
We Serve
Large Loss Claims
We Serve
Multifamily & Apartment Owners
We Handle
Tornado Damage
We Handle
Vandalism & Riot Damage
We Serve
Medical & Dental Office Owners
We Handle
Sinkhole Damage
We Serve
Marina & Boat Owners
We Serve
Government & Municipal Property Owners
We Serve
Agricultural Property Owners
We Serve
Condo & HOA Associations
We Handle
Hail Damage
We Serve
Mobile & Manufactured Homeowners
We Handle
Wildfire & Brushfire Damage
We Handle
Hurricane & Wind Damage
We Serve
Boats & Yachts
We Serve
Warehouse & Industrial Owners
We Serve
Business Income & Extra Expense
We Serve
Retail Store & Strip Center Owners
We Handle
Lightning Strike Damage
We Handle
Flood Damage
We Handle
Fire Damage
We Serve
Restaurant Owners
We Handle
Smoke Damage
We Serve
Vacation & Short-Term Rental Owners
We Handle
Falling Tree & Debris Damage
We Serve
Marinas, Boatyards & Dealers
We Handle
Denied & Underpaid Claims
We Handle
Theft & Vandalism Damage
We Serve
Landlords & Rental Properties
We Handle
Appliance Leak Damage
We Handle
Mold Damage
We Handle
Vehicle Impact Damage
We Handle
Business Interruption Claims
We Serve
Cargo & Fleet
We Serve
Daycare & Child Care Owners
We Serve
Law Firms
We Handle
Water Damage
We Serve
Church, School & Nonprofit Owners
We Serve
Spoilage & Power Outage
We Serve
Third Party Uninsured Property Owners
We Handle
Vehicle Impact Damage
We Serve
Builders Risk
We Serve
Contractor's Equipment
We Serve
Cyber & Systems Losses (FL)
We Handle
Lightning, Falling Tree & Other Sudden Damage
We Serve
Homeowners
We Handle
Winter Storm & Roof Damage
We Handle
Power Surge Damage
We Handle
Business & Commercial Claims
We Handle
Commercial & Specialty Claims
We Serve
Hotel & Motel Owners
We Handle
Sewer & Drain Backup Damage
We Serve
Auto Shop & Dealership Owners
We Serve
Large Loss Claims
We Serve
Multifamily & Apartment Owners
We Handle
Tornado Damage
We Handle
Vandalism & Riot Damage
We Serve
Medical & Dental Office Owners
We Handle
Sinkhole Damage
We Serve
Marina & Boat Owners
We Serve
Government & Municipal Property Owners
We Serve
Agricultural Property Owners
We Serve
Condo & HOA Associations
We Handle
Hail Damage
We Serve
Mobile & Manufactured Homeowners
We Handle
Wildfire & Brushfire Damage
We Handle
Hurricane & Wind Damage
We Serve
Boats & Yachts
We Serve
Warehouse & Industrial Owners
We Serve
Business Income & Extra Expense
We Serve
Retail Store & Strip Center Owners
We Handle
Lightning Strike Damage
We Handle
Flood Damage
We Handle
Fire Damage
We Serve
Restaurant Owners
We Handle
Smoke Damage
We Serve
Vacation & Short-Term Rental Owners
We Handle
Falling Tree & Debris Damage
We Serve
Marinas, Boatyards & Dealers
We Handle
Denied & Underpaid Claims
We Handle
Theft & Vandalism Damage
We Serve
Landlords & Rental Properties
We Handle
Appliance Leak Damage
We Handle
Mold Damage
We Handle
Vehicle Impact Damage

Claims We Handle for You

Claim types these clients typically have, and how Homeland handles each:

All claim types › · All clients ›

Verify Homeland

Check us before you hire anyone. Every license below links to its public record on the Florida Department of Financial Services licensee search.

  • Serves all of Florida: Yes — every city and county. A licensed Homeland public adjuster comes to your property within hours — no need to visit an office. Call (305) 783-3777, 24/7.
  • Homeland Public Adjusters Corporation: Florida public adjusting firm license W818638 · New Jersey public adjuster firm license 3003982360
  • Yeni Martinez, President: Florida public adjuster license P103370 (licensed since 2007) · New Jersey 3003714097 · designated primary adjuster
  • Alberto Enriquez: Senior licensed public adjuster, Florida P112658
  • Yisel Dieguez: Licensed public adjuster and Xactimate estimator, Florida W873884 · New Jersey 3003714335
  • Nelson Avila: Florida public adjuster license G332385 · Florida Certified Contractor CRC1331322 · property insurance appraiser and umpire
  • Complaints and reputation: 5.0★ on Google · BBB Accredited Business, A+ rating
  • Since 2006: Homeland Public Adjusters, Corp. was incorporated in Florida on December 11, 2006. Our President, Yeni Martinez, has held Florida public adjuster license P103370 since 2007. When Florida began requiring adjusting firms to hold their own firm license (a 2021 law, Senate Bill 1598; DFS began licensing adjusting firms in November 2021), Homeland was issued firm license W818638 on January 11, 2022. On November 10, 2026, Homeland became a BBB Accredited Business (BBB Serving Southeast Florida & the Caribbean), with an A+ rating. Each adjuster’s appointment with Homeland appears on that adjuster’s own DFS record.
  • English and Spanish. Office: 8004 NW 154th Street, Suite 609, Miami Lakes, FL 33016 (visits by appointment). Florida (305) 783-3777 · New Jersey (732) 517-3777, 24/7.
Start My Claim