Short answer: the insurance company that owes your claim is the one named on your declarations page, which is not always the brand you bought. Frontline policies are written by First Protective, Allstate’s Florida policies by Castle Key, and many former Safepoint policies are now with Manatee Insurance Exchange. Below are the largest property insurers in Florida and New Jersey, with a guide to each one: who they are, what they insure, your deadlines and where their claims most often need help.
Last reviewed: October 2026
Find your insurer
| Brand | Insurance company on your declarations page | Our guide |
|---|---|---|
| State Farm | State Farm Florida Insurance Company (FL); State Farm Fire and Casualty Company (NJ) | Read the guide |
| Universal Property | Universal Property & Casualty Insurance Company | Read the guide |
| Slide | Slide Insurance Company | Read the guide |
| Tower Hill | Tower Hill Insurance Exchange | Read the guide |
| American Integrity | American Integrity Insurance Company | Read the guide |
| Frontline | First Protective Insurance Company | Read the guide |
| Citizens | Citizens Property Insurance Corporation | Read the guide |
| Safepoint / Manatee | Manatee Insurance Exchange; Safepoint Insurance Company | Read the guide |
| Florida Peninsula | Florida Peninsula Insurance Company | Read the guide |
| Edison | Edison Insurance Company | Read the guide |
| Allstate | Castle Key Indemnity Company (FL); Allstate companies (NJ) | Read the guide |
| Kin | Kin Interinsurance Network | Read the guide |
| Security First | Security First Insurance Company | Read the guide |
| Heritage | Heritage Property & Casualty Insurance Company | Read the guide |
| American Coastal | American Coastal Insurance Company | Read the guide |
| NJM | NJM (New Jersey Manufacturers) | Read the guide |
| Lloyd’s of London | Underwriters at Lloyd’s, London (surplus lines) | Read the guide |
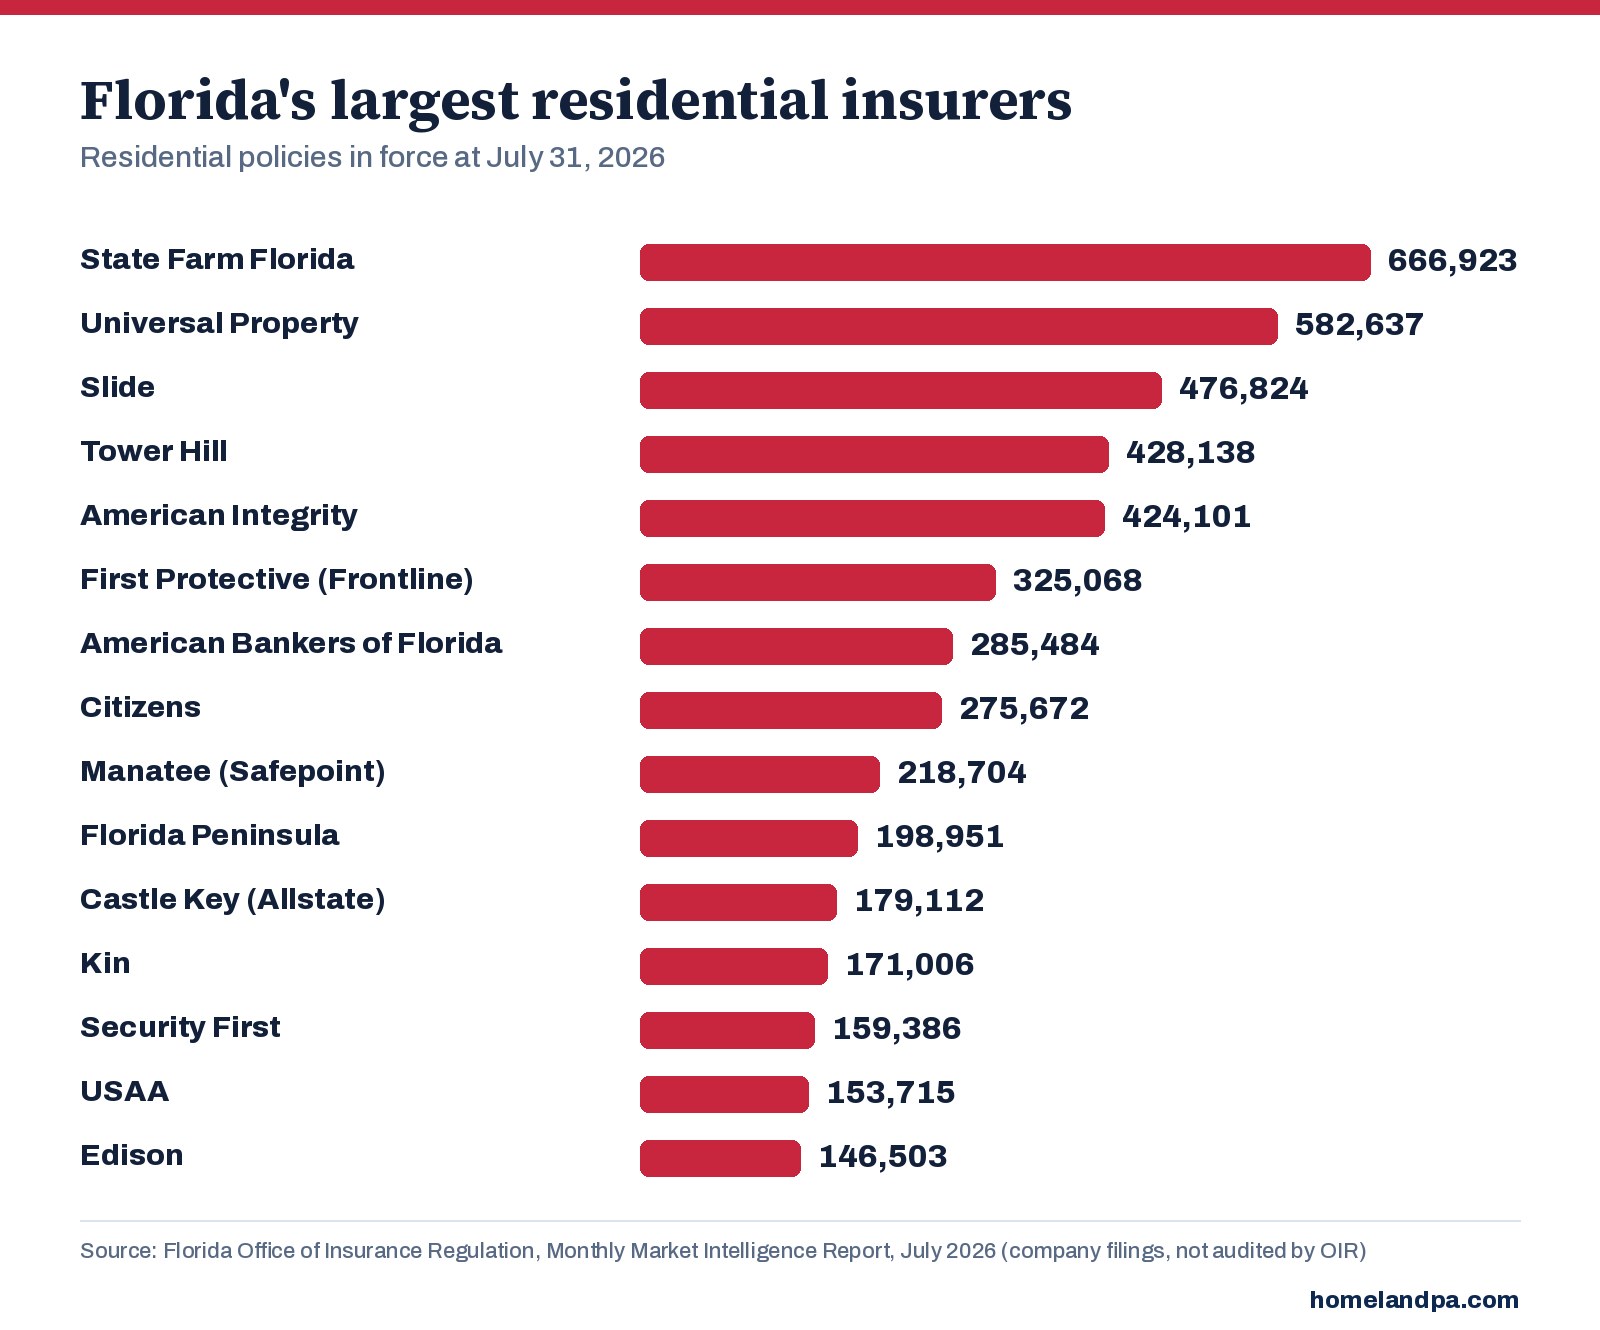
Florida’s largest residential insurers
At July 31, 2026, these were the 15 largest residential property insurers in Florida by policies in force, according to the Office of Insurance Regulation’s Monthly Market Intelligence Report. The figures cover homeowners, condo unit, rental dwelling, mobile home, renters and commercial residential policies written by companies that report to OIR.
Condo associations and commercial property
Commercial property in Florida is mostly insured outside the standard market. In 2025, commercial property was the largest surplus lines coverage in Florida: $6.2 billion in premium across 299,531 policies, according to the Florida Surplus Lines Service Office. Surplus lines policies follow different rules and are not protected by FIGA if the insurer fails; see Lloyd’s and surplus lines policies.
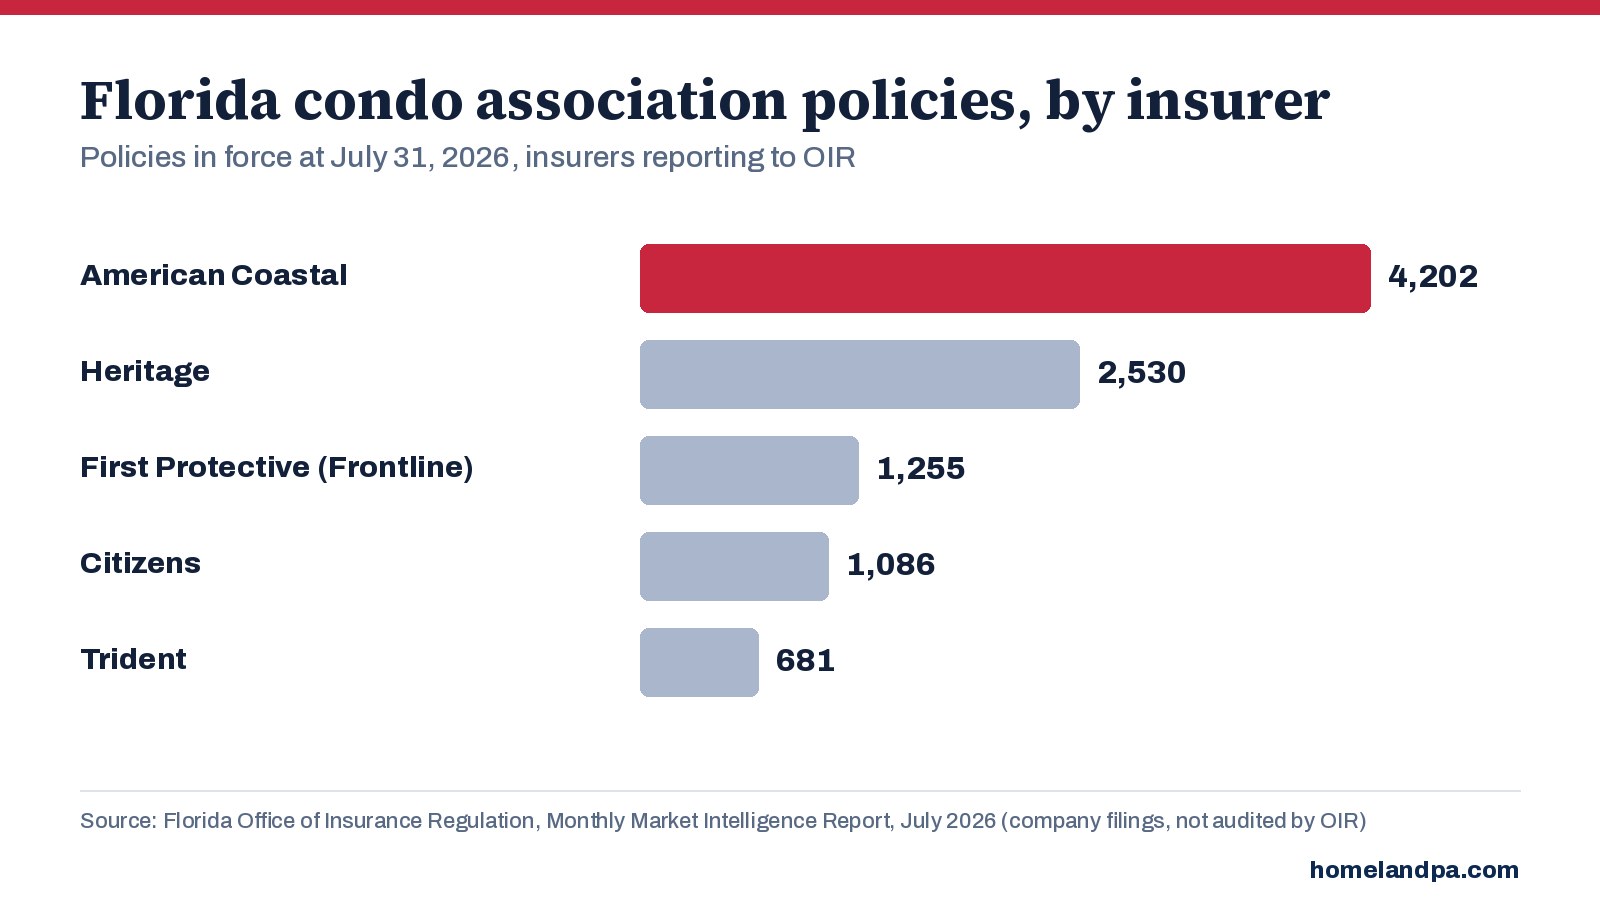
Among insurers that report to OIR, American Coastal, Heritage, First Protective and Citizens wrote the most condominium association policies at July 31, 2026.
Related: condo and HOA claims, business and commercial claims, Florida condo association insurance requirements, documenting a commercial loss.
New Jersey
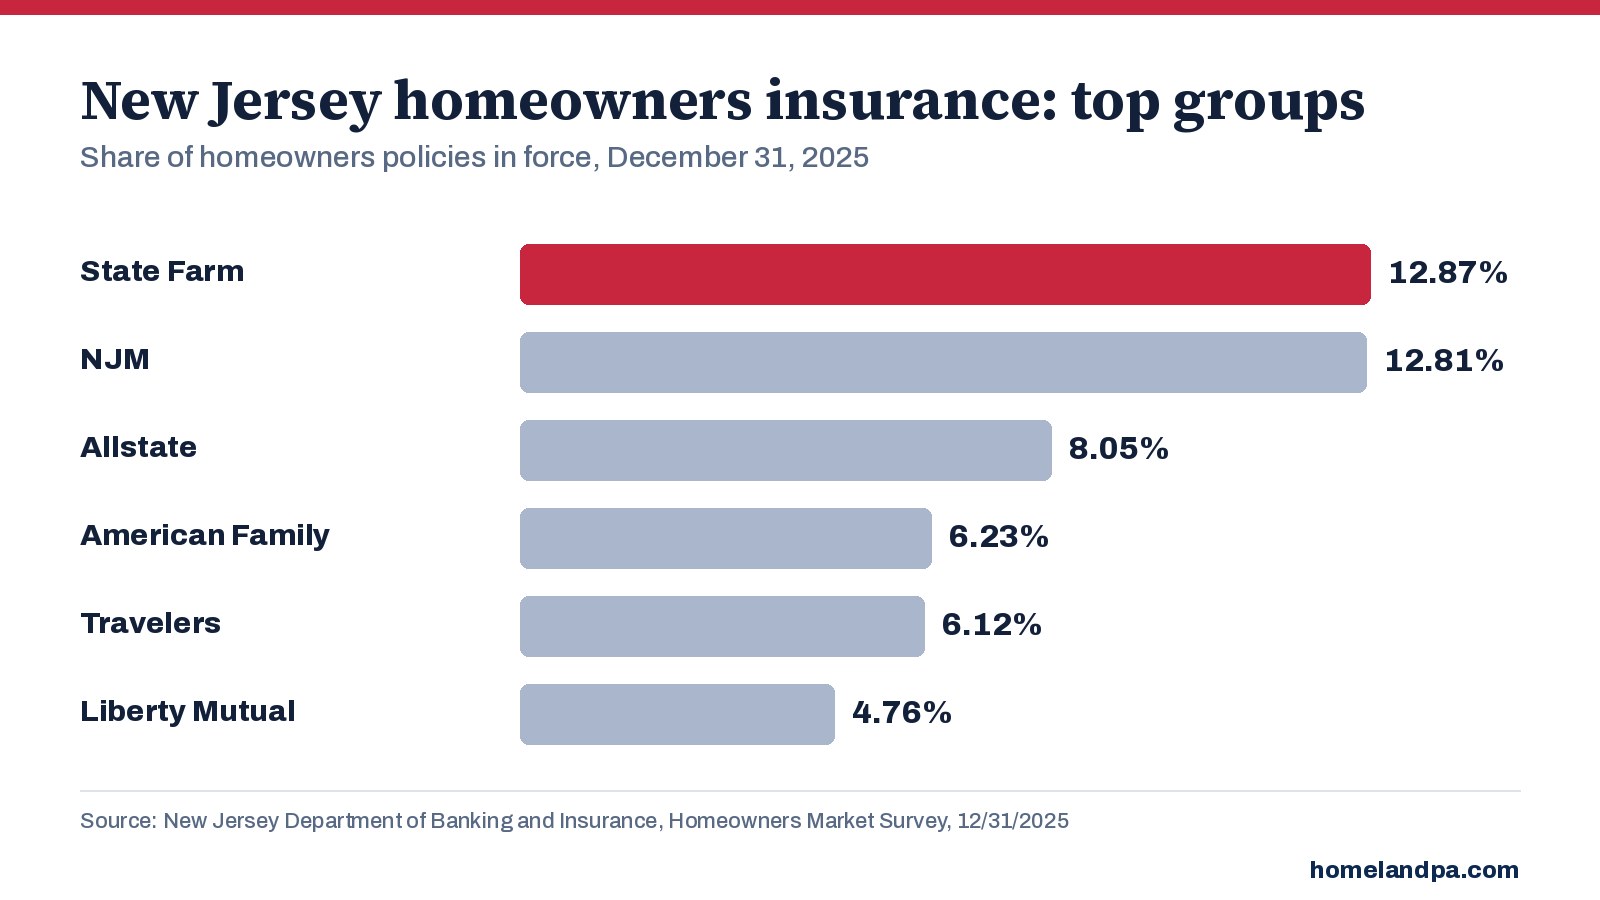
In New Jersey, State Farm, NJM and Allstate wrote the most homeowners policies at December 31, 2025, according to the Department of Banking and Insurance. New Jersey’s claim-handling rules apply to every insurer licensed there.
Your deadlines in Florida
These deadlines apply to admitted insurers. Surplus lines policies, such as those written by underwriters at Lloyd’s, may follow different rules; see the Lloyd’s guide.
If something is wrong with the policy or the insurer
How Homeland helps with your insurance company claim
We represent you, not the insurance company. We read your policy, document the loss, prepare a line-item estimate, and handle the claim with insurance company’s adjusters from start to finish, in English or Spanish. If insurance company has already paid or denied, upload the letter or estimate to Claim Review for a free first read.
Frequently asked questions
How do I find out which insurance company I have?
Who is the largest property insurer in Florida?
Is Homeland affiliated with any of these insurers?
Sources: Florida Surplus Lines Service Office, 2025 Annual Report; WUSF, June 19, 2026; N.J.A.C. 11:2-17.7; NJ DOBI Homeowners Market Survey, 12/31/2025; Florida Office of Insurance Regulation, Monthly Market Intelligence Report, July 2026; Fla. Stat. §627.70131; Fla. Stat. §627.70132.
Homeland Public Adjusters is not affiliated with, endorsed by or sponsored by any insurance company named on this page. Company names are used only to identify the insurer. This page is general information, not legal advice.
Talk to a Public Adjuster
Tell us about your loss. We’ll call you back.

Insurance Company Claims We Handle
We represent property owners on claims with any insurance company in Florida and New Jersey: homes, condo units, rentals, mobile homes, condominium associations and businesses, in English or Spanish. We work for you, never the insurer.