Your Homeowners Insurance Declarations Page, Explained Line by Line

Licensed public adjusters serving Florida & New Jersey
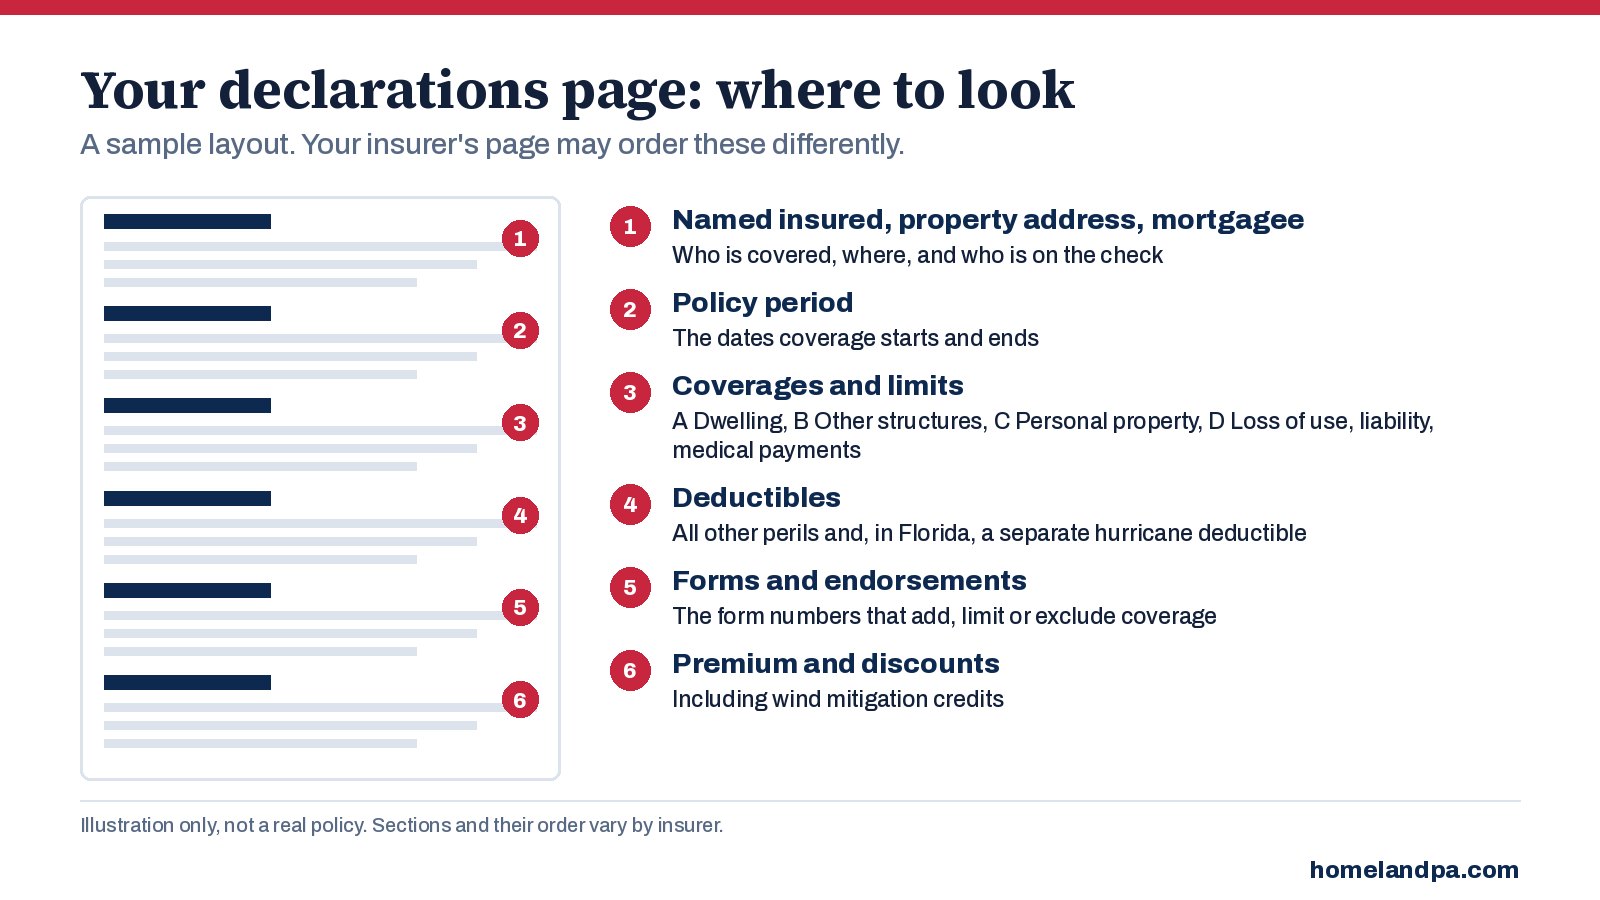
Short answer: the declarations page (often called the “dec page”) is the summary at the front of your policy. It lists who and what is insured, the policy period, each coverage and its limit, your deductibles, your premium and discounts, and the forms and endorsements that make up your policy. It is the first page we read on every claim.
1. Named insured, property address and mortgagee
Check that every owner is named and the address is right. The mortgagee is your lender; it is usually named on claim checks for damage to the home. See Insurance Check Made Out to the Mortgage Company.
2. Policy period
The dates your coverage starts and ends. The loss must happen inside this period for this policy to apply.
3. Coverages and limits
- Coverage A, Dwelling: the house itself and attached structures.
- Coverage B, Other structures: detached structures like fences, sheds and detached garages.
- Coverage C, Personal property: your belongings. See contents coverage.
- Coverage D, Loss of use: extra living costs if you cannot live in the home. See additional living expense.
- Liability and medical payments to others (often labeled E and F): injuries and damage you cause to others.
- Look for whether the home and belongings are covered at replacement cost or actual cash value (what the difference means), and for any ordinance or law coverage.
4. Deductibles
Most policies list an all other perils deductible and, in Florida, a separate hurricane deductible, often a percentage of Coverage A. Some list a separate sinkhole deductible too. A 2% hurricane deductible on a $400,000 dwelling limit is $8,000. See What Is a Hurricane Deductible?.
5. Forms and endorsements
This list of form numbers is where coverage is added, limited or taken away, and it is where surprises hide: a roof payment schedule, a limited water damage endorsement, or even an anti-public adjuster endorsement. Ask for a full copy of every form listed, not just the dec page.
6. Premium and discounts
The total premium and any discounts, such as wind mitigation credits (see Wind Mitigation, 4-Point and Roof Inspections). Missing credits can mean you are paying more than you need to.
Get a free review
Upload your declarations page to Policy Scan for a free plain-language review by our team, or save it in the free Adjuster Advantage app so you have it when you need it. If you already have a claim, get a free claim review.
Frequently asked questions
What is a declarations page?
How do I get a copy of my declarations page?
What are Coverage A, B, C and D?
Is the declarations page the whole policy?
Sources: Maryland Insurance Administration, Understanding Your Homeowners Insurance Declarations Page; Florida Department of Financial Services, Florida’s hurricane deductible.
This guide is general information, not legal advice. Declarations pages and policy forms differ by insurer and state; your own policy controls.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim Review