Insurance Check Made Out to You and Your Mortgage Company

Homeland Public Adjusters · Last reviewed: October 2026
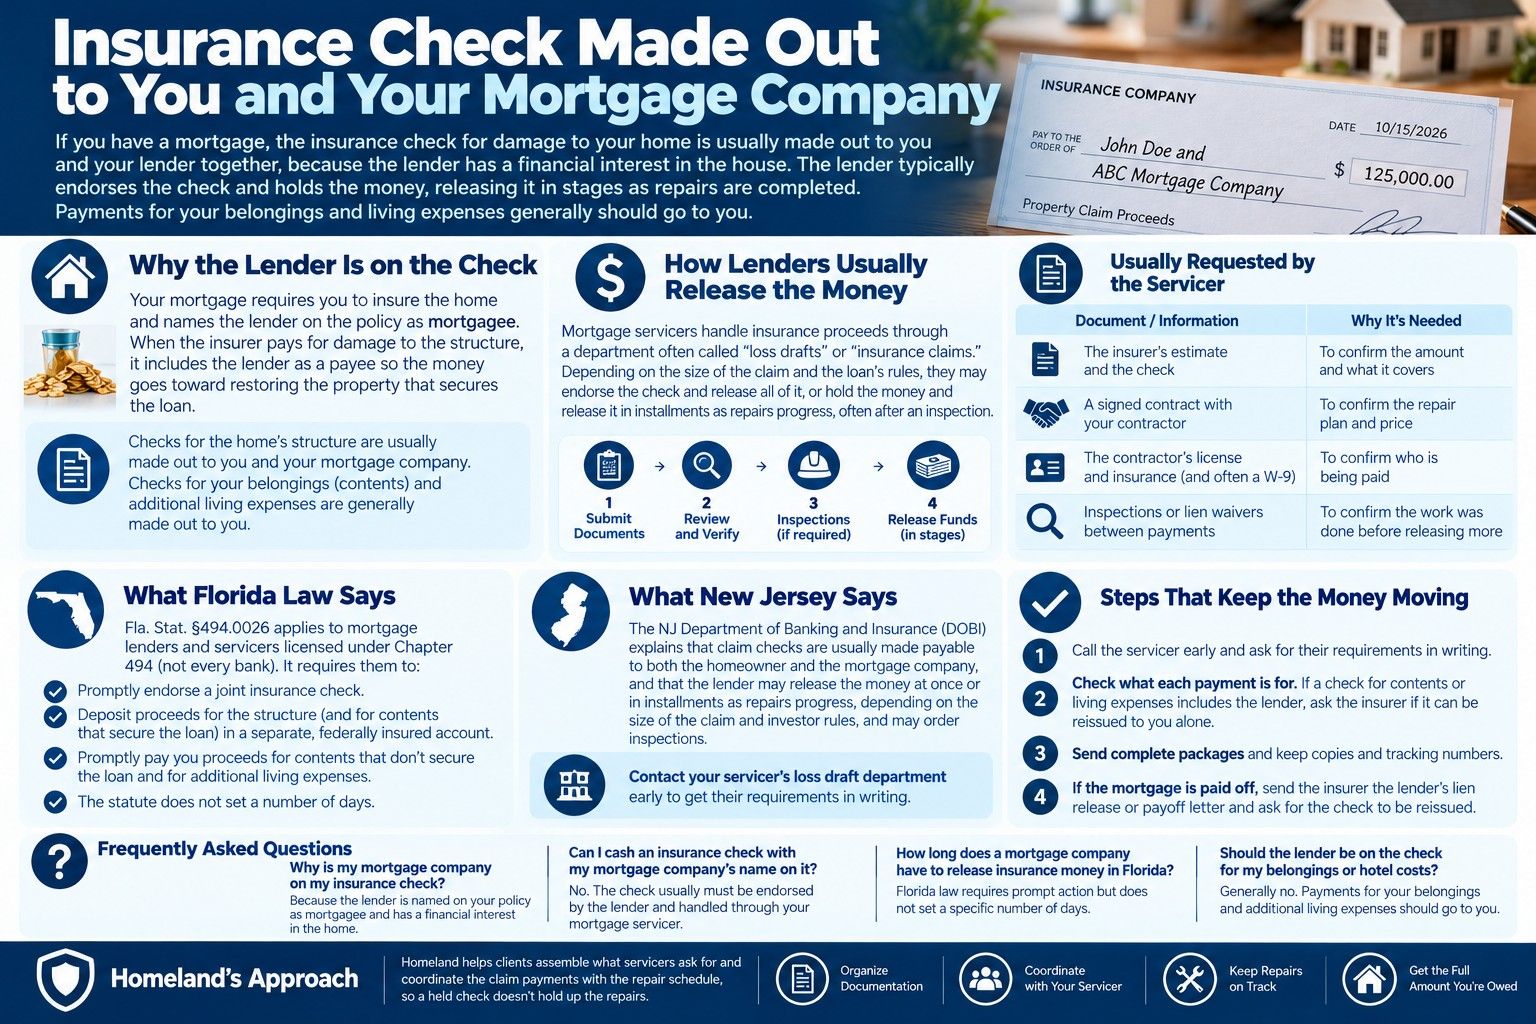
Short answer: If you have a mortgage, the insurance check for damage to your home is usually made out to you and your lender together, because the lender has a financial interest in the house. The lender typically endorses the check and holds the money, releasing it in stages as repairs are completed. Payments for your belongings and living expenses generally should go to you.
Why the lender is on the check
Your mortgage requires you to insure the home and names the lender on the policy as mortgagee. When the insurer pays for damage to the structure, it includes the lender as a payee so the money goes toward restoring the property that secures the loan.
How lenders usually release the money
Mortgage servicers handle insurance proceeds through a department often called "loss drafts" or "insurance claims." Depending on the size of the claim and the loan's rules, the servicer may endorse the check and release all of it, or deposit it and release it in installments as repairs progress, often after an inspection.
| Usually requested by the servicer | Why |
|---|---|
| The insurer's estimate and the check | To confirm the amount and what it covers |
| A signed contract with your contractor | To confirm the repair plan and price |
| The contractor's license and insurance (and often a W-9) | To confirm who is being paid |
| Inspections or lien waivers between payments | To confirm the work was done before releasing more |
What Florida law says
Florida's Fla. Stat. §494.0026 applies to mortgage lenders and servicers licensed under Chapter 494 (not every bank). It requires them to promptly endorse a joint insurance check, to deposit proceeds for the structure and for contents that secure the loan in a separate account at a federally insured institution, and to promptly pay you proceeds for contents that don't secure the loan and for additional living expenses. The statute does not set a number of days.
What New Jersey says
The NJ Department of Banking and Insurance (DOBI) explains that claim checks are usually made payable to both the homeowner and the mortgage company, and that the lender may release the money at once or in installments as repairs progress, depending on the size of the claim and investor rules, and may order inspections. DOBI's advice is to contact your servicer right away.
Steps that keep the money moving
Call the servicer's loss draft department early and ask for its requirements in writing.
Check what each payment is for. If a check for contents or living expenses includes the lender, ask the insurer whether it can be reissued to you alone.
Send complete packages and keep copies and tracking numbers.
If the mortgage is paid off, send the insurer the lender's lien release or payoff letter and ask for the check to be reissued.
Homeland helps policyholders in Kendall, Orlando and Jersey City get the mortgage endorsement process moving.
Frequently asked questions
Why is my mortgage company on my insurance check?
Can I cash an insurance check with my mortgage company's name on it?
How long does a mortgage company have to release insurance money in Florida?
Should the lender be on the check for my belongings or hotel costs?
Homeland helps clients assemble what servicers ask for and coordinate the claim payments with the repair schedule, so a held check doesn't hold up the repairs.
This article is for general information only and is not legal or insurance advice. Statutes, regulations and policy wording change, and how they apply depends on your own policy and the facts of your claim. Homeland Public Adjusters is a public adjusting firm, not a law firm.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Public Adjuster Near Me page to get connected with the Homeland adjuster covering your area.