What Is Recoverable Depreciation on an Insurance Claim?

Homeland Public Adjusters · Last reviewed: October 2026
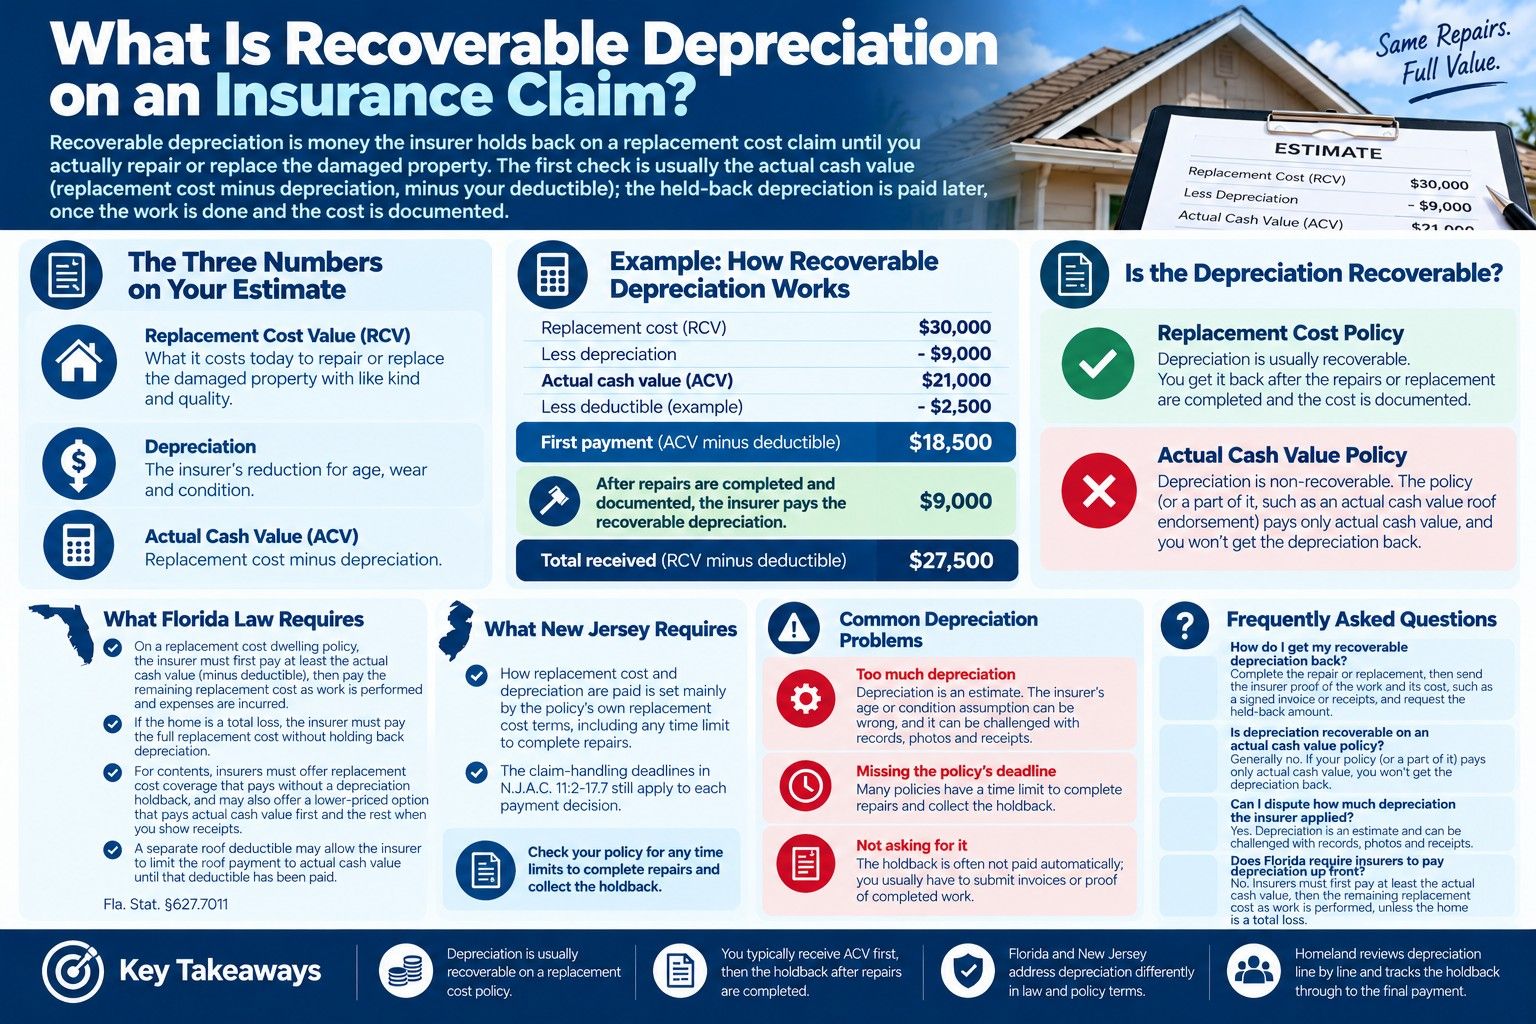
Short answer: Recoverable depreciation is money the insurer holds back on a replacement cost claim until you actually repair or replace the damaged property. The first check is usually the actual cash value (replacement cost minus depreciation, minus your deductible); the held-back depreciation is paid later, once the work is done and the cost is shown.
The three numbers on your estimate
| Term | What it means |
|---|---|
| Replacement cost value (RCV) | What it costs today to repair or replace the damaged property with like kind and quality |
| Depreciation | The insurer's reduction for age, wear and condition |
| Actual cash value (ACV) | Replacement cost minus depreciation |
If your policy pays replacement cost, the depreciation is usually recoverable: you get it back after the repairs. If your policy (or a part of it, such as an actual cash value roof endorsement) pays only actual cash value, the depreciation is non-recoverable, and you won't get it back.
An example
What Florida law requires
Under Fla. Stat. §627.7011, on a replacement cost dwelling policy the insurer must first pay at least the actual cash value, minus the deductible, and then pay the remaining replacement cost as work is performed and expenses are incurred. If the home is a total loss, the insurer must pay the full replacement cost without holding back depreciation.
For belongings (contents), Florida insurers must offer replacement cost coverage that pays without a depreciation holdback, and may also offer a lower-priced option that pays actual cash value first and the rest when you show receipts. Which one you have is on your declarations page. Where a separate roof deductible applies, the insurer may limit the roof payment to actual cash value until that deductible has been paid.
The statute doesn't set a deadline to finish repairs and collect the holdback, but many policies do. Check your policy's replacement cost conditions for any time limit.
New Jersey
In New Jersey, how replacement cost and depreciation are paid is set mainly by the policy's own replacement cost terms, including any time limit to complete repairs. The claim-handling deadlines in N.J.A.C. 11:2-17.7 still apply to each payment decision.
Common depreciation problems
Too much depreciation. Depreciation is an estimate. An insurer's age or condition assumption can be wrong, and it can be challenged with records, photos and receipts.
Missing the policy's deadline to repair and claim the holdback.
Not asking for it. The holdback is often not paid automatically; you usually have to submit invoices or proof of completed work.
An insurer that questions your property’s age and condition may use the same findings two ways: to argue an exclusion such as wear and tear (often in a reservation of rights letter), and to apply more depreciation. That’s why documenting the property’s condition before and after a loss matters.
Homeland tracks and recovers holdback on claims in Miami Lakes, Fort Lauderdale and Toms River.
Frequently asked questions
How do I get my recoverable depreciation back?
Is depreciation recoverable on an actual cash value policy?
Can I dispute how much depreciation the insurer applied?
Does Florida require insurers to pay depreciation up front?
Homeland reviews depreciation line by line and tracks the holdback through to the final payment, so money you're owed doesn't get left on the table.
This article is for general information only and is not legal or insurance advice. Statutes, regulations and policy wording change, and how they apply depends on your own policy and the facts of your claim. Homeland Public Adjusters is a public adjusting firm, not a law firm.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Public Adjuster Near Me page to get connected with the Homeland adjuster covering your area.