
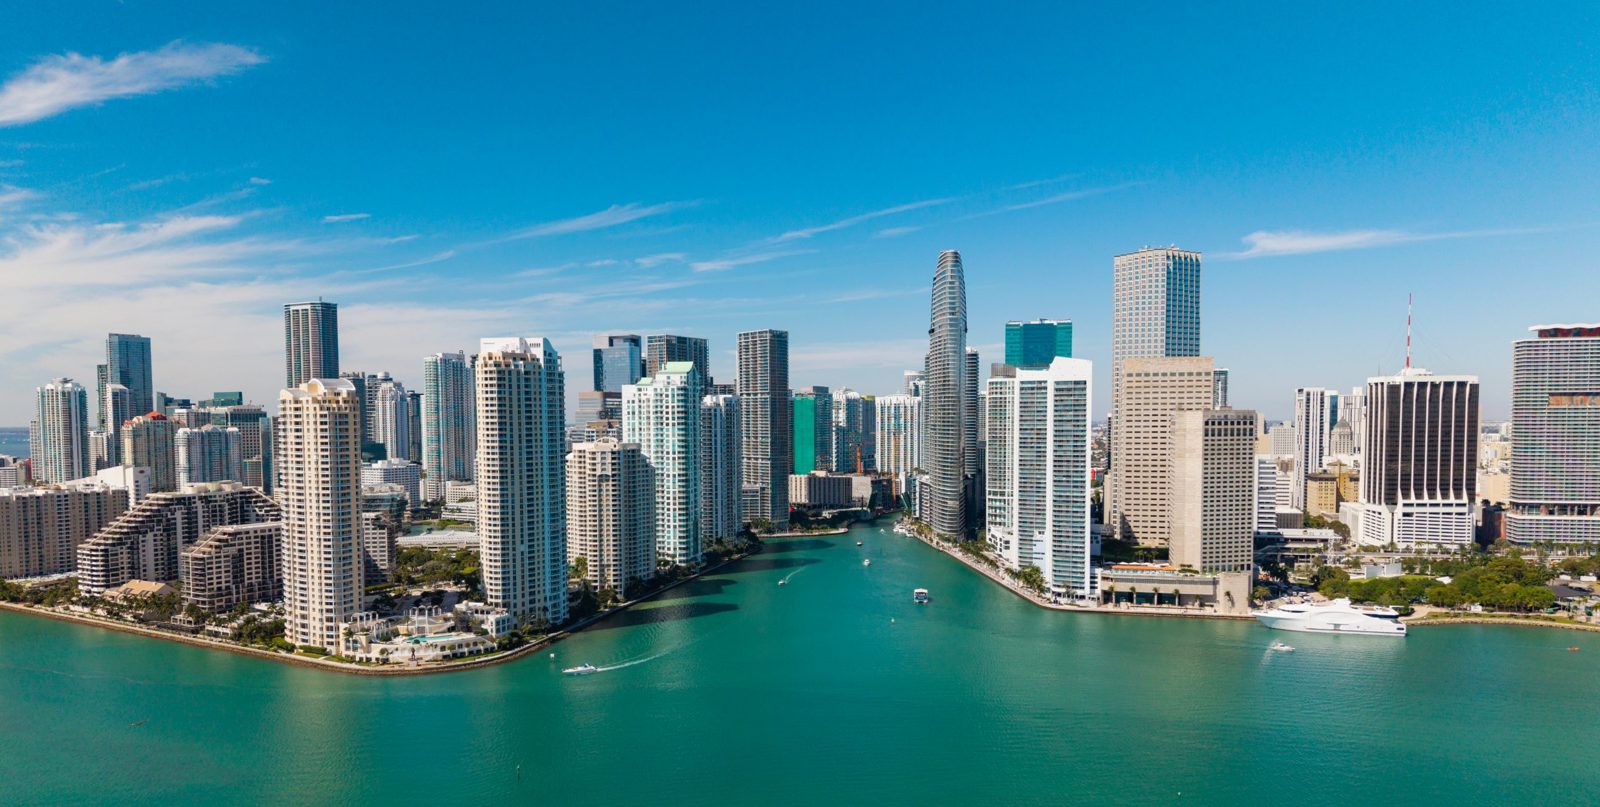
Wherever you are in South Florida, we come to you. A licensed Homeland public adjuster comes to your property within hours — Miami-Dade, Broward, Palm Beach and the Keys, every city in every county — no need to visit an office. Serving Florida property owners since 2006, in English and Spanish.
Homeland Public Adjusters is a South Florida firm. Our home office is in Miami Lakes, our adjusters live and work in Miami-Dade, Broward and Palm Beach, and the tri-county area is where we have represented homeowners, condominium associations, unit owners, landlords and businesses since 2006. South Florida has the highest homeowners premiums in the country, the largest concentration of condominium associations, the most expensive hurricane deductibles, and the state’s highest claim litigation rate. We document the loss, prepare the claim and negotiate it with the insurer. No Recovery, No Fee. Call 24/7, hablamos español.
Last reviewed: October 2026
How Can We Help You Recover, or Prepare?
Why South Florida Claims Are Different
Three numbers explain the tri-county market. Litigation: 27.27% of property claims closed in Palm Beach, Broward and Miami-Dade in 2025 involved a lawsuit, against 8.16% in the rest of the state outside Central Florida. Premiums: Palm Beach and Broward homeowners pay the second- and third-highest average premiums in Florida, behind only Monroe County. Condominiums: nearly 13,000 condo associations and 610,000 units sit in the three counties, every one of them on a master policy with a percentage hurricane deductible and a line between the association’s coverage and the unit owner’s under §718.111(11). Add pre-1994 housing with cast-iron drain lines, the $10,000 limited water damage endorsement on most Citizens and many private policies, and carriers that reinspect every claim, and you have a region where the first offer is rarely the right number.
Miami-Dade County
Miami-Dade is Homeland’s home county. The claims here are the oldest housing stock in the state (Coral Gables, Miami Springs, Miami Shores, the Roads) with cast-iron plumbing, tile roofs and 1950s electrical; the condominium towers of Brickell, Aventura, Sunny Isles and Key Biscayne, where a single hurricane deductible can exceed $1 million and the association’s master policy and the unit owner’s HO-6 have to be claimed together; and a commercial base of restaurants, warehouses in Doral and Medley, medical offices and hotels. Miami-Dade also has the state’s largest Spanish-speaking policyholder base, and every Homeland adjuster is bilingual. Local pages on the (305) line: Miami, Miami Lakes, Hialeah, Miami Gardens, Kendall, Doral, Coral Gables, Aventura, Miami Beach, Key Biscayne, Homestead, Palmetto Bay, North Miami Beach, Miami Springs.
Choosing an adjuster here? See the 10-point test for the best public adjuster in Miami-Dade County.
Broward County
Broward’s claims run from the barrier-island condominiums of Fort Lauderdale, Hollywood and Pompano Beach to the 1990s–2000s single-family communities of Weston, Pembroke Pines, Miramar, Plantation and Coral Springs, where the roof-age endorsements and roof payment schedules carriers added after 2022 decide most hurricane claims. Broward’s April 2023 rain event (Fort Lauderdale’s 25-inch day) produced flood denials on homeowners policies for water that entered through roofs and openings, a wind-driven-rain versus flood dispute we still see on supplemental claims. Local pages on the (954) line: Broward County, Fort Lauderdale, Hollywood, Pembroke Pines, Miramar, Weston, Coral Springs, Pompano Beach, Plantation.
Choosing an adjuster here? See the 10-point test for the best public adjuster in Broward County.
Palm Beach County
Palm Beach County pays the second-highest premiums in Florida and has the widest range of property in the region: oceanfront estates and condominiums from Boca Raton to Jupiter, the equestrian and agricultural west (Wellington, Loxahatchee, Belle Glade and the Glades sugar and vegetable operations), and the 55-plus communities whose associations carry master policies on hundreds of villas at a time. Palm Beach filed 4,865 Hurricane Ian claims and 4,559 Milton claims even though neither storm made landfall nearby, which is what a hurricane watch does to a hurricane deductible. Local pages on the (561) line: Palm Beach County, West Palm Beach, Boca Raton, Delray Beach, Jupiter, Belle Glade.
Choosing an adjuster here? See the 10-point test for the best public adjuster in Palm Beach County.
Monroe County and the Florida Keys
The Keys carry the highest homeowners premiums in Florida, wind coverage that Citizens writes for much of the island chain, and flood through the NFIP on nearly every structure. A Keys claim is almost always two claims (wind and flood) with two adjusters and two proofs of loss, and the NFIP’s 60-day proof-of-loss deadline runs from the date of loss. See our Florida Keys page and flood damage claims.
Choosing an adjuster here? See the 10-point test for the best public adjuster in Monroe County and the Florida Keys.
Condominium Associations: South Florida’s Largest Claims
With nearly 13,000 associations in the tri-county area, the master-policy claim is South Florida’s signature loss. Under §718.111(11) the association insures the building except the unit interiors (floor, wall and ceiling coverings, fixtures, appliances, cabinets, window treatments), which the unit owner insures under an HO-6; after a hurricane the two policies must be claimed in parallel. Percentage deductibles on a tower are allocated to owners by the declaration and bylaws, and a shortfall becomes a special assessment. Homeland represents the association and, separately, the unit owners; see condo and HOA associations, our free board and manager session, and the 718 insurance requirements explained.
What a South Florida Public Adjuster Does for You
Homeland works on a No Recovery, No Fee basis, and Florida law caps public adjuster fees. See public adjuster fees.
South Florida Public Adjuster FAQs
Where is Homeland’s office?
Why is the litigation rate so high in the tri-county area?
Does my condo association’s policy cover the inside of my unit?
My policy has a $10,000 water damage limit. Is that all I can get?
Hablan español?
South Florida Public Adjusters, City by City
Each South Florida city and county page carries a local line (305, 954 or 561) that rings our adjusters directly. Not listed? We serve all of Miami-Dade, Broward, Palm Beach and Monroe; call the Miami line.
Talk to a Public Adjuster
How Can We Help You Recover, or Prepare?
Tell us about your loss. We’ll call you back.

Claims We Handle Across South Florida
From a cast-iron pipe failure in Coral Gables to a master-policy hurricane claim on Brickell, these are the claims South Florida property owners bring us.
Verify Homeland
Check us before you hire anyone. Every license below links to its public record on the Florida Department of Financial Services licensee search.
- Serves all of Florida: Yes — every city and county. A licensed Homeland public adjuster comes to your property within hours — no need to visit an office. Call (305) 783-3777, 24/7.
- Homeland Public Adjusters Corporation: Florida public adjusting firm license W818638 · New Jersey public adjuster firm license 3003982360
- Yeni Martinez, President: Florida public adjuster license P103370 (licensed since 2007) · New Jersey 3003714097 · designated primary adjuster
- Alberto Enriquez: Senior licensed public adjuster, Florida P112658
- Yisel Dieguez: Licensed public adjuster and Xactimate estimator, Florida W873884 · New Jersey 3003714335
- Nelson Avila: Florida public adjuster license G332385 · Florida Certified Contractor CRC1331322 · property insurance appraiser and umpire
- Complaints and reputation: 5.0★ on Google · BBB Accredited Business, A+ rating
- Since 2006: Homeland Public Adjusters, Corp. was incorporated in Florida on December 11, 2006. Our President, Yeni Martinez, has held Florida public adjuster license P103370 since 2007. When Florida began requiring adjusting firms to hold their own firm license (a 2021 law, Senate Bill 1598; DFS began licensing adjusting firms in November 2021), Homeland was issued firm license W818638 on January 11, 2022. On November 10, 2026, Homeland became a BBB Accredited Business (BBB Serving Southeast Florida & the Caribbean), with an A+ rating. Each adjuster’s appointment with Homeland appears on that adjuster’s own DFS record.
- English and Spanish. Office: 8004 NW 154th Street, Suite 609, Miami Lakes, FL 33016 (visits by appointment). Florida (305) 783-3777 · New Jersey (732) 517-3777, 24/7.