Call Now · 24/7 · Hablamos Español
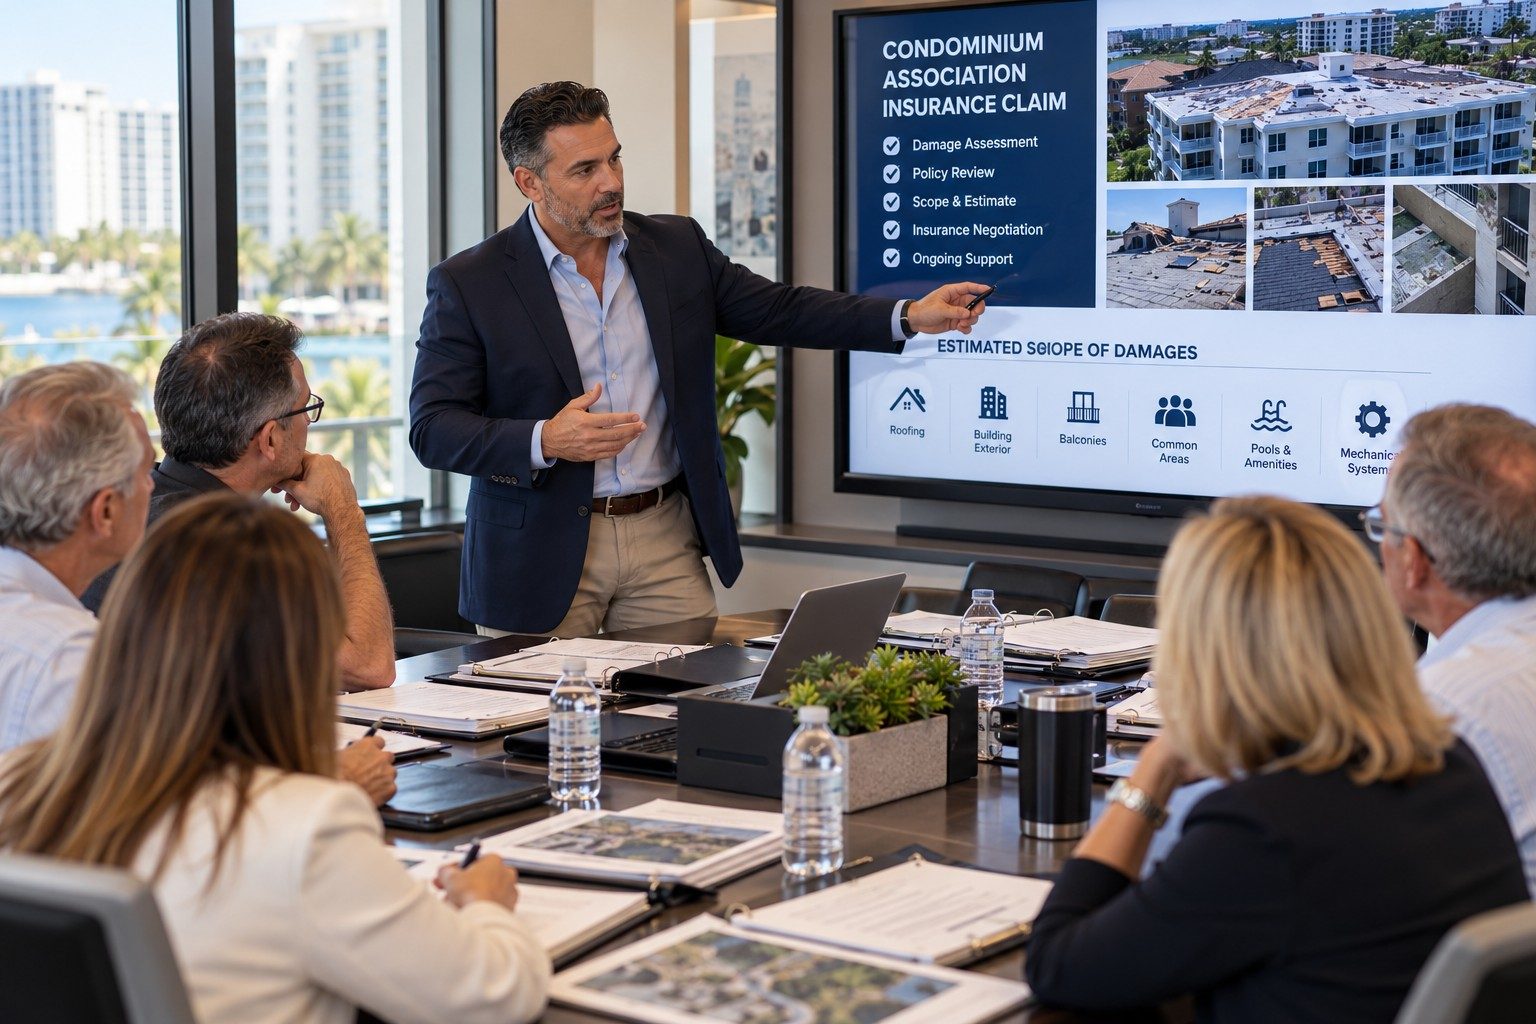
Public adjuster presenting a condominium association insurance claim to a board in a conference room
FREE BOARD EDUCATION SESSION

Insurance Claims for Condo & HOA Boards and Managers

A 30-minute session for boards and managers: what the master policy pays for, what the board has to prove, and how to keep a shortfall from becoming a special assessment.

Short answer: the master policy pays for what the association proves. Most boards find that out after the loss, when the insurer’s number is the only number on the table and the gap becomes a special assessment. Homeland presents a free, vendor-neutral session to condo and HOA boards, community association managers and management companies in Florida and New Jersey, in person or by video, in English or Spanish.

What the Session Covers

1
Who covers what after a loss
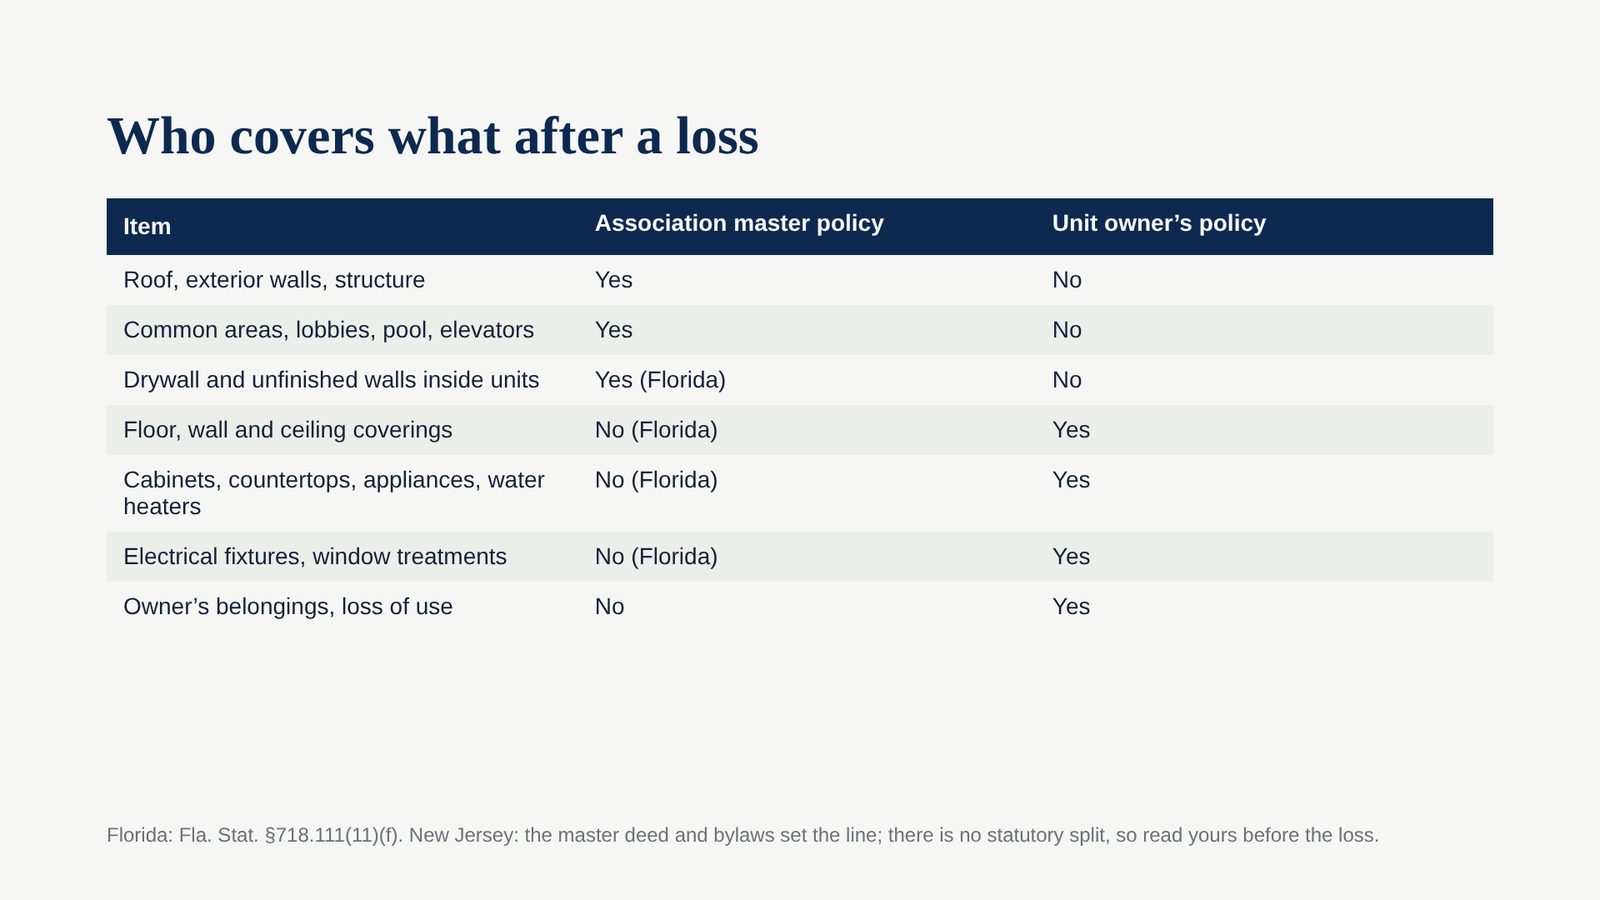
The master policy versus the unit owner’s policy under Fla. Stat. §718.111(11)(f), and the master deed in New Jersey. Why almost every water or fire loss is two claims on two policies.
2
The deductible in dollars, and who absorbs it
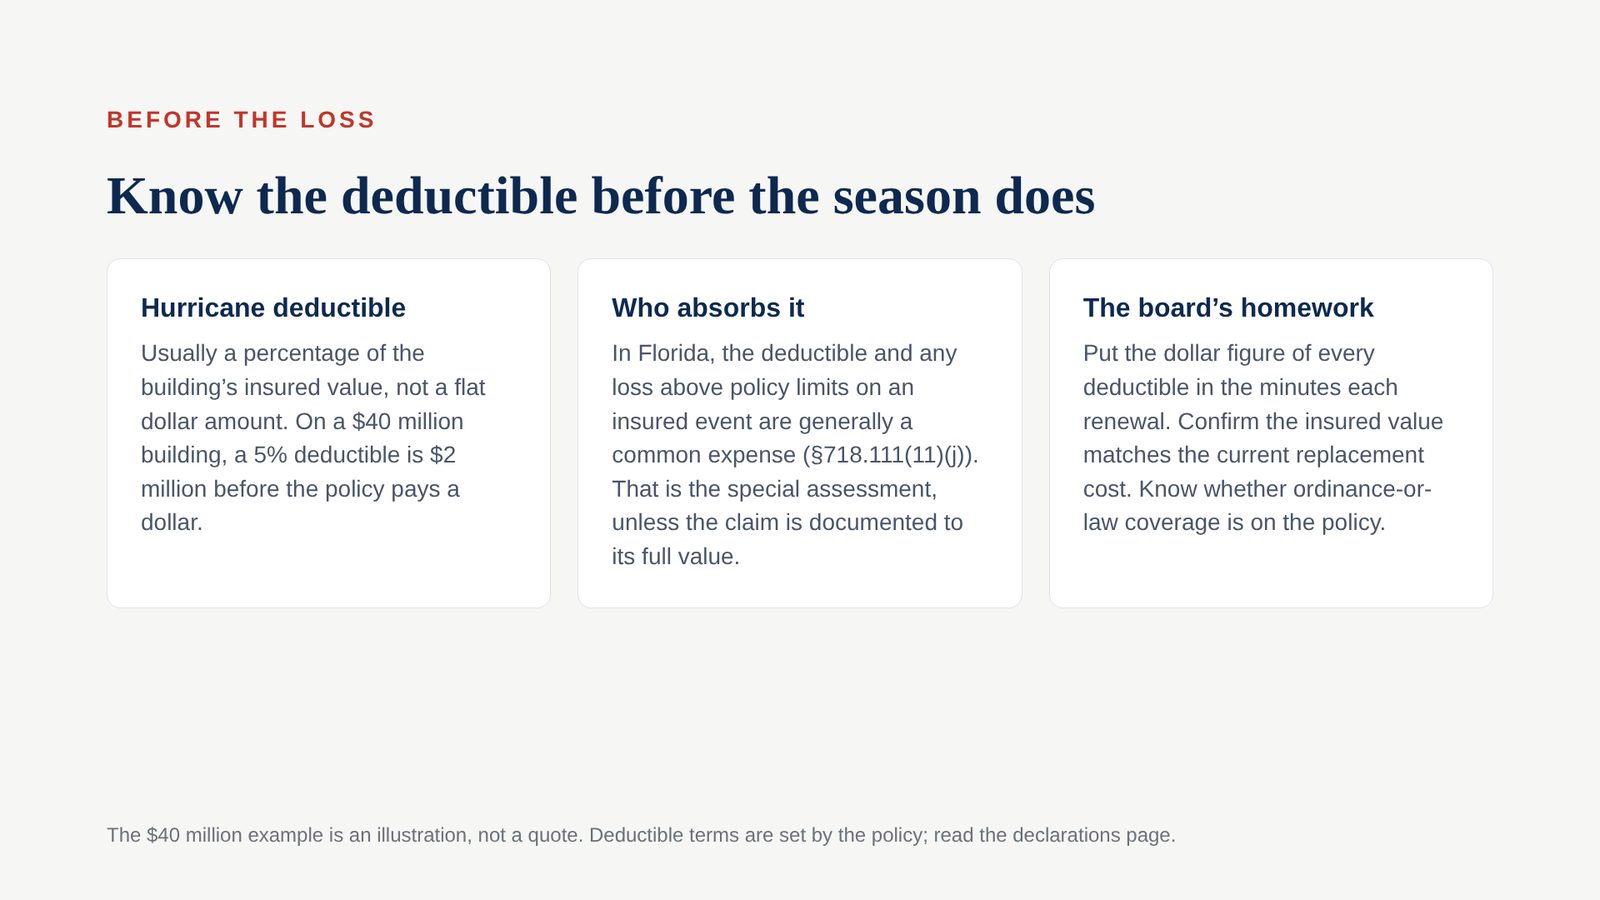
Percentage hurricane deductibles, ordinance-or-law coverage, and why the deductible and any uninsured portion are generally a common expense (§718.111(11)(j)).
3
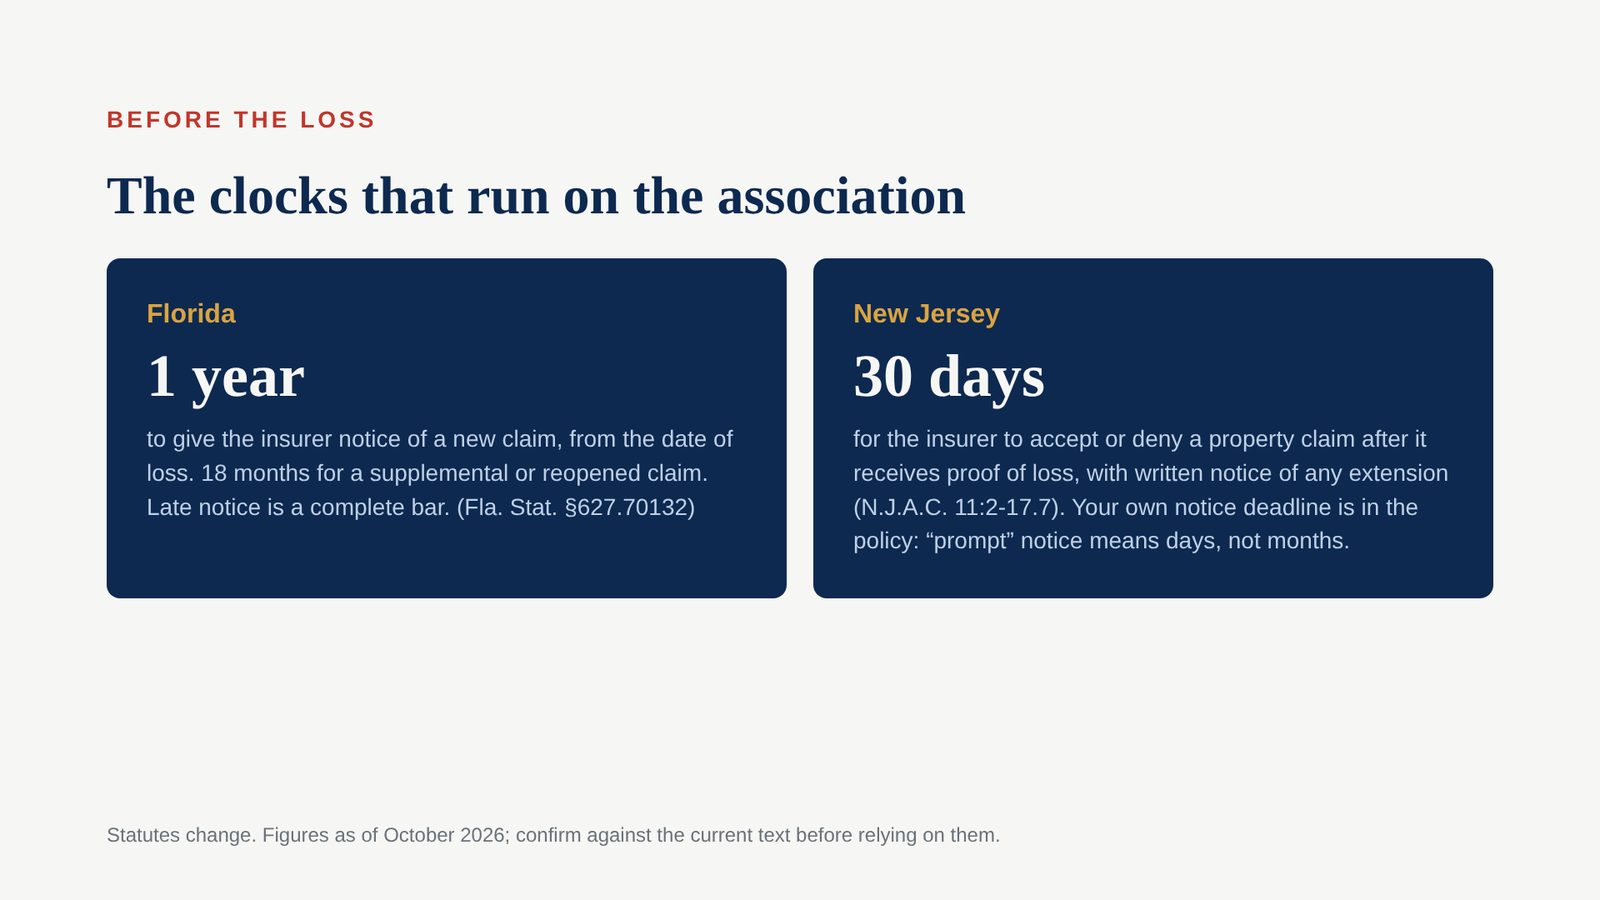
The clocks that run on the association
Florida’s one-year notice and 18-month supplemental deadlines (§627.70132); New Jersey’s insurer response rules (N.J.A.C. 11:2-17.7) and the policy’s own notice clause.
4
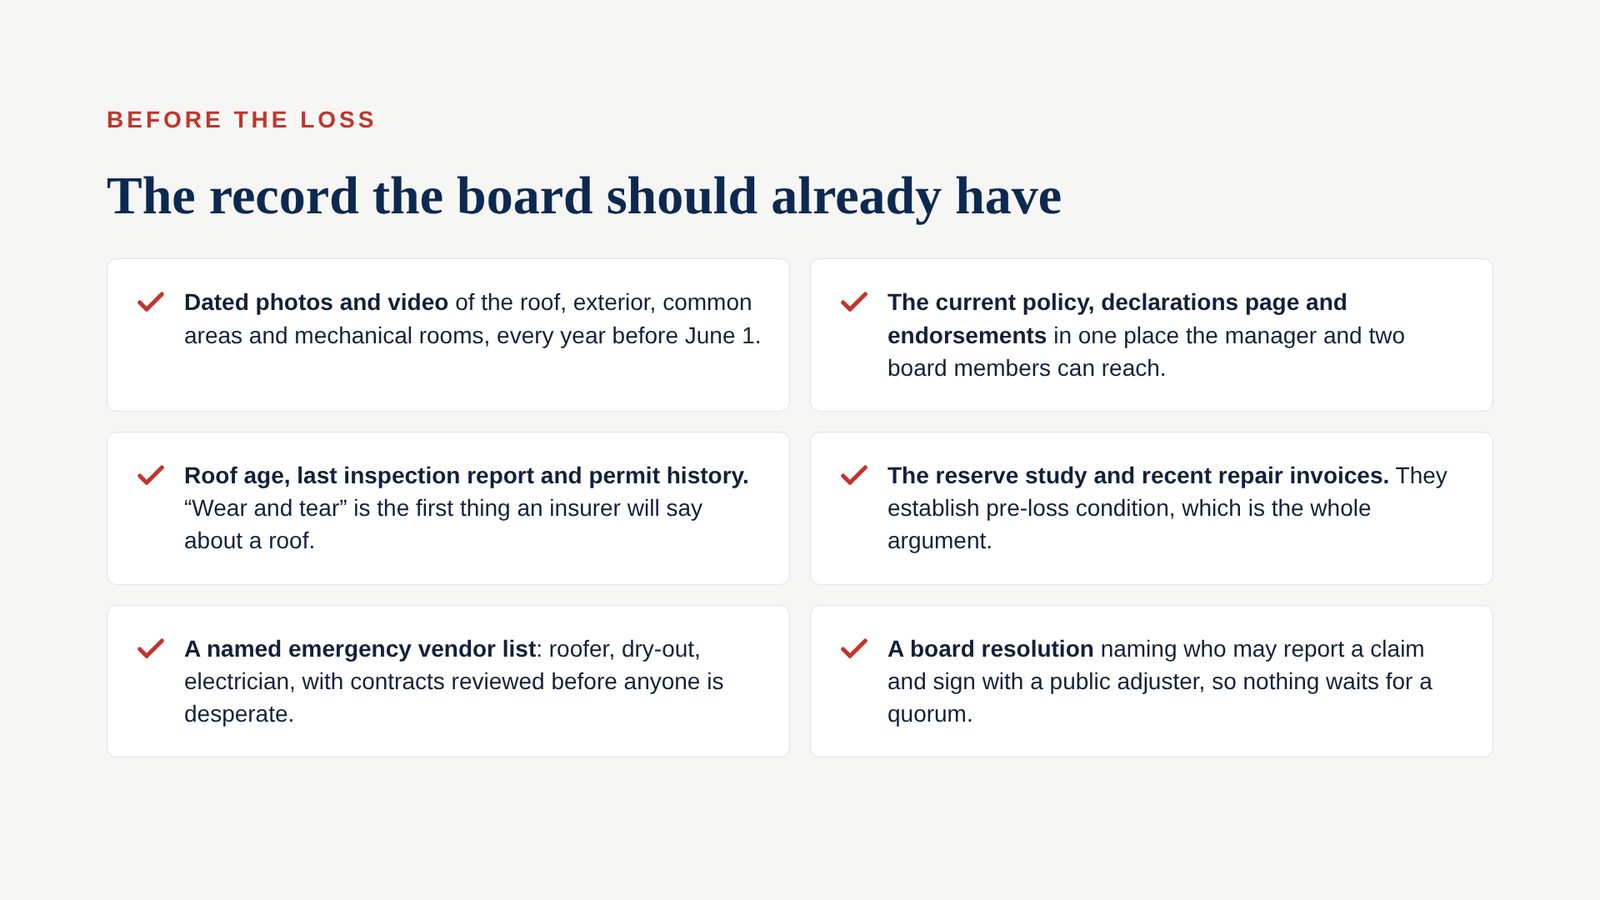
The record the board should already have
Dated photos before June 1, roof reports and permit history, the reserve study, the policy in one place, and a resolution naming who may report a claim.
5
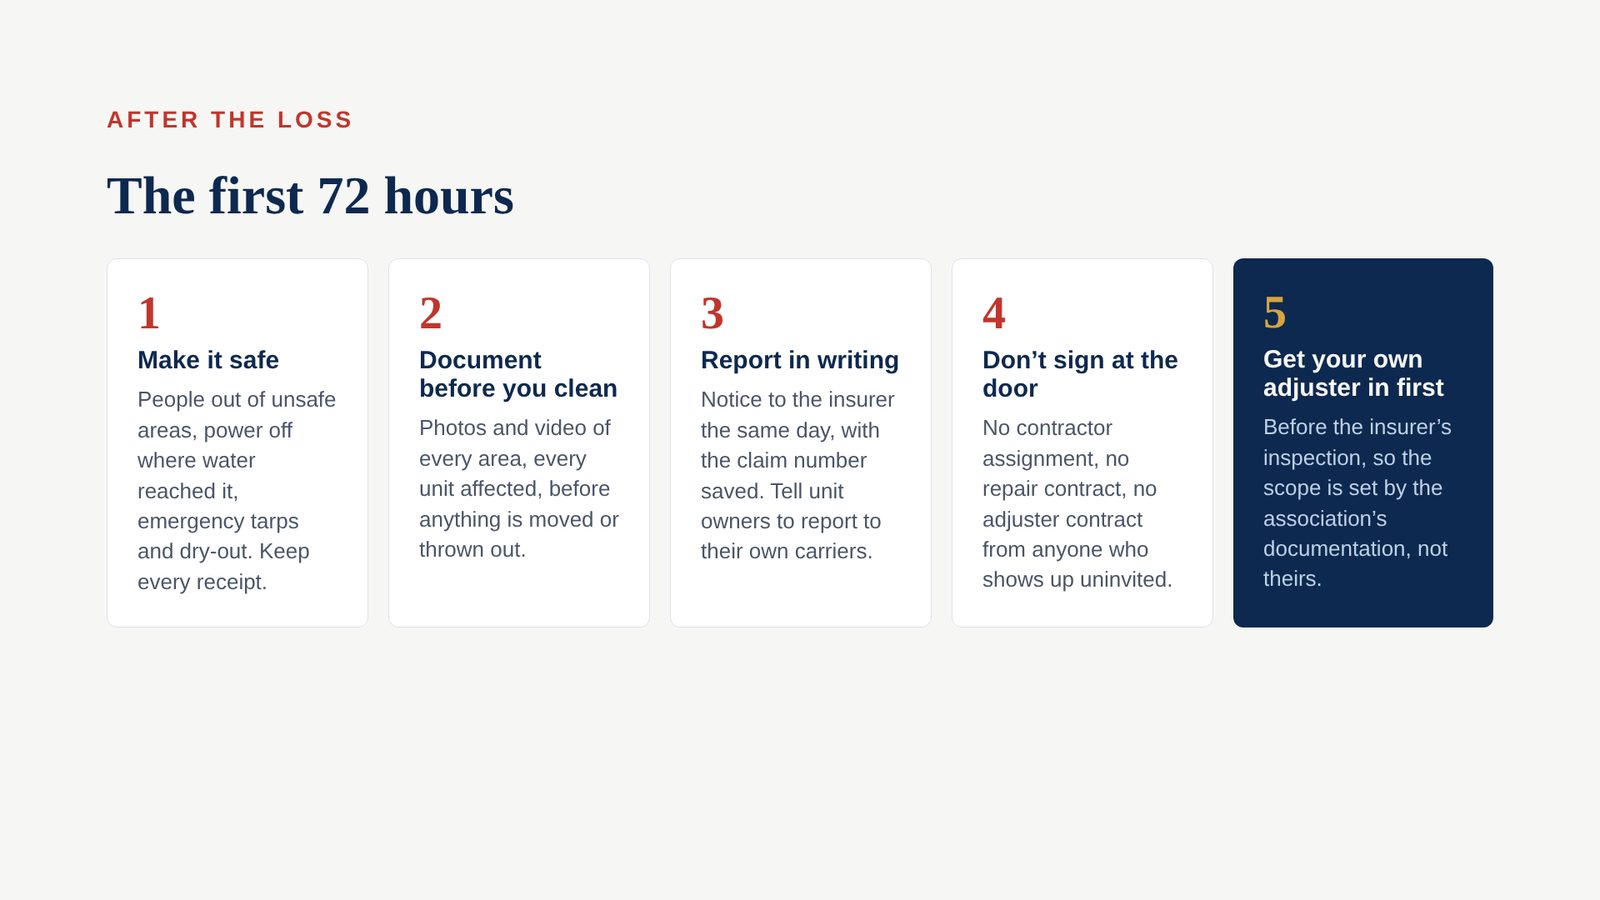
The first 72 hours, and where claims come up short
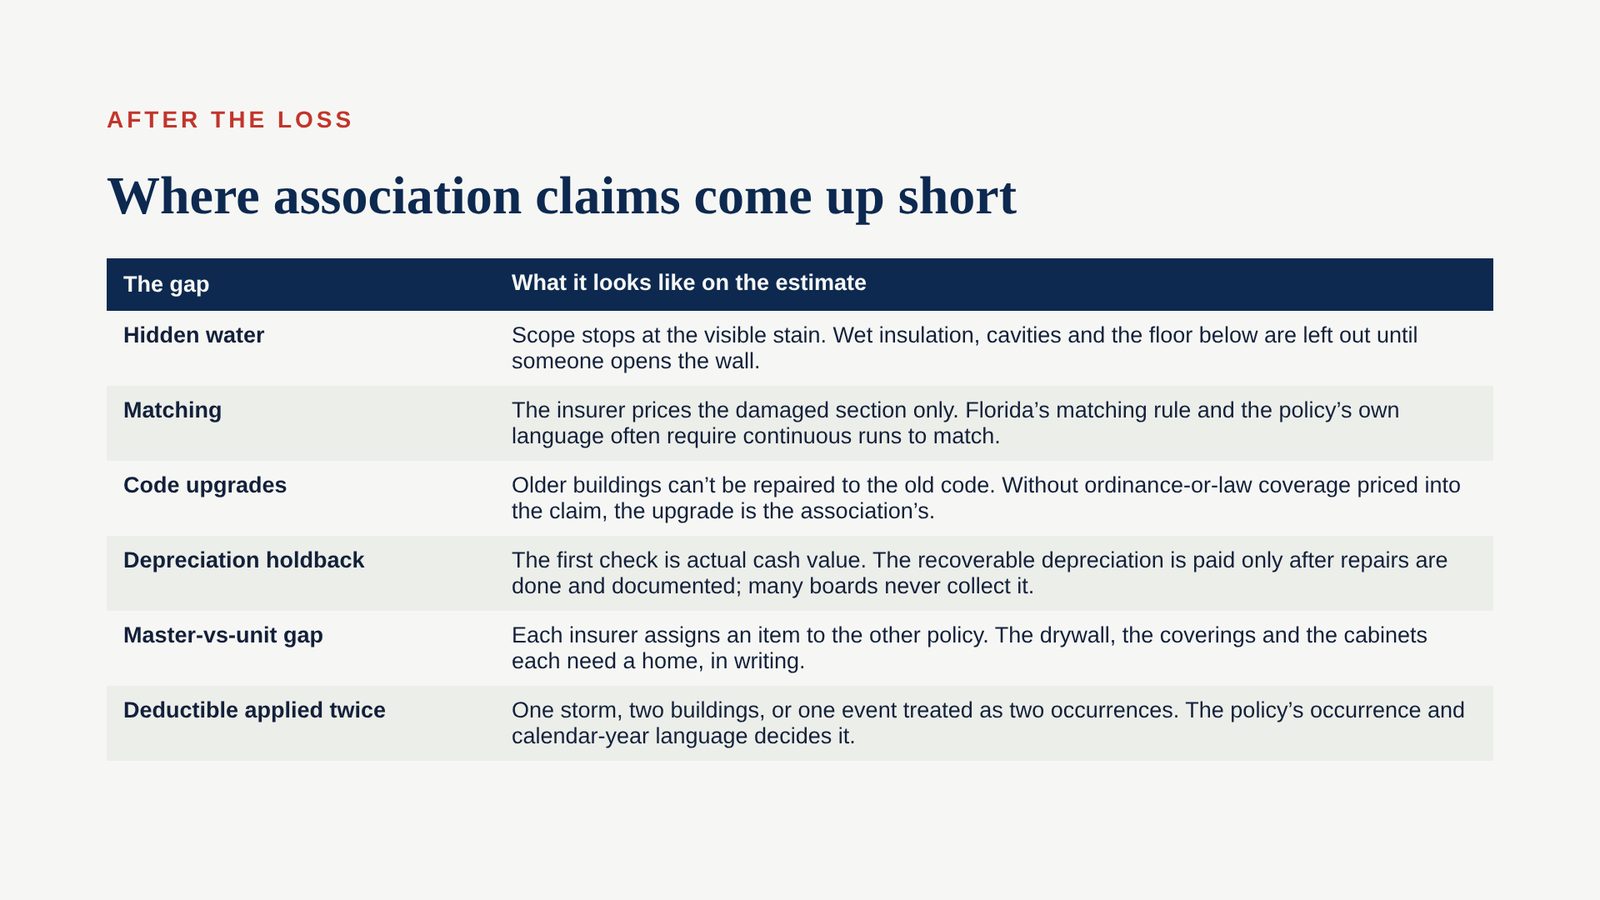
Hidden water, matching, code upgrades, depreciation holdback, the master-versus-unit gap, the deductible applied twice.
6
When the number is still short
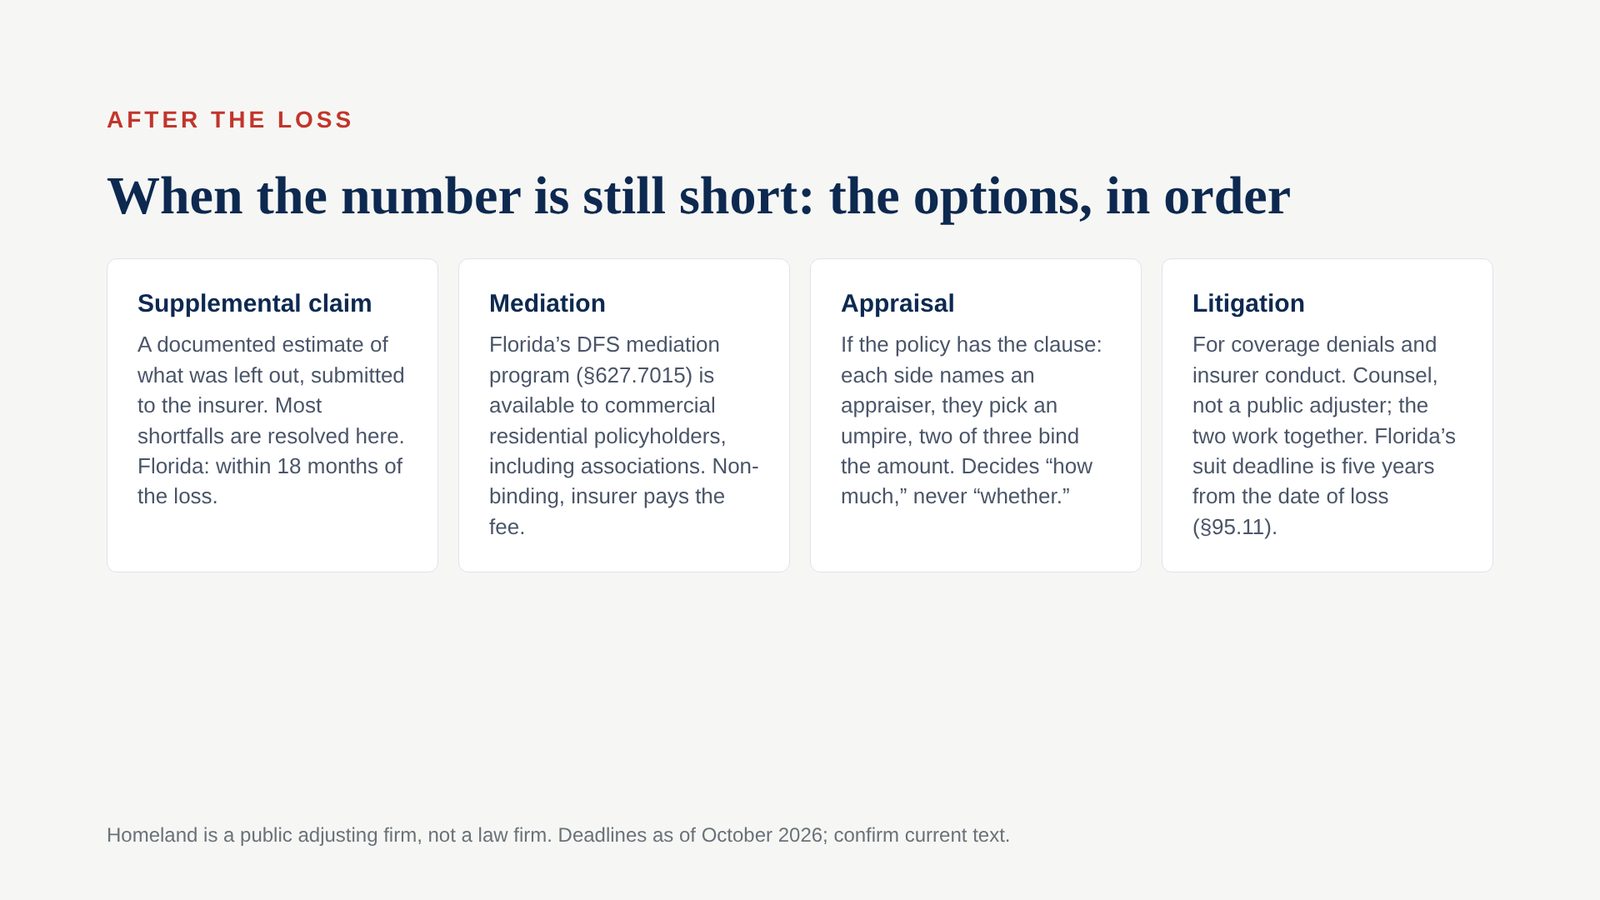
Supplemental claim, DFS mediation (§627.7015, available for commercial residential policies), appraisal, and when counsel is needed, in that order.
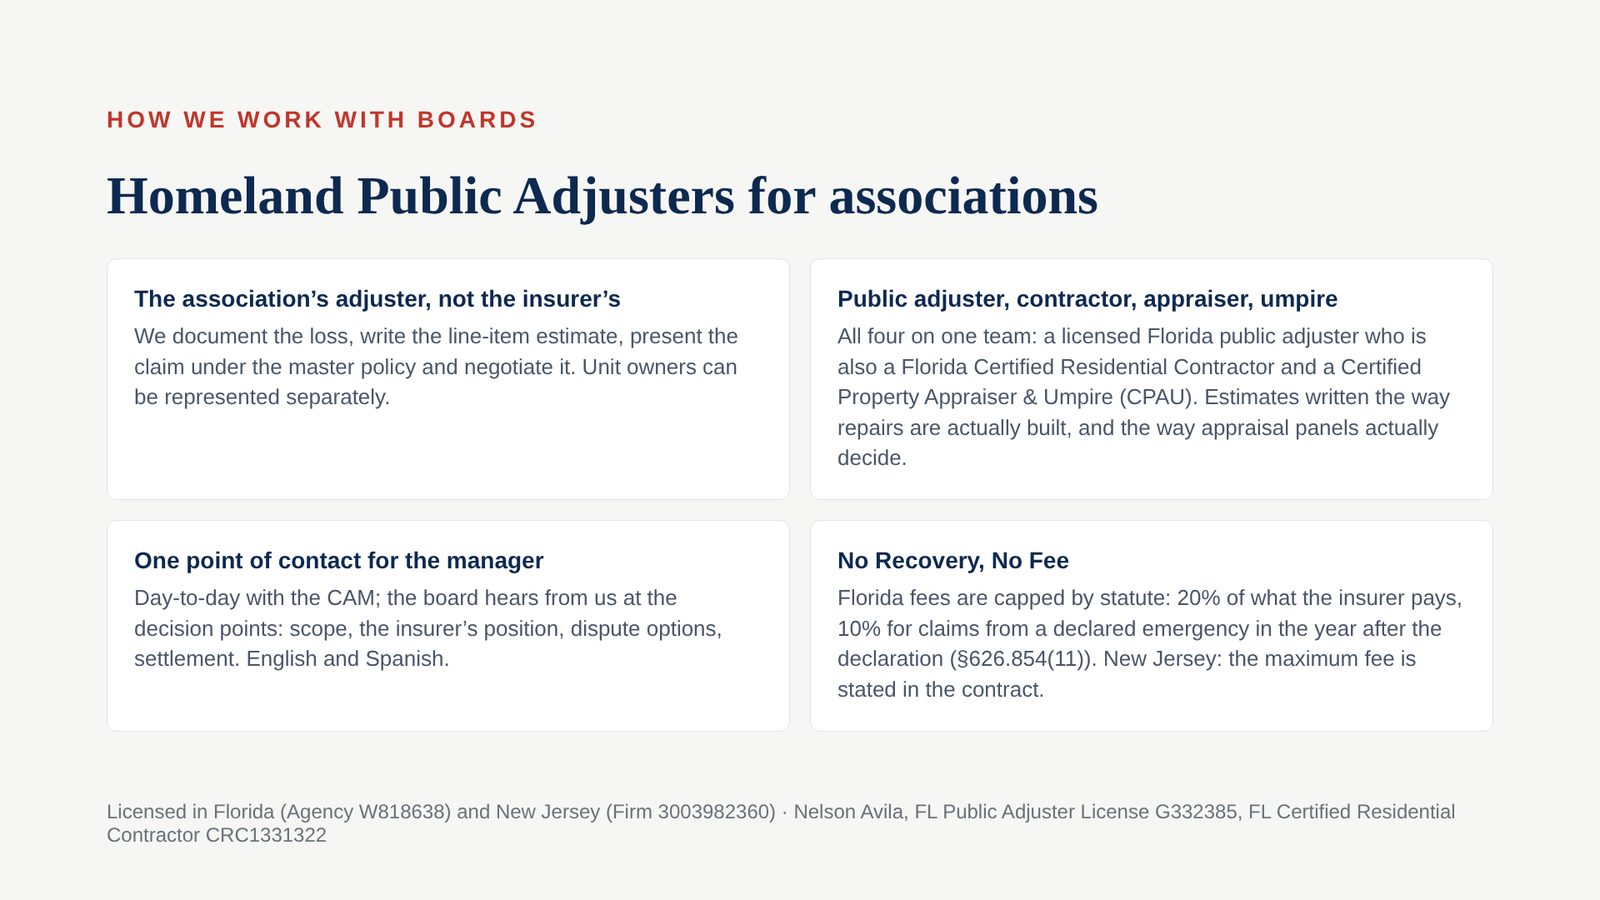
Vendor-neutral, no product sold from the podium. The session is education. The only ask at the end is a free review of a past claim file for any board that wants one. Presented by a licensed Florida public adjuster who is also a Florida Certified Contractor and a Certified Property Appraiser & Umpire. Homeland is a Business Partner member of the Community Associations Institute (CAI), Southeast Florida Chapter. Management companies and CAI chapters: we will complete any CEU paperwork your program requires.
Download the one-page handout (PDF)

Insurance Terms Every Board Member Should Know

The ten words that decide most association claims. Directors who know them read the adjuster’s letter the way the adjuster does.

Master policy: The association’s property policy on the building and common elements. In Florida its minimum scope is set by Fla. Stat. §718.111(11)(f). Master policy vs. HO-6 →
HO-6 (unit owner policy): The unit owner’s policy: finishes, cabinets, appliances, contents, loss of use, and loss assessment coverage.
Loss assessment coverage: The HO-6 coverage that pays an owner’s share of an assessment levied after a covered loss; Florida requires at least $2,000 on unit owner policies. Loss assessment and special assessments →
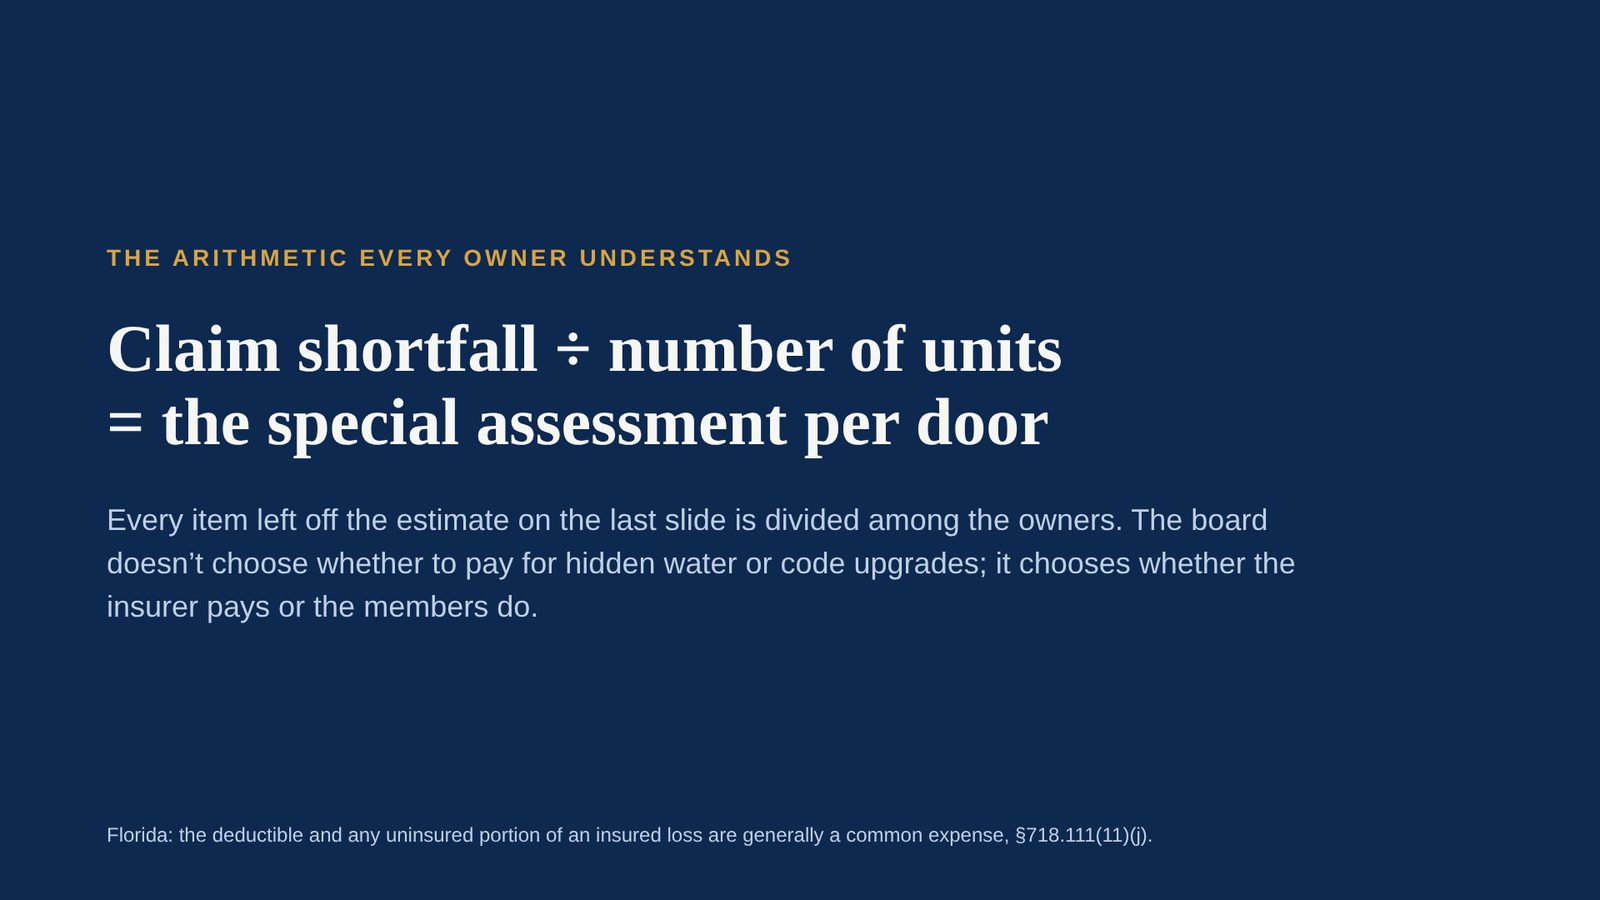
Special assessment: A charge to owners for a common expense the budget and reserves do not cover, including the master policy deductible and any uninsured portion of a loss (§718.111(11)(j)).
Hurricane deductible: A percentage of the insured value, not a flat dollar amount; on a $20 million building a 5% deductible is $1 million before the policy pays. How it works →
Ordinance or law coverage: Pays the extra cost of bringing a damaged building up to current code during repairs; often capped at a percentage of the limit.
Co-insurance: A penalty clause that reduces the payment when the building is insured for less than the required percentage of its value; a common problem on older buildings.
Proof of loss: The sworn statement of the amount claimed, due within the time the policy sets; the carrier’s clock in Florida starts when it is received.
Appraisal: The policy’s dispute process for the amount of the loss: two appraisers and an umpire, not a court. Florida appraisal explained →
Milestone inspection / SIRS: Florida’s structural inspection and reserve study requirements for condominium buildings three stories and taller; the reports are also the best pre-loss record of the building’s condition.

For Community Association Managers

Managers usually find the damage, make the first call and carry the claim for the board. Florida licenses community association managers under Part VIII of Chapter 468 for the financial, meeting and maintenance work of running an association; negotiating the amount of an insurance claim for compensation is public adjusting and is licensed separately. The session shows managers where their role ends and the adjuster’s begins, what to collect in the first 72 hours, and how to report to the board so the directors can decide quickly. New Jersey does not license community association managers at the state level; the same division of roles applies.

Management companies: one session covers every board you manage; we repeat it per community on request.
CAI chapters and manager meetings: the session fits a lunch program; we complete your CEU paperwork.
Spanish-speaking boards: the full session and handout are available in Spanish.

Open claim right now? Skip the session and call: Florida (305) 783-3777, New Jersey (732) 517-3777.

Request a Session

The Session, Slide by Slide

The twelve slides we present, so a board can preview the session or revisit it after the meeting. Scroll through, or download the slides as a PDF and the one-page handout.

Slide 1 of the Board Education Session: Insurance Claims for Condo & HOA Boards
Slide 1 of 12 · Insurance Claims for Condo & HOA Boards. Cover: what the master policy pays for, what the board has to prove, and how to keep a shortfall from becoming a special assessment.
Slide 2 of the Board Education Session: The master policy pays for what the association proves
Slide 2 of 12 · The master policy pays for what the association proves. The premise of the session: the insurer’s adjuster evaluates the claim for the insurer; if the board does not document the loss, the insurer’s number is the only number on the table.
Slide 3 of the Board Education Session: Who covers what after a loss
Slide 3 of 12 · Who covers what after a loss. The split between the association’s master policy and the unit owner’s policy under Fla. Stat. §718.111(11)(f); in New Jersey the master deed draws the line.
Slide 4 of the Board Education Session: Know the deductible before the season does
Slide 4 of 12 · Know the deductible before the season does. Percentage hurricane deductibles, who absorbs them under §718.111(11)(j), and the board’s homework at every renewal.
Slide 5 of the Board Education Session: The clocks that run on the association
Slide 5 of 12 · The clocks that run on the association. Florida’s one-year notice and 18-month supplemental deadlines; New Jersey’s 30-day insurer decision rule.
Slide 6 of the Board Education Session: The record the board should already have
Slide 6 of 12 · The record the board should already have. Dated photos, the policy in one place, roof history, the reserve study, a vendor list and a board resolution naming who may report a claim.
Slide 7 of the Board Education Session: The first 72 hours
Slide 7 of 12 · The first 72 hours. Make it safe, document before you clean, report in writing, don’t sign at the door, get your own adjuster in first.
Slide 8 of the Board Education Session: Where association claims come up short
Slide 8 of 12 · Where association claims come up short. Hidden water, matching, code upgrades, depreciation holdback, the master-vs-unit gap, and the deductible applied twice.
Slide 9 of the Board Education Session: Claim shortfall ÷ number of units = the special assessment per door
Slide 9 of 12 · Claim shortfall ÷ number of units = the special assessment per door. Every item left off the estimate is divided among the owners.
Slide 10 of the Board Education Session: When the number is still short: the options, in order
Slide 10 of 12 · When the number is still short: the options, in order. Supplemental claim, DFS mediation (§627.7015), appraisal, litigation.
Slide 11 of the Board Education Session: Homeland Public Adjusters for associations
Slide 11 of 12 · Homeland Public Adjusters for associations. The association’s adjuster; public adjuster, contractor, appraiser and umpire on one team; one contact for the manager; No Recovery, No Fee.
Slide 12 of the Board Education Session: Bring us your last claim file
Slide 12 of 12 · Bring us your last claim file. The ask: a free review of a closed or open association claim.

Board & Manager Session FAQs

Who is the session for?
Condominium, HOA, co-op and master association boards, community association managers, and management companies in Florida and New Jersey. It works as a board training, a manager meeting topic, or a chapter program.
How long is it, and where?
Thirty minutes plus questions. At your office, at the property, or by video. English or Spanish.
Is there a cost or a sales pitch?
No cost. The content is educational and vendor-neutral; nothing is sold from the podium. Boards that want one can ask for a free review of a past claim file afterward.
Can we get CEU credit?
If your management company or CAI chapter has a continuing-education process, we will complete whatever it requires. Ask when you request the session.
We have a claim open right now. Should we book a session or call?
Call. An open association claim gets a licensed public adjuster on the phone right away: Florida (305) 783-3777, New Jersey (732) 517-3777, 24 hours. The session is for boards that want to be ready before the next loss.
Call Now · Florida(305) 783-3777Call Now · New Jersey(732) 517-3777