Vendor Certificates of Insurance: What Condo and HOA Boards Should Require

Licensed public adjusters serving Florida & New Jersey
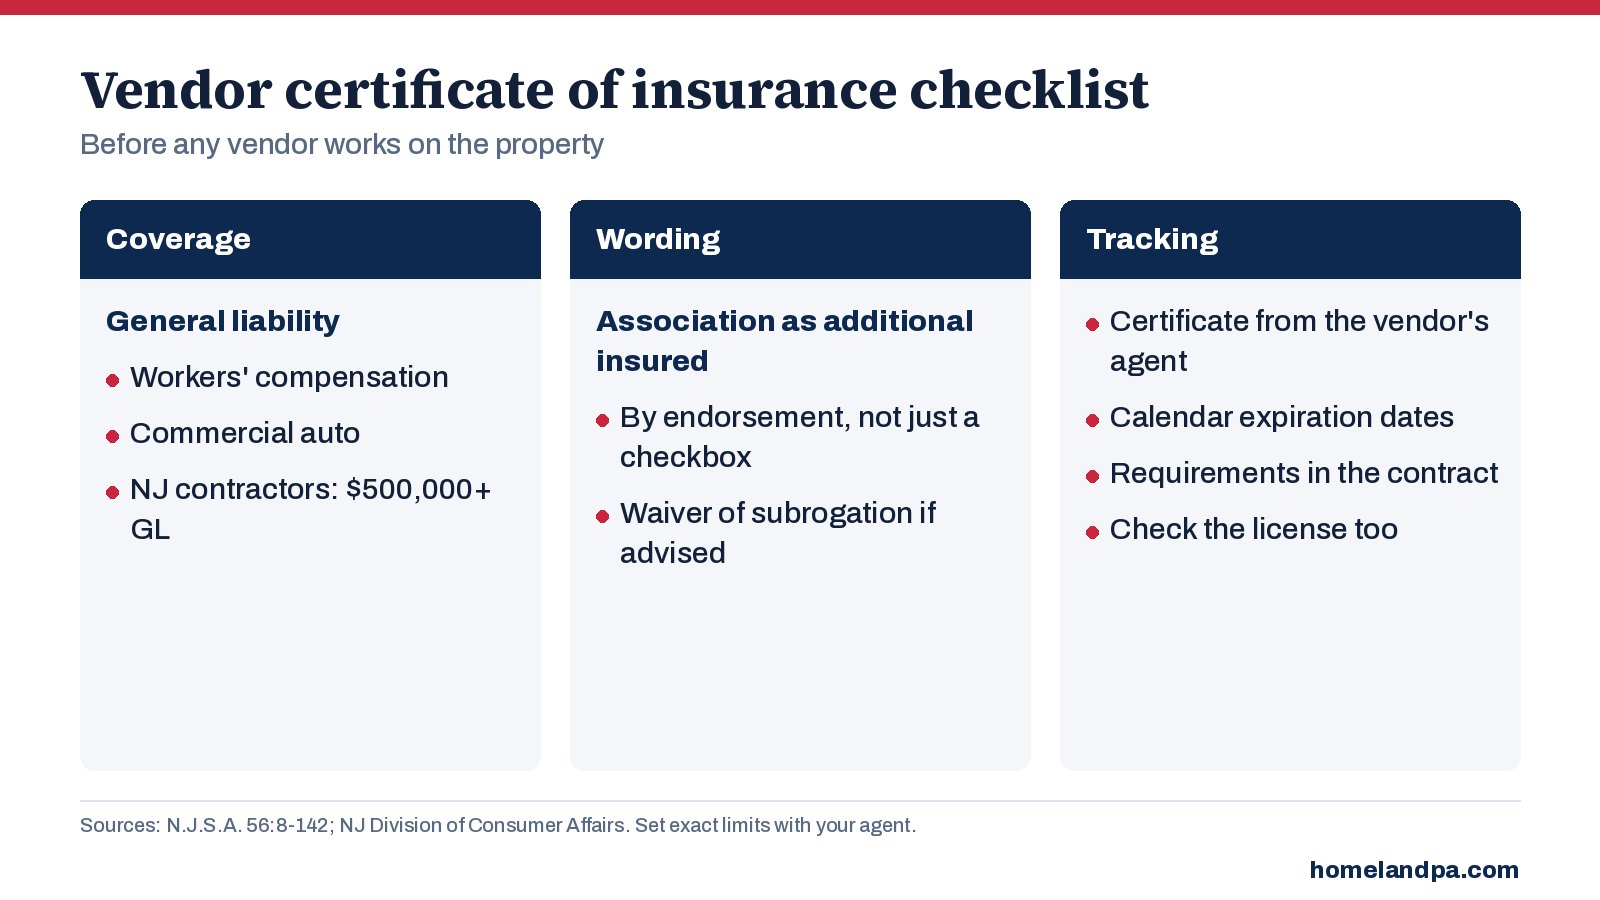
Short answer: before any vendor works on the property, the board or manager should have a current certificate of insurance showing general liability, workers’ compensation where required, and auto coverage, with the association named as additional insured. When an uninsured vendor floods a building or injures someone, the loss lands on the association’s own policies, and its deductible lands on the owners.
What to require
- General liability with limits the association’s agent recommends for the type of work. New Jersey requires registered home improvement contractors to carry at least $500,000 per occurrence (N.J.S.A. 56:8-142); higher-risk work (roofing, structural, high-rise) usually calls for more.
- Workers’ compensation where the law requires it, or a valid exemption.
- Commercial auto for vendors driving on the property.
- Additional insured status for the association (and the management company) on the vendor’s liability policy, by endorsement, not just a box on the certificate.
- Waiver of subrogation where the association’s agent recommends it.
- The vendor’s license, checked on the state database.
How to track it
- Collect the certificate before work starts, from the vendor’s agent, not the vendor.
- Calendar every expiration date and request renewals 30 days ahead.
- Put the insurance requirements in the contract, with indemnity language the association’s attorney approves.
- Keep certificates with the contract in the association’s records.
The free Adjuster Advantage for Associations app keeps vendor certificates with expiration reminders.
Frequently asked questions
Why should the association be an additional insured?
Is a certificate of insurance enough?
How much liability insurance must a New Jersey home improvement contractor carry?
Sources: NJ Division of Consumer Affairs, home improvement contractor FAQ; N.J.S.A. 56:8-142 (current text as reprinted); Florida DBPR license search.
This guide is general information for association boards and managers, current as of October 2026. It is not legal advice. Your governing documents, your policies and your association’s attorney control. Ask the association’s insurance agent and attorney to set your exact requirements.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim Review