
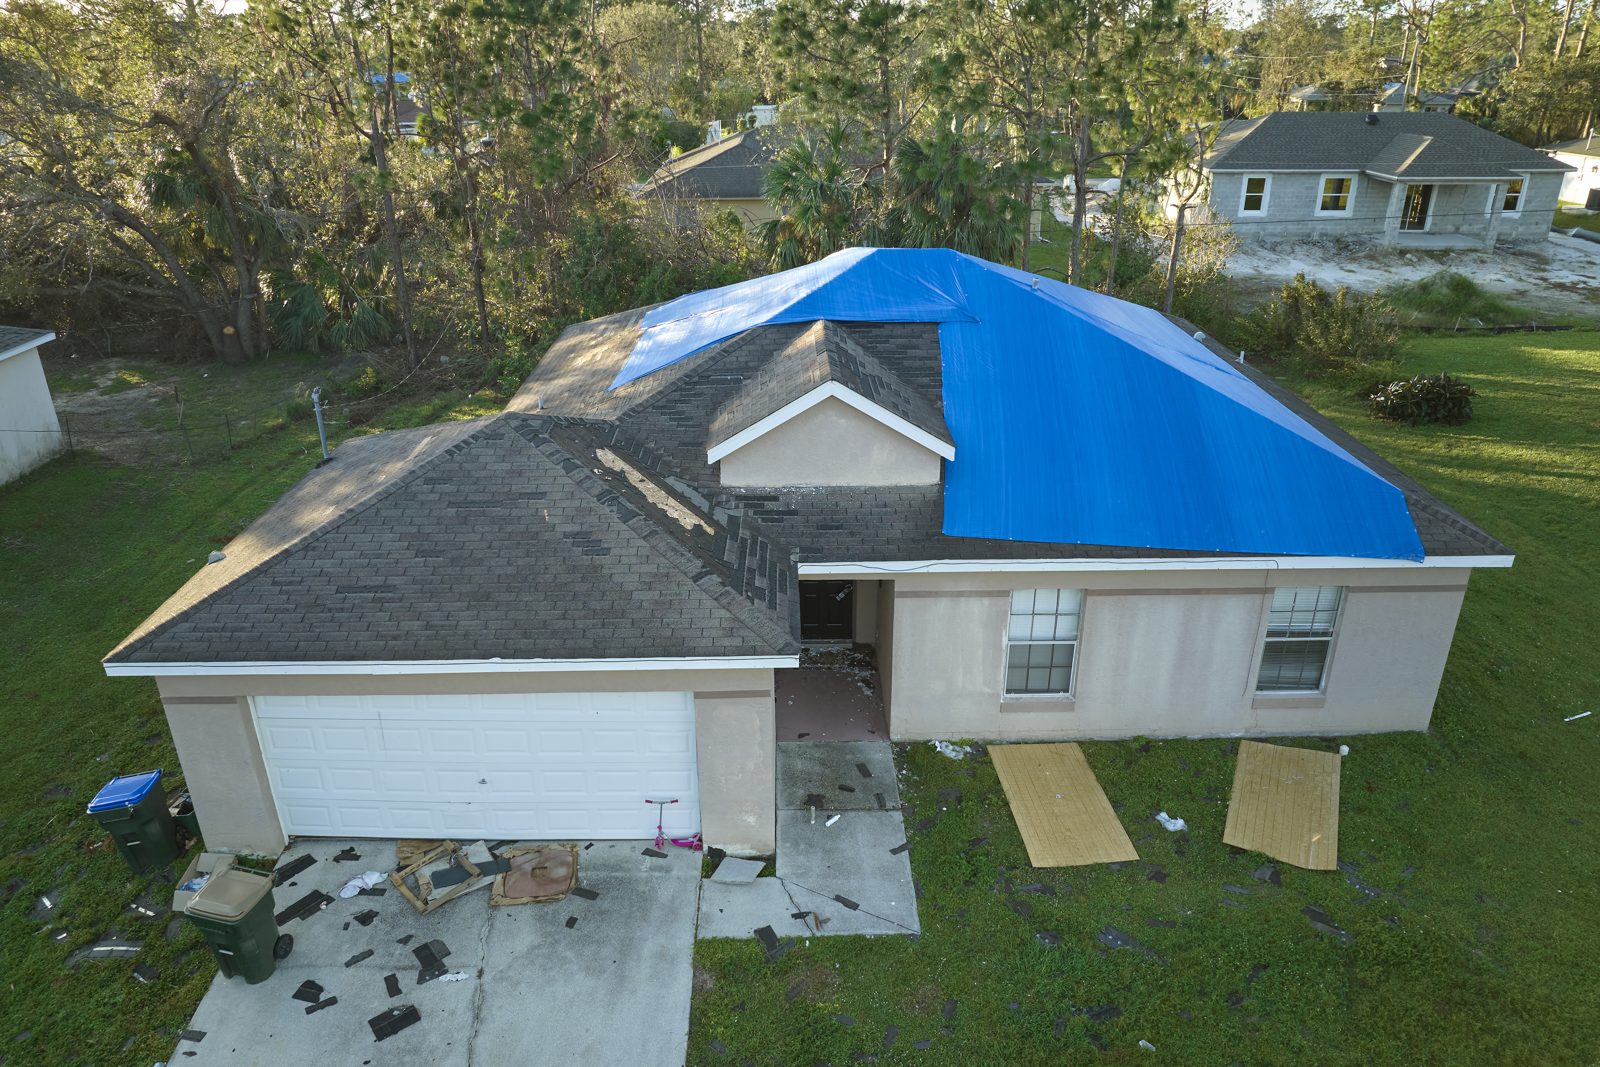
Wherever you are in Central Florida, we come to you. A licensed Homeland public adjuster comes to your property within hours — Orlando, Kissimmee, Lakeland, Daytona Beach, Ocala, Sebring and Tampa Bay, every city in every county — no need to visit an office. Serving Florida property owners since 2006, in English and Spanish.
Short answer: Central Florida public adjusters are licensed adjusters who represent property owners, not insurance companies, on hurricane, roof, water and other claims. Homeland Public Adjusters has served Florida property owners since 2006, from Orlando, Kissimmee and Lakeland to Daytona Beach, the Space Coast, Ocala, Sebring and Tampa Bay, with a local line in each area code, 24/7. No Recovery, No Fee.
Homeland Public Adjusters represents homeowners, condominium associations, landlords and businesses across Central Florida: Orange, Osceola, Seminole, Lake, Polk, Volusia, Brevard, Marion and Highlands counties, and the Tampa Bay counties of Hillsborough, Pinellas, Manatee and Sarasota. Central Florida’s claims are hurricane wind and rain, lightning (Florida leads the nation in lightning claims, and the Tampa–Orlando corridor leads Florida), sinkhole-prone ground, and the water and roof losses of a housing stock built fast in the last thirty years. We inspect, document and negotiate the claim with your insurer. No Recovery, No Fee. Call 24/7.
Last reviewed: October 2026
How Can We Help You Recover, or Prepare?
Why Central Florida Claims Are Different
Central Florida sits where every Gulf and Atlantic storm track crosses the peninsula. Hurricane Ian (2022) came ashore in Lee County and tracked straight through Orlando, flooding neighborhoods that had never filed a claim; Milton (2024) did the same from Sarasota through Polk and Orange. The region’s other signature losses are lightning (Florida leads the nation in lightning claims and the I-4 corridor leads Florida), sinkhole activity in Marion, Pasco, Hernando and Polk, and the roof-age and water-damage endorsements that carriers have loaded onto the region’s 1990s–2000s housing stock. The disputes we see most: percentage hurricane deductibles applied to underscoped roofs, wind-driven rain called “seepage,” lightning damage to electronics denied as “power surge,” and roof payment schedules applied to the whole claim instead of the shingles.
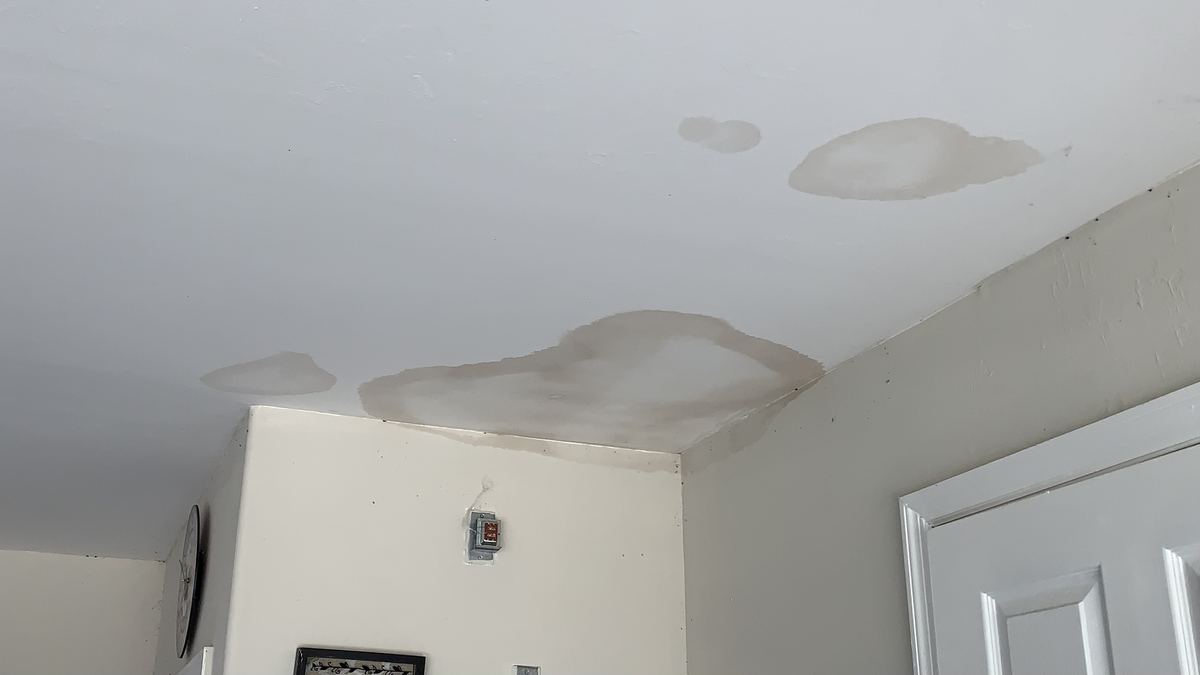
Hurricane Milton and Ian: What Happened to Central Florida Claims
The Office of Insurance Regulation publishes claim counts by county after each storm. Two things stand out in the Central Florida rows: the share of claims closed without any payment, and how many of those were in counties the storms crossed as weakened but still destructive systems.
| County | Milton claims (Dec 2025) | Milton closed without payment | Ian claims (Mar 2025) | Ian closed without payment |
|---|---|---|---|---|
| Hillsborough (Tampa) | 74,851 | 25,871 | — | — |
| Pinellas (St. Petersburg, Clearwater) | 55,848 | 20,153 | — | — |
| Manatee (Bradenton) | 38,535 | 10,214 | — | — |
| Sarasota | 31,786 | 9,434 | 78,171 | 21,181 |
| Polk (Lakeland) | 24,203 | 8,236 | 27,659 | 8,865 |
| Volusia (Daytona Beach) | 17,482 | 6,803 | 41,808 | 14,903 |
| Orange (Orlando) | 15,024 | 6,617 | 35,411 | 15,013 |
| Lake | 13,875 | 5,502 | — | — |
| Osceola (Kissimmee) | 8,091 | 2,868 | 12,206 | 4,890 |
| Brevard (Space Coast) | 6,043 | 2,353 | 6,056 | 2,496 |
| Seminole | 4,478 | 2,049 | 12,202 | 5,482 |
Ian county figures are closed-with-payment plus closed-without-payment as reported by OIR; “—” means the county was not broken out on that storm’s report. A claim closed without payment is not necessarily a correct denial: in Florida it can be reopened within one year of the date of loss, and a supplemental claim for damage found later can be filed within 18 months (§627.70132). For Milton (landfall October 9, 2024) the supplemental window ran to April 2026; for Ian it has closed, but open claims and litigation continue.
Orlando and the I-4 Corridor
Orange, Osceola and Seminole counties carry Florida’s second-highest litigation rate after the tri-county area, which tells you how often carriers and policyholders disagree here. The Orlando metro’s claims are hurricane rain and wind on tile and shingle roofs, lightning strikes on homes and HVAC systems, water losses in slab-on-grade homes with aging polybutylene and CPVC plumbing, and theme-park-corridor short-term rentals whose carriers argue vacancy and business use after every loss. Our Orlando and Kissimmee pages carry the (407) line; vacation-rental owners should also read our short-term rental page.
Local lines: Orlando and Kissimmee, (407) 863-3777.Local lines: (407) 863-3777, (813) 807-3777, (727) 390-3777, (941) 267-3777, (863) 485-3777, (386) 388-3777, (321) 351-3777, (352) 677-3777 · Main office: (305) 783-3777. All reach the same Homeland team, 24/7.
Tampa Bay: Hillsborough, Pinellas, Manatee and Sarasota
Milton made Tampa Bay the center of Florida’s 2024 claims: more than 200,000 claims in the four bay counties, 65,000 of them closed without payment. Helene’s surge two weeks earlier had already flooded barrier-island homes from Clearwater to Anna Maria, which produced the hardest claims in the state: wind from Milton on top of flood from Helene, two carriers, two dates of loss, and an anti-concurrent causation clause in every denial letter. We separate the two losses with the physical evidence and build both claims to the same facts. Local pages: Tampa, St. Petersburg, Clearwater, Pinellas County, Bradenton and Sarasota.
Local lines: Tampa, (813) 807-3777; St. Petersburg, Clearwater and Pinellas County, (727) 390-3777; Bradenton and Sarasota, (941) 267-3777.
Lakeland, Polk County and the Heartland
Polk County was crossed by Ian, Milton and Charley before them, and its claims mix adds agriculture: citrus groves, cattle, packing houses and nurseries insured on farm and ranch forms, where the structures are scheduled and the crops are not. See our agricultural properties page and the Lakeland and Sebring pages, both on the (863) line.
Local lines: Lakeland and Sebring, (863) 485-3777.
Daytona Beach and the Space Coast
Volusia and Brevard take the Atlantic side of every storm that crosses the state, and Volusia filed more Ian claims than Orange County. Beachside condominiums from Daytona to Cocoa Beach are master-policy claims with percentage deductibles that can run into six figures; see condo and HOA associations.
Local lines: Daytona Beach, (386) 388-3777; Cocoa Beach and Brevard County, (321) 351-3777.
Ocala, Marion County and Gainesville
Marion County (Ocala) adds the state’s most active sinkhole ground and horse-farm structures; see our agricultural properties page. Farther north, inland doesn’t mean safe from storms: Gainesville and Alachua County property owners bring us wind, fallen-tree and inland flooding claims.
Local lines: Ocala and Gainesville, (352) 677-3777.
Common Central Florida Claims
Most of the Central Florida claims we handle fall into a few groups. Each one has its own coverage questions.
What a Central Florida Public Adjuster Does for You
Homeland works on a No Recovery, No Fee basis, and Florida law caps public adjuster fees. See public adjuster fees.
Central Florida Public Adjuster FAQs
Do you have an office in Orlando or Tampa?
Is it too late to file a Milton or Ian claim?
My Central Florida claim was closed without payment. What now?
Does the hurricane deductible apply to a tropical storm?
Do you handle sinkhole claims in Marion, Pasco or Polk?
How do I reach a Central Florida public adjuster after hours?
Do you handle condo and HOA claims in Central Florida?
Central Florida Public Adjusters, City by City
Every Central Florida page below has its own local line that rings our adjusters directly. Not listed? We serve all of Central Florida; call the Orlando line.
Talk to a Public Adjuster
How Can We Help You Recover, or Prepare?
Tell us about your loss. We’ll call you back.

Claims We Handle Across Central Florida
From a lightning strike in Lakeland to a Milton roof in Pinellas, these are the claims Central Florida property owners bring us.
Verify Homeland
Check us before you hire anyone. Every license below links to its public record on the Florida Department of Financial Services licensee search.
- Serves all of Florida: Yes — every city and county. A licensed Homeland public adjuster comes to your property within hours — no need to visit an office. Call (305) 783-3777, 24/7.
- Homeland Public Adjusters Corporation: Florida public adjusting firm license W818638 · New Jersey public adjuster firm license 3003982360
- Yeni Martinez, President: Florida public adjuster license P103370 (licensed since 2007) · New Jersey 3003714097 · designated primary adjuster
- Alberto Enriquez: Senior licensed public adjuster, Florida P112658
- Yisel Dieguez: Licensed public adjuster and Xactimate estimator, Florida W873884 · New Jersey 3003714335
- Nelson Avila: Florida public adjuster license G332385 · Florida Certified Contractor CRC1331322 · property insurance appraiser and umpire
- Complaints and reputation: 5.0★ on Google · BBB Accredited Business, A+ rating
- Since 2006: Homeland Public Adjusters, Corp. was incorporated in Florida on December 11, 2006. Our President, Yeni Martinez, has held Florida public adjuster license P103370 since 2007. When Florida began requiring adjusting firms to hold their own firm license (a 2021 law, Senate Bill 1598; DFS began licensing adjusting firms in November 2021), Homeland was issued firm license W818638 on January 11, 2022. On November 10, 2026, Homeland became a BBB Accredited Business (BBB Serving Southeast Florida & the Caribbean), with an A+ rating. Each adjuster’s appointment with Homeland appears on that adjuster’s own DFS record.
- English and Spanish. Office: 8004 NW 154th Street, Suite 609, Miami Lakes, FL 33016 (visits by appointment). Florida (305) 783-3777 · New Jersey (732) 517-3777, 24/7.