Florida’s $10,000 Water Damage Sublimit: What It Means for Your Claim

Homeland Public Adjusters · Last reviewed: October 2026
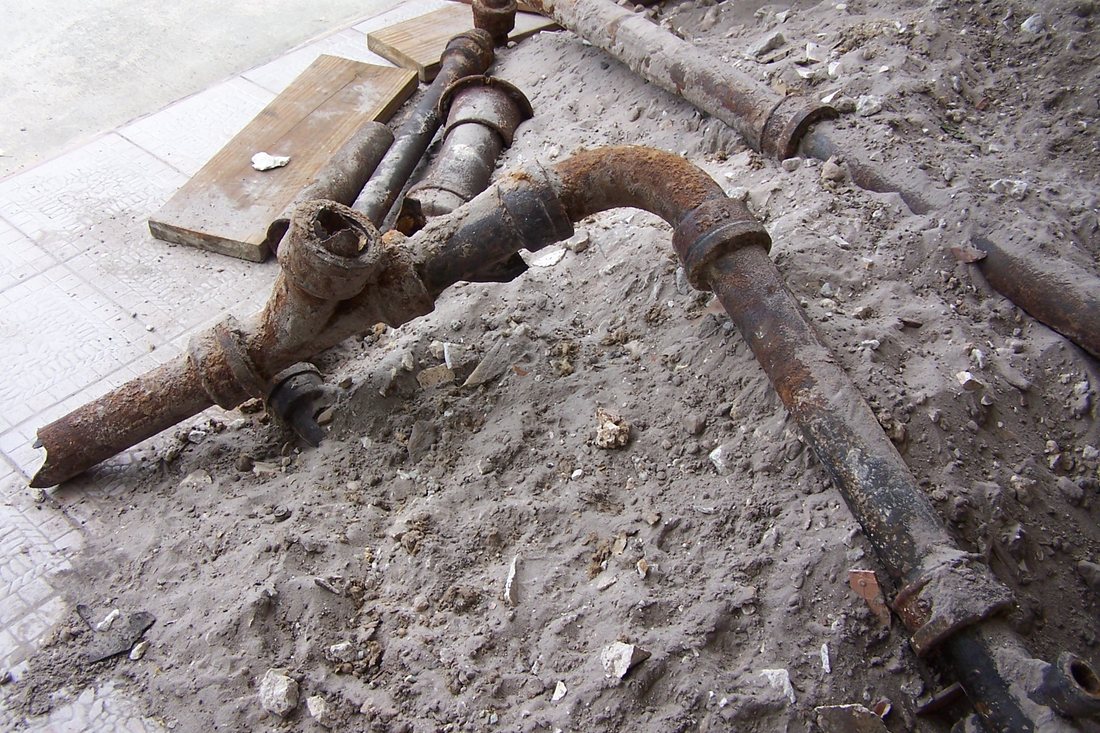
Over the past several years, a majority of Florida property insurers have adopted a $10,000 cap on coverage for non-weather water damage — a failed water heater, a burst supply line, a washing machine hose letting go — particularly on homes over 40 years old. This is separate from hurricane or storm-driven water damage, which is its own coverage question.
Have a property claim anywhere in Florida? A licensed Homeland public adjuster comes to you within hours — no need to visit an office. Call (305) 783-3777 (Florida) or (732) 517-3777 (New Jersey), 24/7.
Where this shows up most
Short answer: Many Florida insurers now cap non-weather water damage, like a burst supply line or failed water heater, at $10,000, particularly on homes over 40 years old. Citizens applies the cap unless you use its managed repair contractor, and many homeowners don’t learn their policy has it until they are mid-claim.
Citizens Property Insurance Corporation caps non-weather water damage at $10,000 unless the policyholder agrees to use a contractor from Citizens’ own managed repair program, in which case the cap doesn’t apply. As Citizens has worked to move policies to private insurers through its depopulation (“takeout”) process, a number of the private insurers receiving those policies have adopted similar $10,000 caps of their own.
Why the cap catches people off guard
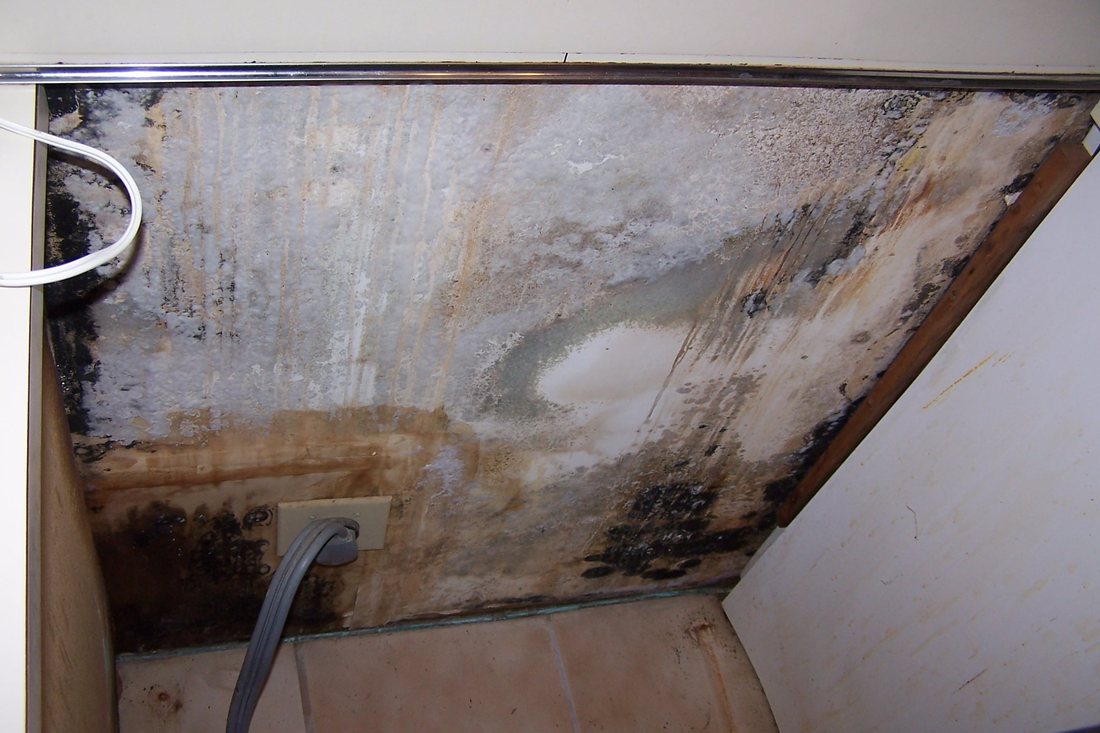
$10,000 sounds reasonable until it meets an actual claim. A failed water heater in a two-story home can mean torn-out drywall, flooring, cabinetry, and mold remediation across multiple rooms — well past that number. Many homeowners don’t learn their policy carries this cap until they’re already mid-claim.
How a restoration or mitigation company can use up the cap before you even file
After a water loss, the company that reaches the property first is often a restoration or mitigation contractor — found through an ad, a truck parked on the street, or the carrier’s own “preferred vendor” list — not a public adjuster. That company’s emergency work (water extraction, industrial drying equipment, tear-out of wet materials) gets billed directly against this same $10,000 sublimit, and it can consume the entire cap before anyone has even assessed the structural repairs, flooring, or cabinetry the loss actually requires. By the time a homeowner learns the sublimit exists, it may already be spent on mitigation alone — leaving nothing toward the repairs that follow.
The exception worth knowing
On a Citizens policy, agreeing to the insurer’s managed repair program removes the cap entirely. Whether that trade-off — the carrier choosing the contractor — makes sense depends on the specific loss and policy; it isn’t automatically the better choice.
Call Homeland before you speak with the insurance company, and before signing anything with a restoration or mitigation company, after a non-weather water loss — especially on an older home. Whether your policy carries this sublimit, and how much of it a first responder might already be spending, is worth knowing before a number gets put on the table.
Water-damage sublimits come up constantly on claims in Hialeah, Pembroke Pines and Cape Coral.
Frequently asked questions
What is Florida’s $10,000 water damage cap?
Does the $10,000 cap apply to Citizens policies?
Can a restoration company use up my water damage cap?
This article is for general information only and is not legal or insurance advice. Always review your own policy’s water damage provisions.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewThis topic often comes up alongside Florida's Matching Law and the New 1% Payout Cap: What Homeowners Should Know. If your situation involves this kind of loss, see our Water Damage page for how Homeland can help with the claim itself.