Florida’s Matching Law and the New 1% Payout Cap: What Homeowners Should Know

Homeland Public Adjusters · Last reviewed: October 2026
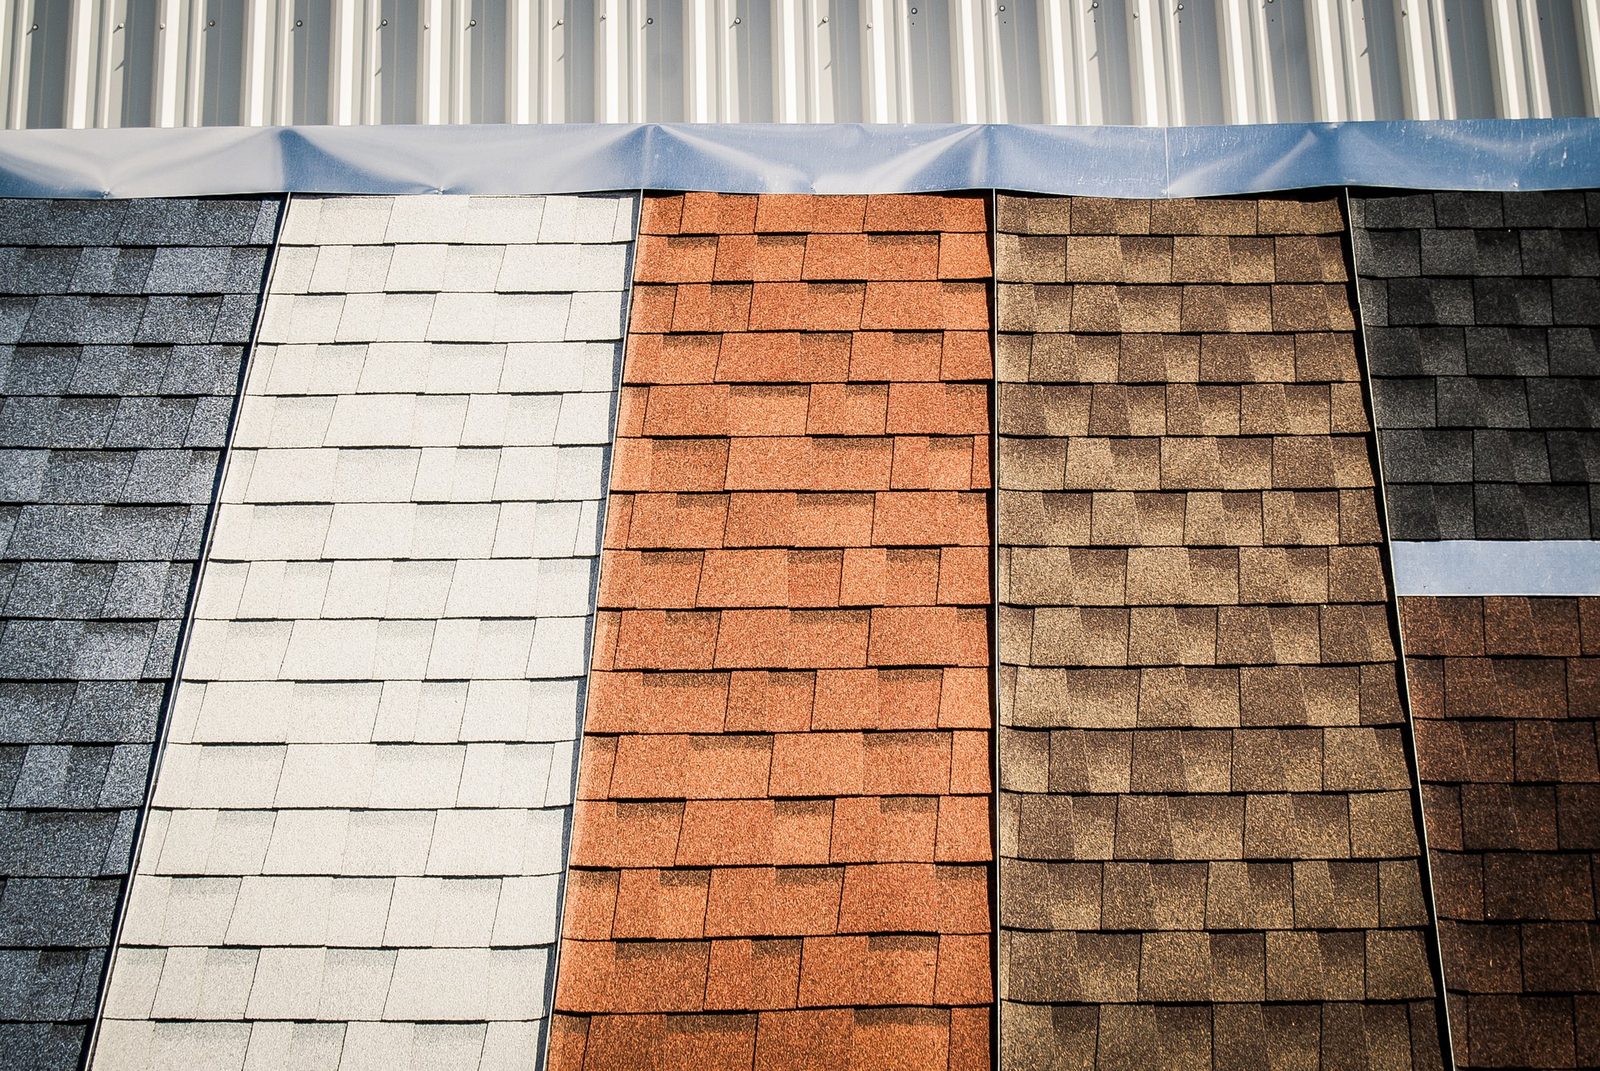
Florida Statute 626.9744 generally requires that when an insurer repairs part of a covered loss, and the new materials won’t reasonably match the undamaged remainder in quality, color or size, the insurer has to address that mismatch too — repairing or replacing enough of the adjoining undamaged material that the result looks consistent, not patched.
Have a property claim anywhere in Florida? A licensed Homeland public adjuster comes to you within hours — no need to visit an office. Call (305) 783-3777 (Florida) or (732) 517-3777 (New Jersey), 24/7.
How insurers have responded
Short answer: Florida Statute 626.9744 generally requires the insurer to address a mismatch when repaired materials won’t reasonably match the undamaged rest. But a number of insurers now use OIR-approved endorsements that cap matching at 1% of your dwelling limit, which is $3,000 on a $300,000 home.
Since 2022, Florida’s Office of Insurance Regulation has approved “matching limitation” endorsements from a number of insurers (Citizens’ was approved in August 2022, and about 25 insurers were listed by September 2023). The ones published so far cap what the carrier pays toward matching undamaged areas at 1% of your dwelling (Coverage A) limit. On a $300,000 dwelling limit, that’s $3,000 toward matching, regardless of what the repair actually costs.
Why that number is often not enough
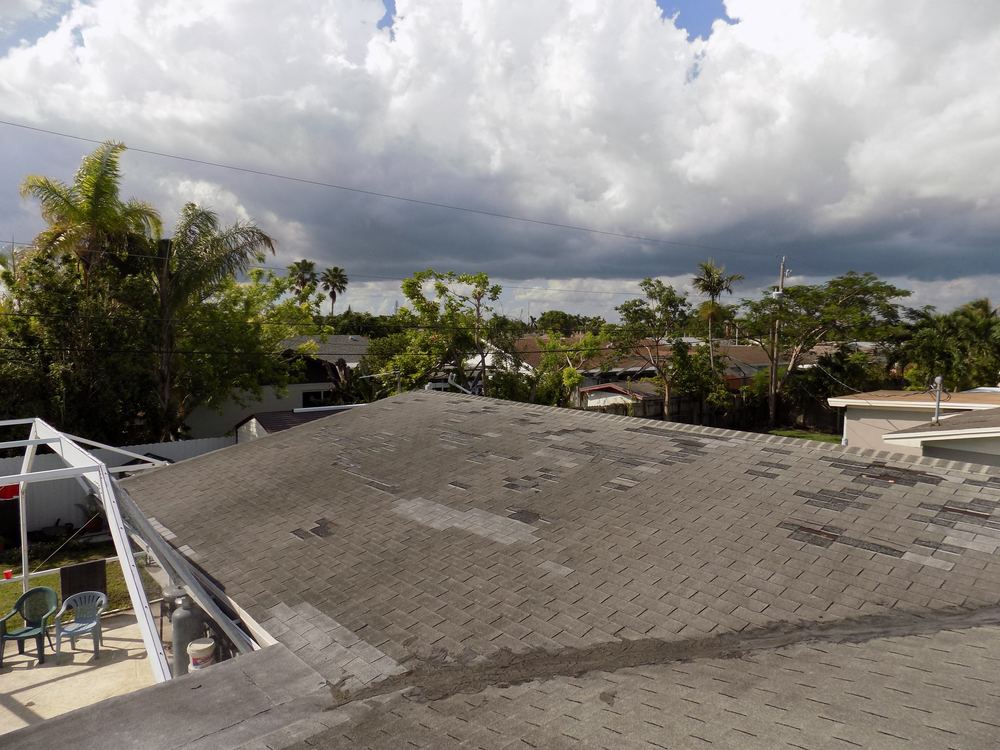
Discontinued shingle colors, aged siding, or roofing material no longer manufactured can mean the only way to actually match is replacing far more than 1% covers — sometimes an entire roof slope or side of a house. When the endorsement applies, the dollar cap, not the visual outcome, decides how far the repair goes.
Call Homeland before you speak with the insurance company about a repair that won’t match the rest of your home. Whether a matching-limitation endorsement applies, and what it actually caps, changes how the claim should be built from the start.
Matching disputes are a regular issue on Homeland's claims in Coral Springs, Boca Raton and Sarasota.
Frequently asked questions
What does Florida’s matching law require?
What is the 1% matching cap?
This article is for general information only and is not legal or insurance advice. Always review your own policy and any endorsements for the exact matching language.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewThis topic often comes up alongside Florida's $10,000 Water Damage Sublimit: What It Means for Your Claim. If your situation involves this kind of loss, see our Hurricane & Wind Damage page for how Homeland can help with the claim itself.