Florida’s Roof Repair Rules Changed: Why a Full Replacement Isn’t Automatic Anymore

Homeland Public Adjusters · Last reviewed: October 2026
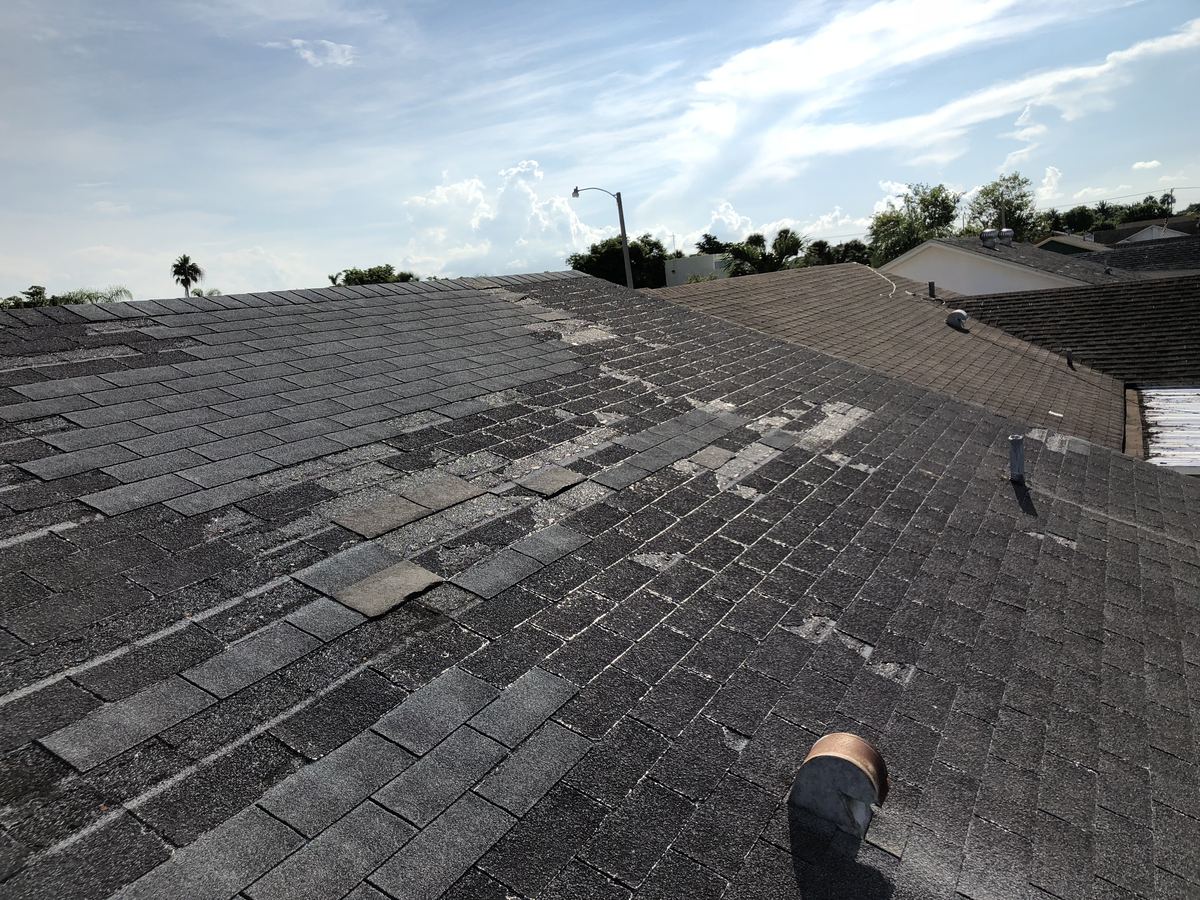
For years, many Florida jurisdictions followed a building-code rule requiring a full roof replacement whenever more than 25% of the roof was damaged within a 12-month period — commonly called the “25% roof replacement rule.” Senate Bill 4D, passed in a May 2022 special session, changed the statewide building code to loosen that requirement, making it easier for a roof to be repaired in sections rather than replaced in full.
Have a property claim anywhere in Florida? A licensed Homeland public adjuster comes to you within hours — no need to visit an office. Call (305) 783-3777 (Florida) or (732) 517-3777 (New Jersey), 24/7.
What this means for a roof claim
Short answer: Senate Bill 4-D (May 2022) changed Florida’s old “25% rule”: if the roof was built or replaced to the 2007 Florida Building Code or later, only the repaired section has to meet current code, so damage to a quarter of the roof no longer makes a full replacement automatic. The roof claim now turns on documenting the full scope of damage and whether materials can perform to code on the undamaged sections.
Before this change, hitting the 25% threshold was a strong, code-based argument for a full roof replacement on a covered loss. That argument carries less weight today. Carriers can more often point to the code change to justify offering a partial repair instead of a full roof replacement, even on damage that affects a meaningful portion of the roof.
What still matters
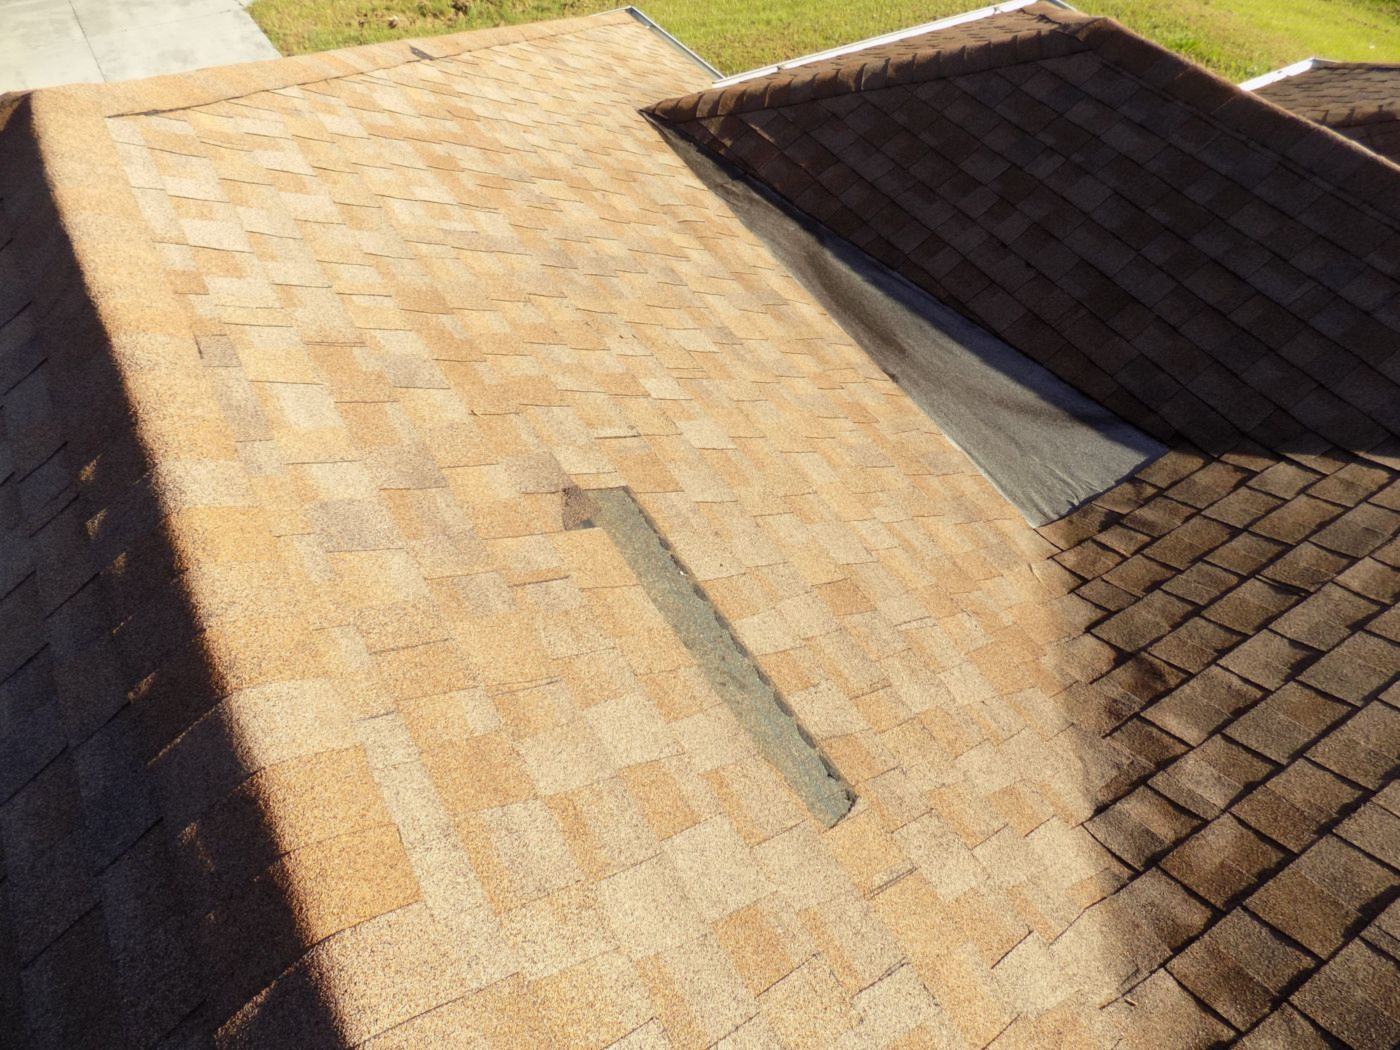
The code change affects the building-code trigger — not whether the underlying damage is covered, or how extensive it actually is. A roof claim still turns on thoroughly documenting the full scope of damage, not just what’s visible from one vantage point, and on whether available materials can perform to code on the undamaged sections — a separate question from the matching issue above.
Call Homeland before you accept a partial-repair offer on a roof claim. Documenting the full extent of the damage — not just the parts the adjuster points to — is what determines whether a partial repair is the right outcome or just the cheaper one.
Homeland documents roof claims in Miami Gardens, Lakeland and Port St Lucie, where partial-repair offers are common.
Frequently asked questions
What is Florida’s 25% roof replacement rule?
Can my insurer offer a partial roof repair instead of a full replacement in Florida?
Does the roof code change affect whether my roof damage is covered?
This article is for general information only and is not legal or insurance advice. Always review your own policy’s roof-specific provisions and any endorsements.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewThis topic often comes up alongside Florida's $10,000 Water Damage Sublimit: What It Means for Your Claim. If your situation involves this kind of loss, see our Hurricane & Wind Damage page for how Homeland can help with the claim itself.