Lost rental income, tenant-caused damage or a loss between tenancies. A rental loss hits the property, the tenant and your income all at once.
Home » Clients » Landlords & Rental Property Owners
Homeland Public Adjusters represents landlords and rental property owners in Florida and New Jersey, whether you own a single rental, a handful of units or a multifamily building. Short-term and vacation rentals have their own page. We document the property damage and the lost rental income, review your landlord policy, and present the claim to your insurance company on your behalf.
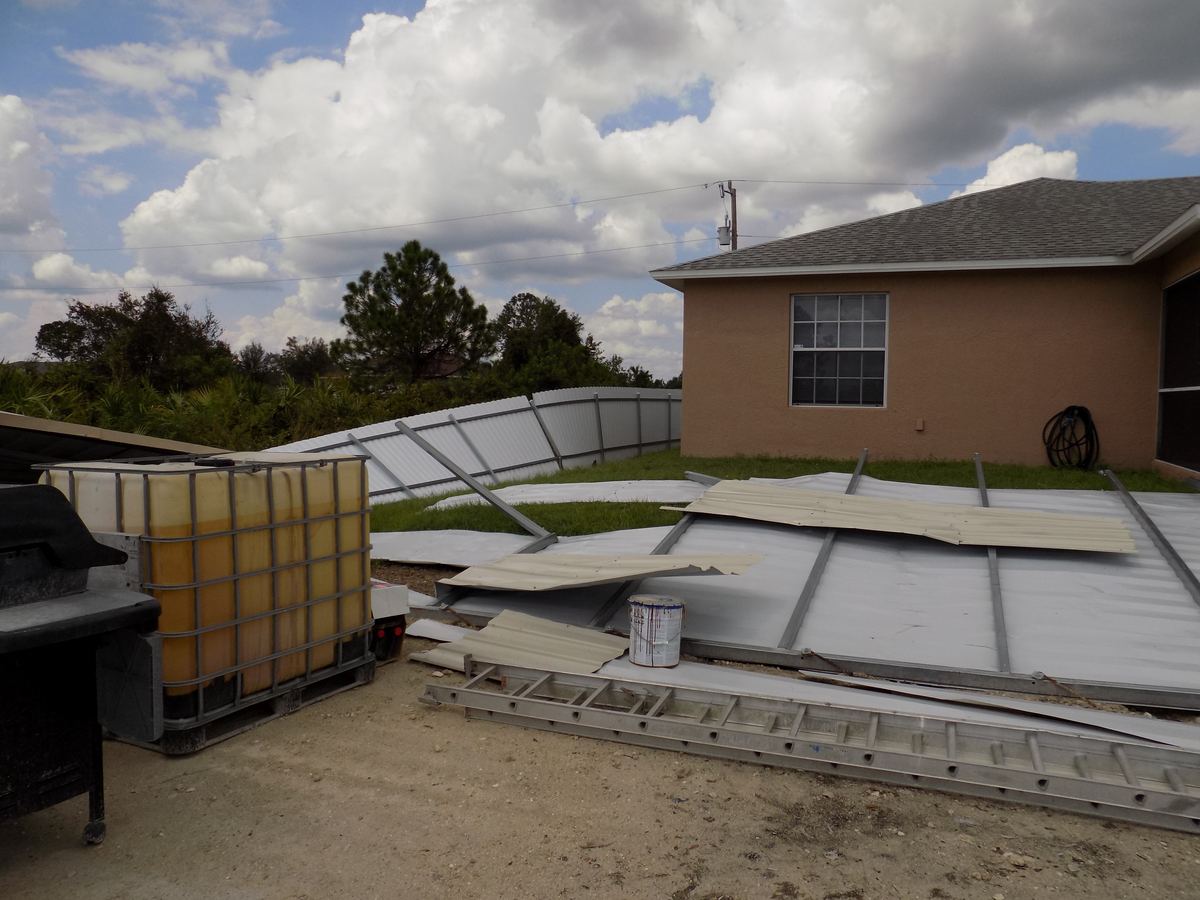
Florida landlords face hurricane and wind damage, water loss between tenancies, fire, and vandalism, often while also managing a tenant who still needs somewhere to live. Homeland represents landlords and rental property owners across Miami-Dade, Broward, Palm Beach and the rest of the state.
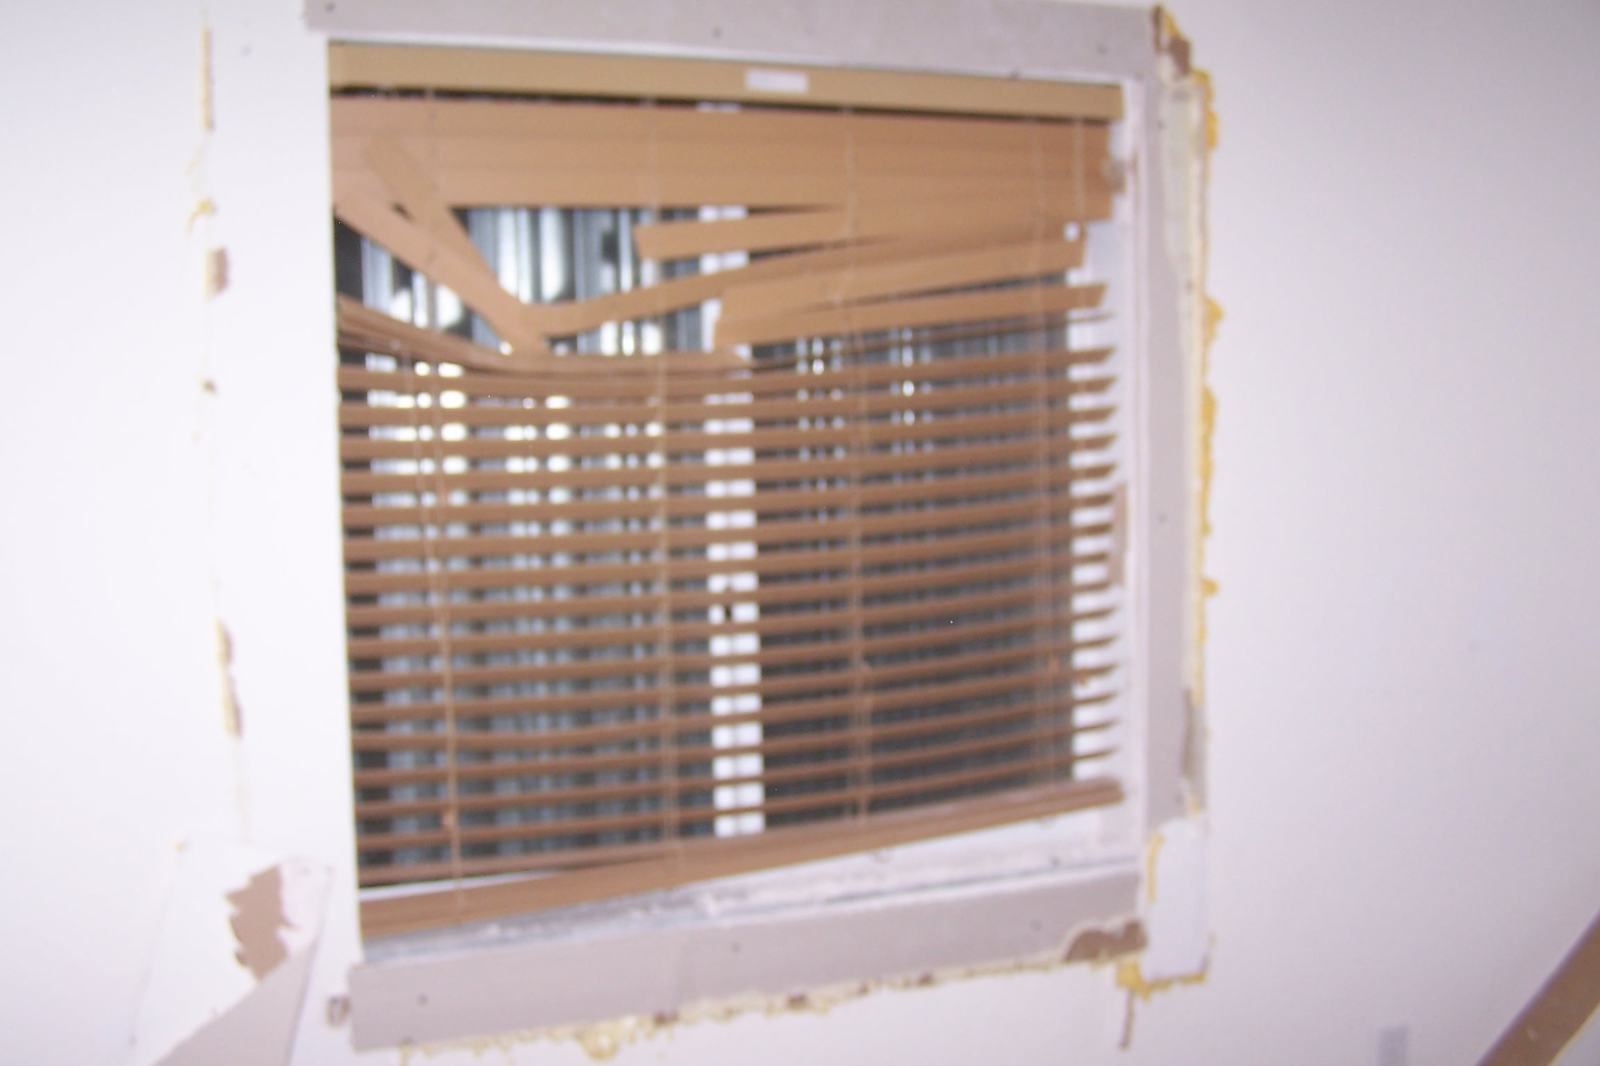
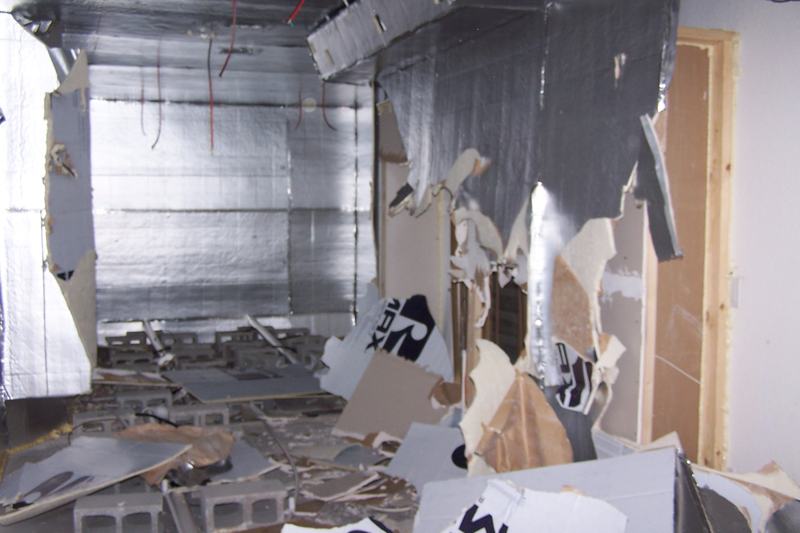
A rental in Miami after tenants ran an unauthorized grow operation. Whether the policy treats it as vandalism or excludes it turns on the policy language and the documentation.
Landlord Claims in New Jersey
New Jersey landlords deal with nor’easters, water damage, fire and tenant turnover losses across single-family rentals, multifamily buildings and shore rentals. Homeland represents New Jersey landlords with these losses.
A landlord’s policy (often called a dwelling or DP-3 policy) is built around the property as a rental business, not an owner-occupied home. That changes what matters in a claim:
Loss of rental income: Coverage for lost rent while the unit is uninhabitable after a covered loss, subject to policy limits and time periods
Tenant-caused damage: Many landlords do not realize damage caused by a tenant, not just a storm or fire, can still be a covered loss under the right circumstances
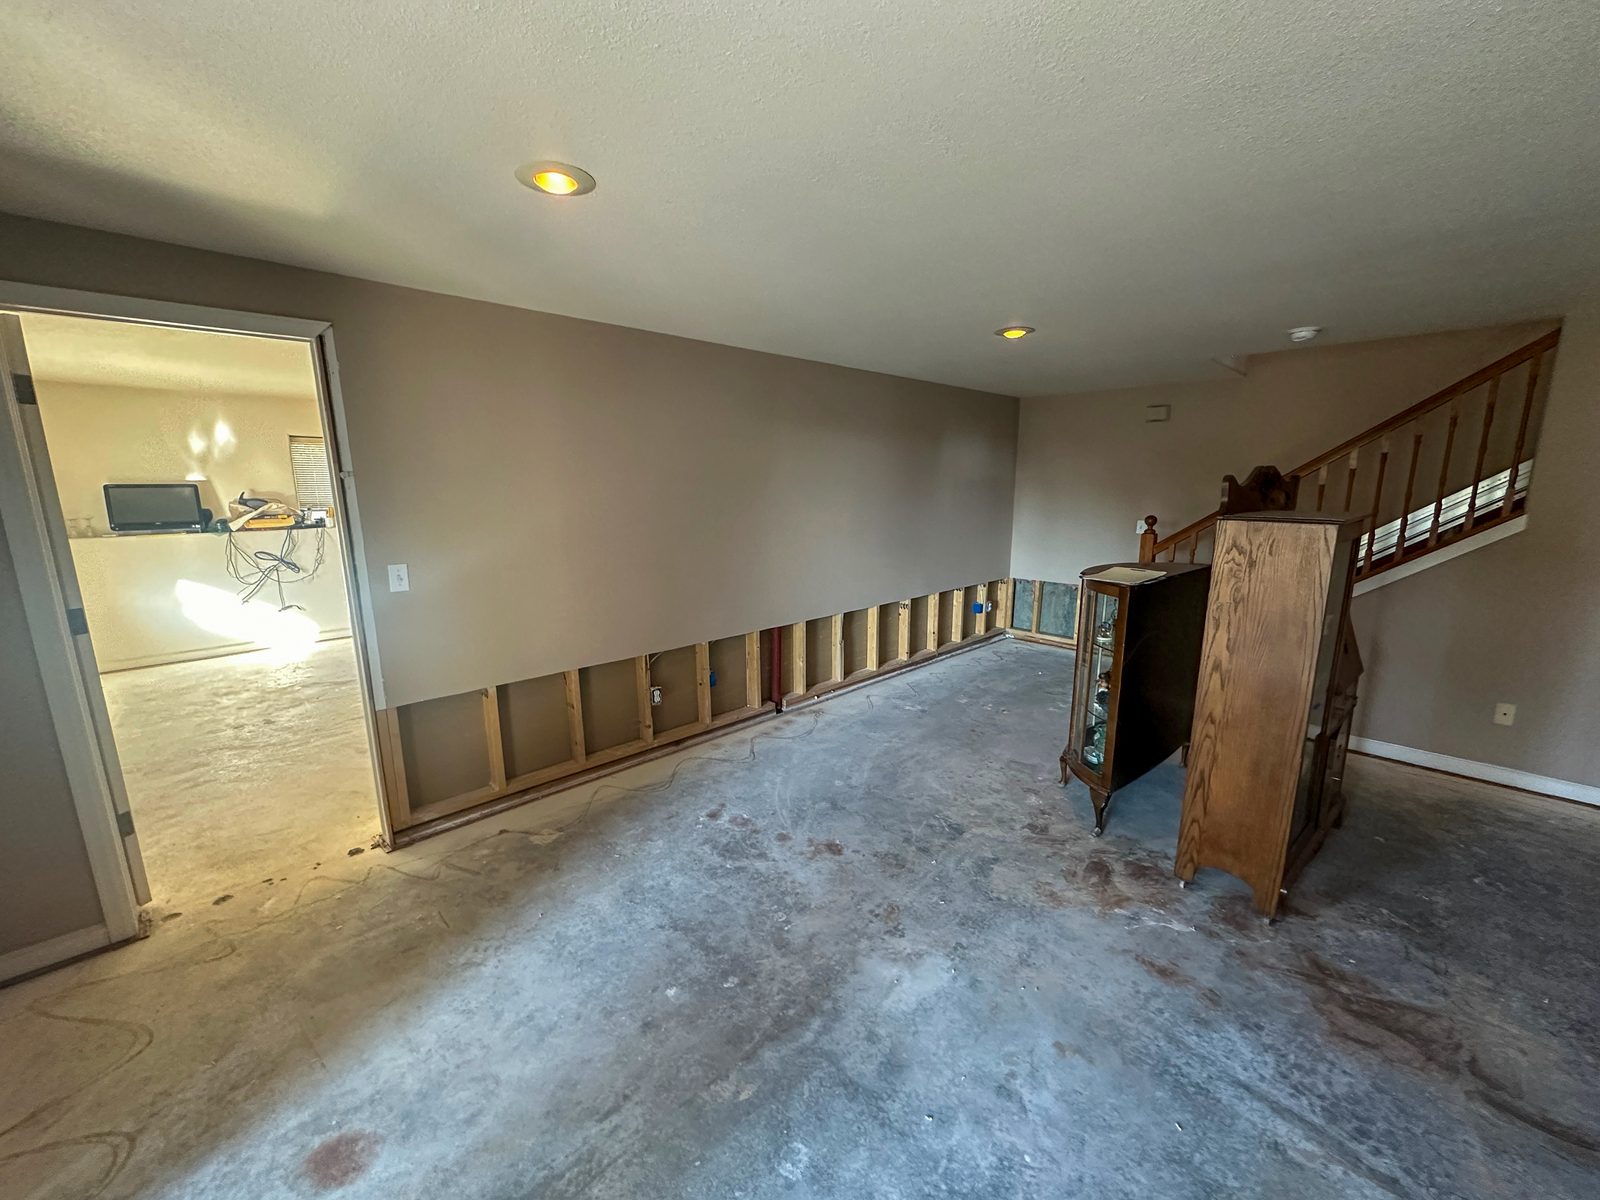
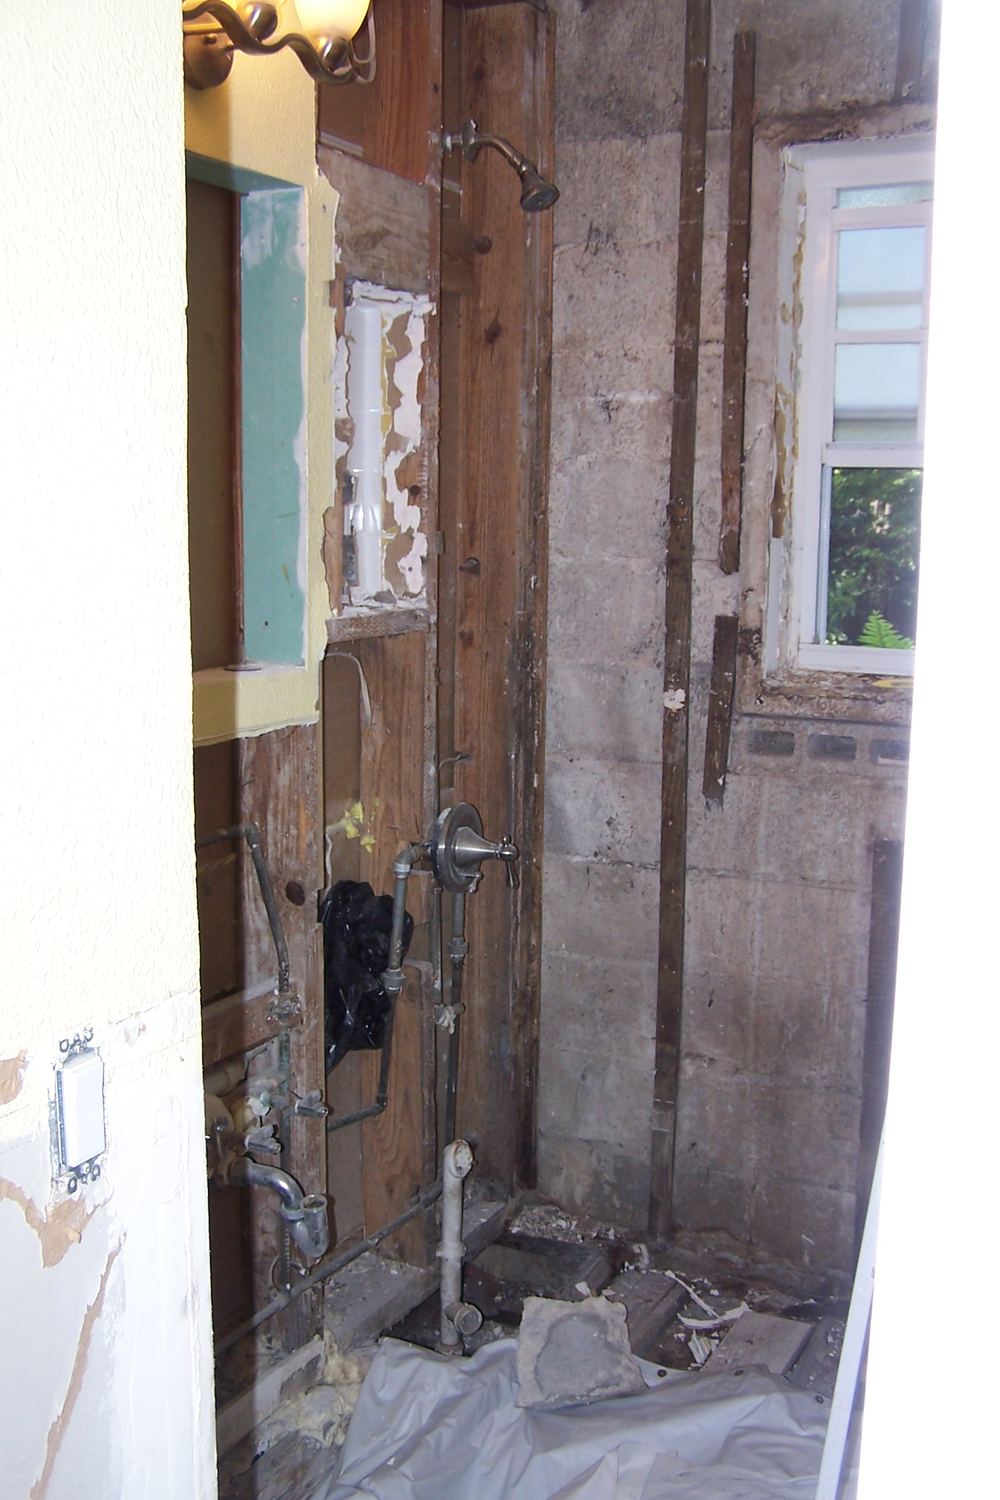
Damage between tenancies: Documenting condition at turnover protects both the claim and the security deposit accounting
Multi-unit and multifamily losses: Organizing documentation across several units in the same property
Vacant or short-term rental exposure: Some policies treat extended vacancy or short-term rental use differently
Liability exposure: Landlord policies typically include liability coverage separate from the property coverage itself
What to Do After Rental Property Damage
1
Make safety the priority: Confirm tenants are safe and the property is secure before anything else.
2
Protect the property: Tarp roofs, stop active leaks and take reasonable steps to prevent further damage, keeping receipts.
3
Document the damage and the unit: Photograph and video every affected unit separately, before cleanup or repairs begin.
4
Let Homeland notify the carrier: Call us before you speak with the insurance company. Hire us, and we’ll submit the notice of loss under your landlord or dwelling policy and handle every carrier conversation from there.
5
Communicate with tenants: Keep a written record of what you told tenants and when, especially if the unit becomes uninhabitable.
6
Track lost rent: Document the rent you are not collecting and for how long, in case your policy covers loss of rental income.
7
Gather your records: The policy, lease agreements, prior inspection reports, and turnover condition reports.
8
Speak with a public adjuster: Contact Homeland Public Adjusters before accepting a settlement or signing a release so we can review the claim and the policy.
Why Choose Homeland for a Landlord Claim
Policyholder-only representation: Homeland works for property owners, not insurance carriers.
Multi-unit documentation: We document damage across every affected unit as part of one organized claim.
Lost rent documentation: We help document loss-of-rental-income claims alongside the property damage itself.
Policy review: We review landlord and dwelling policies for applicable coverage, limits and conditions.
Carrier communication: We communicate with the insurance company and its adjusters for you.
Denied and underpaid claims: We review claims that were denied or paid less than expected.
Florida and New Jersey: We represent landlords in both states.
No Recovery, No Fee.
Rental Property Claims by the Numbers
Rental property by the numbers
32% / 36%Renter-occupied share of homes in Florida and New Jersey (Census, 2020–24)
$9,043Average claim for “all other property damage,” the category that includes vandalism and tenant damage (III, 2019–23)
$29,880Average liability claim on a homeowners-type policy, 2019–2023 (III)
45%Share of renter households with no renters insurance, so most tenant contents are uninsured (NAA via Harvard JCHS)
Florida. Florida law requires notice of an initial or reopened property claim within 1 year after the date of loss, and notice of a supplemental claim within 18 months. For hurricanes and similar weather events, the date of loss is the landfall date or the date the event is verified. Your policy may include its own requirements, so do not wait.
New Jersey. New Jersey regulations require insurers to begin an investigation within 10 working days of notice of a claim and set a 30-calendar-day period, running from receipt of a properly executed proof of loss, for first-party claims, with written explanations and updates every 45 days if more time is needed.
In the News: A Real Landlords & Rental Properties Claim
In the News. According to CBS News Miami, landlord Barclay Garnett lost half of his Fort Lauderdale duplex to fire in January 2012, allegedly set by a tenant he was in the process of evicting — leaving him, in the outlet's words, with "a big mess" to deal with. Rental property owners face risks that go beyond ordinary wear and tear: a tenant dispute, a fire, a storm, or a burst pipe can take a unit offline for months, cutting off rental income at the same time repair costs pile up. That's why a landlord policy needs to cover both the structure and the lost rent, and why documenting the full scope of damage — not just what's visible — matters when filing a claim. If you own a rental property in Florida or New Jersey and your insurer isn't covering the full cost of repairs or your lost rental income, Homeland Public Adjusters can help you build and pursue a complete claim.
Does my landlord policy cover lost rent while a unit is uninhabitable?
Many landlord and dwelling policies include loss-of-rental-income coverage for a covered loss, subject to the policy’s limits and time period. Homeland reviews your specific policy to confirm what applies and helps document the lost income.
Is damage caused by a tenant covered?
It depends on the policy and the circumstances. Some tenant-caused damage can be a covered loss, separate from security-deposit or lease-based remedies. Homeland reviews the policy and the facts to determine what may apply.
I have several units damaged in the same property. Is that one claim or several?
Usually one claim covering the property, but each unit needs to be documented separately so the full scope of damage is supported. Homeland organizes this as part of a single, coordinated claim.
Do short-term rentals get treated differently?
Yes. A home rented by the night is a business use to most carriers, and a standard landlord or homeowners policy may exclude the loss unless it carries a short-term rental endorsement. Which policy responds, what Airbnb’s and VRBO’s host guarantees actually pay, and how guest vandalism is proved are covered on our Short-Term & Vacation Rentals page.
My claim was denied or the payment seems too low. What now?
Contact Homeland before accepting a settlement or signing a release. We review denied and underpaid landlord claims against the policy and the documented damage.
Do you handle claims for single rentals as well as larger portfolios?
Yes. Homeland represents landlords with a single rental property as well as owners and managers of multifamily and multi-property portfolios.
Landlord & Rental Property Claims We Handle Across Florida & New Jersey
Homeland handles landlord and rental property claims throughout Florida and New Jersey. Wherever your rental property is in either state, call us 24/7.
Rental property losses usually begin with a specific type of property damage. Homeland Public Adjusters assists landlords with each of these covered losses.
Managing property damage, lost rent and tenants all at once is a lot to handle alone. Contact Homeland for a free review. Our team can document the damage, organize the supporting evidence, and represent you throughout the claims process.

 By Nelson Avila