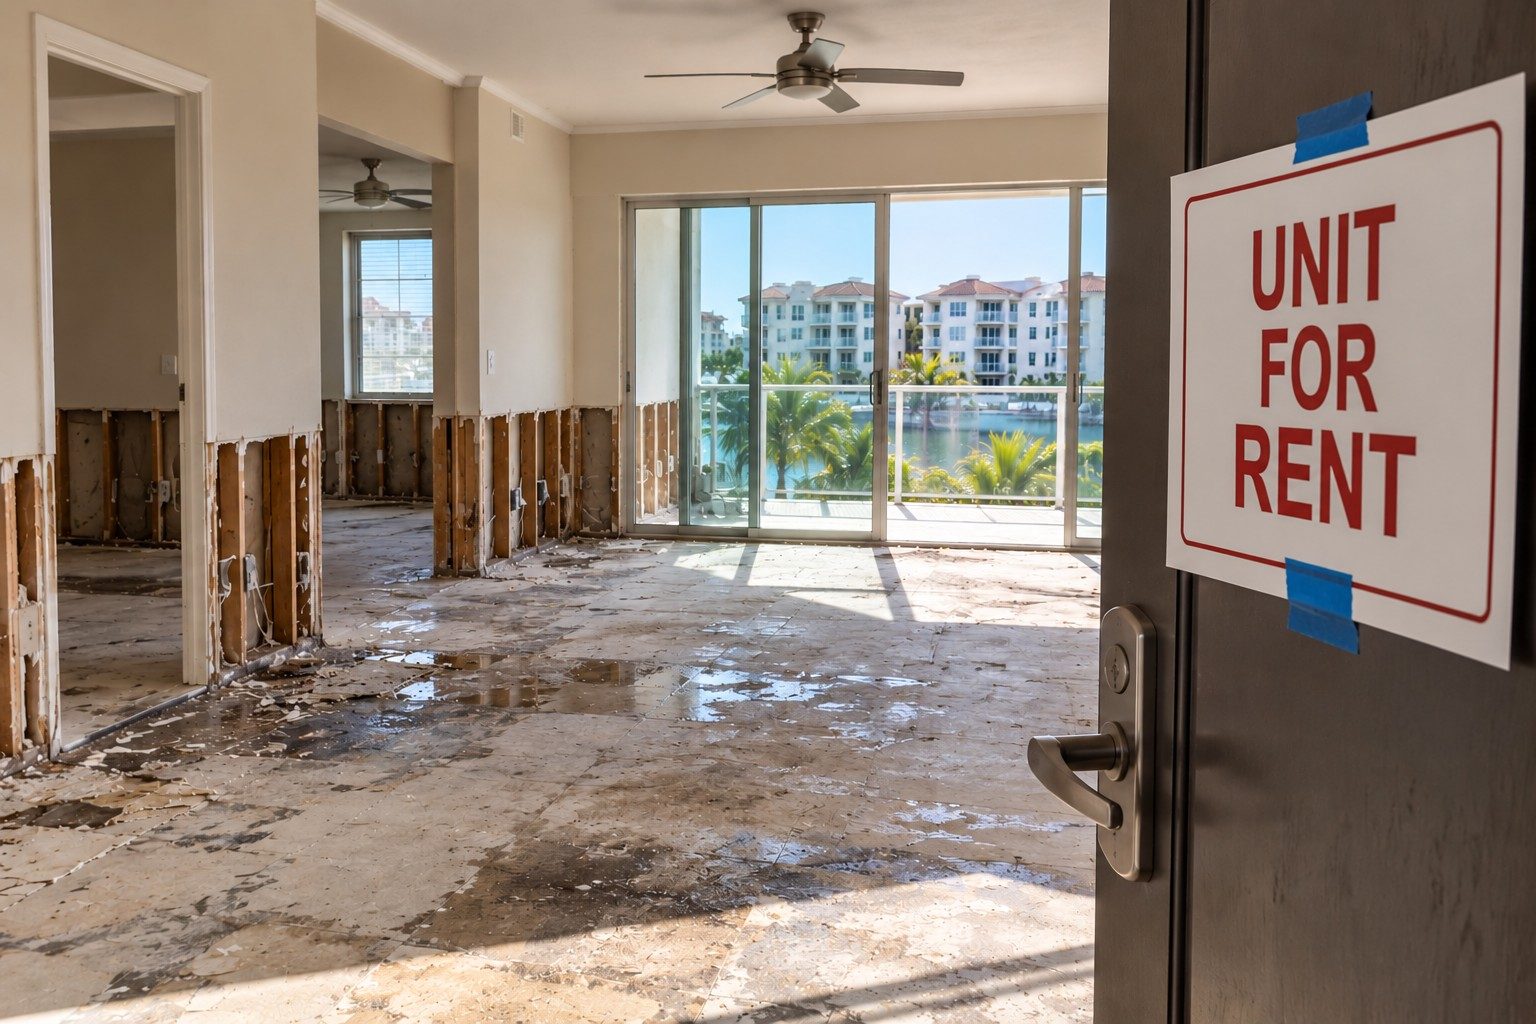
Tenant-Caused Damage vs. a Covered Loss: What Landlords Need to Know

Homeland Public Adjusters · Last reviewed: October 2026
Not all damage a tenant is involved in is treated the same way by a landlord’s policy. The distinction that matters most is sudden and accidental versus deliberate or neglected.
Have a property claim anywhere in Florida? A licensed Homeland public adjuster comes to you within hours — no need to visit an office. Call (305) 783-3777 (Florida) or (732) 517-3777 (New Jersey), 24/7.
Usually treated like any other covered loss
Short answer: Sudden, accidental damage a tenant causes, like a cooking fire or a leaking appliance, is generally handled the same as if the landlord had caused it. The claims insurers push back on are damage they call intentional, damage blamed on neglect the landlord should have caught, and damage during an eviction or move-out.
A tenant’s cooking fire, a tenant’s appliance that leaks and floods a unit, an accidental break that causes water or fire damage. These are typically handled the same as if the landlord had caused them — the fact that a tenant was present isn’t, by itself, a reason to deny the claim.
Where it gets contested
Damage the carrier characterizes as intentional, damage attributed to neglect the landlord should have caught, or damage during an eviction or move-out.
What helps either way: move-in and move-out condition documentation, a record of any maintenance requests and how they were handled, and photos from routine inspections if you do them. If a tenant was involved in a loss and you’re not sure how the carrier will treat it, call Homeland before you report the claim — how it’s described matters from the first conversation.
Tenant-caused damage claims are a regular part of Homeland's rental-property work in Homestead, Kissimmee and Trenton.
Frequently asked questions
Does landlord insurance cover damage caused by a tenant?
When is tenant damage likely to be disputed by the insurer?
Can I recover from the tenant and also file my own insurance claim?
This article is for general information only and is not legal or insurance advice. Every policy and every claim is different — call Homeland. We review your policy language with you at no cost.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewThis topic often comes up alongside Landlords: Documenting Damage and Lost Rent After a Loss. If your situation involves this kind of loss, see our Landlords & Rental Properties page for how Homeland can help with the claim itself.