Barn, Stable and Outbuilding Damage: What Your Policy Actually Covers

Homeland Public Adjusters · Last reviewed: October 2026
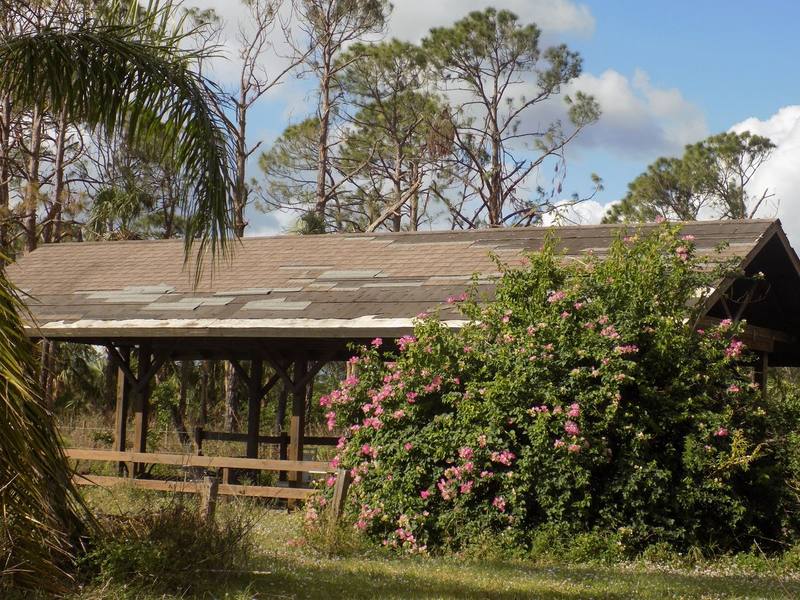
On a working farm or ranch, the farmhouse is rarely the only structure with real value at risk. Barns, equipment sheds, horse stables and hay storage buildings each carry their own exposure, and they’re not always covered the same way the main residence is. Understanding how your policy treats these “other structures” matters most before a storm, when it’s still possible to fix a gap.
Have a property claim anywhere in Florida? A licensed Homeland public adjuster comes to you within hours — no need to visit an office. Call (305) 783-3777 (Florida) or (732) 517-3777 (New Jersey), 24/7.
Scheduled versus blanket coverage
Short answer: Barns, stables and sheds are often covered differently from the farmhouse: some farm policies list each outbuilding with its own limit, others use one blanket limit for all of them. An outdated list of structures, or a contents limit nobody checked, is one of the most common reasons an outbuilding claim comes in short.
Some farm and ranch policies list each outbuilding individually, with its own coverage limit. Others use a blanket limit that applies across all secondary structures combined. A scheduled policy is more precise but requires updating every time a new structure goes up or an old one is renovated or removed; a blanket policy is more flexible but can leave a single large loss underinsured if the combined limit isn’t enough. Either way, an outdated list of structures is one of the most common reasons an outbuilding claim comes in under what it costs to rebuild.
Contents matter as much as the structure
A barn or stable often holds more insured value in what’s inside it — tack, feed, tools, equipment, sometimes livestock housed there — than in the structure itself. Farm policies frequently separate coverage for the building from coverage for its contents, and the contents limit is easy to overlook until a loss forces a count of everything that was inside.
After a loss
Open-sided barns and equipment structures are especially vulnerable to wind, and storm damage can range from a lifted roof panel to a total collapse. Document the damage to the structure and everything inside it before cleanup or repairs begin, and get the building’s replacement cost — not just its depreciated value — into the claim from the start.
Homeland handles farm and outbuilding claims in Florida's agricultural areas, including Immokalee, Belle Glade and Ocala.
Frequently asked questions
Are barns and outbuildings covered the same way as the farmhouse?
What is the difference between scheduled and blanket outbuilding coverage?
What should I document after storm damage to a barn or stable?
This article is for general information only and is not legal or insurance advice. Every policy and every claim is different — call Homeland. We review your policy language with you at no cost.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
- Plane or Odd Impact Hit Your House? Your Policy Covers It
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewThis topic often comes up alongside Open Land, Open Exposure: Wind and Tornado Risk on the Farm. If your situation involves this kind of loss, see our Agricultural Properties page for how Homeland can help with the claim itself.