Plane or Odd Impact Hit Your House? Your Policy Covers It

Homeland Public Adjusters · Last reviewed: October 2026
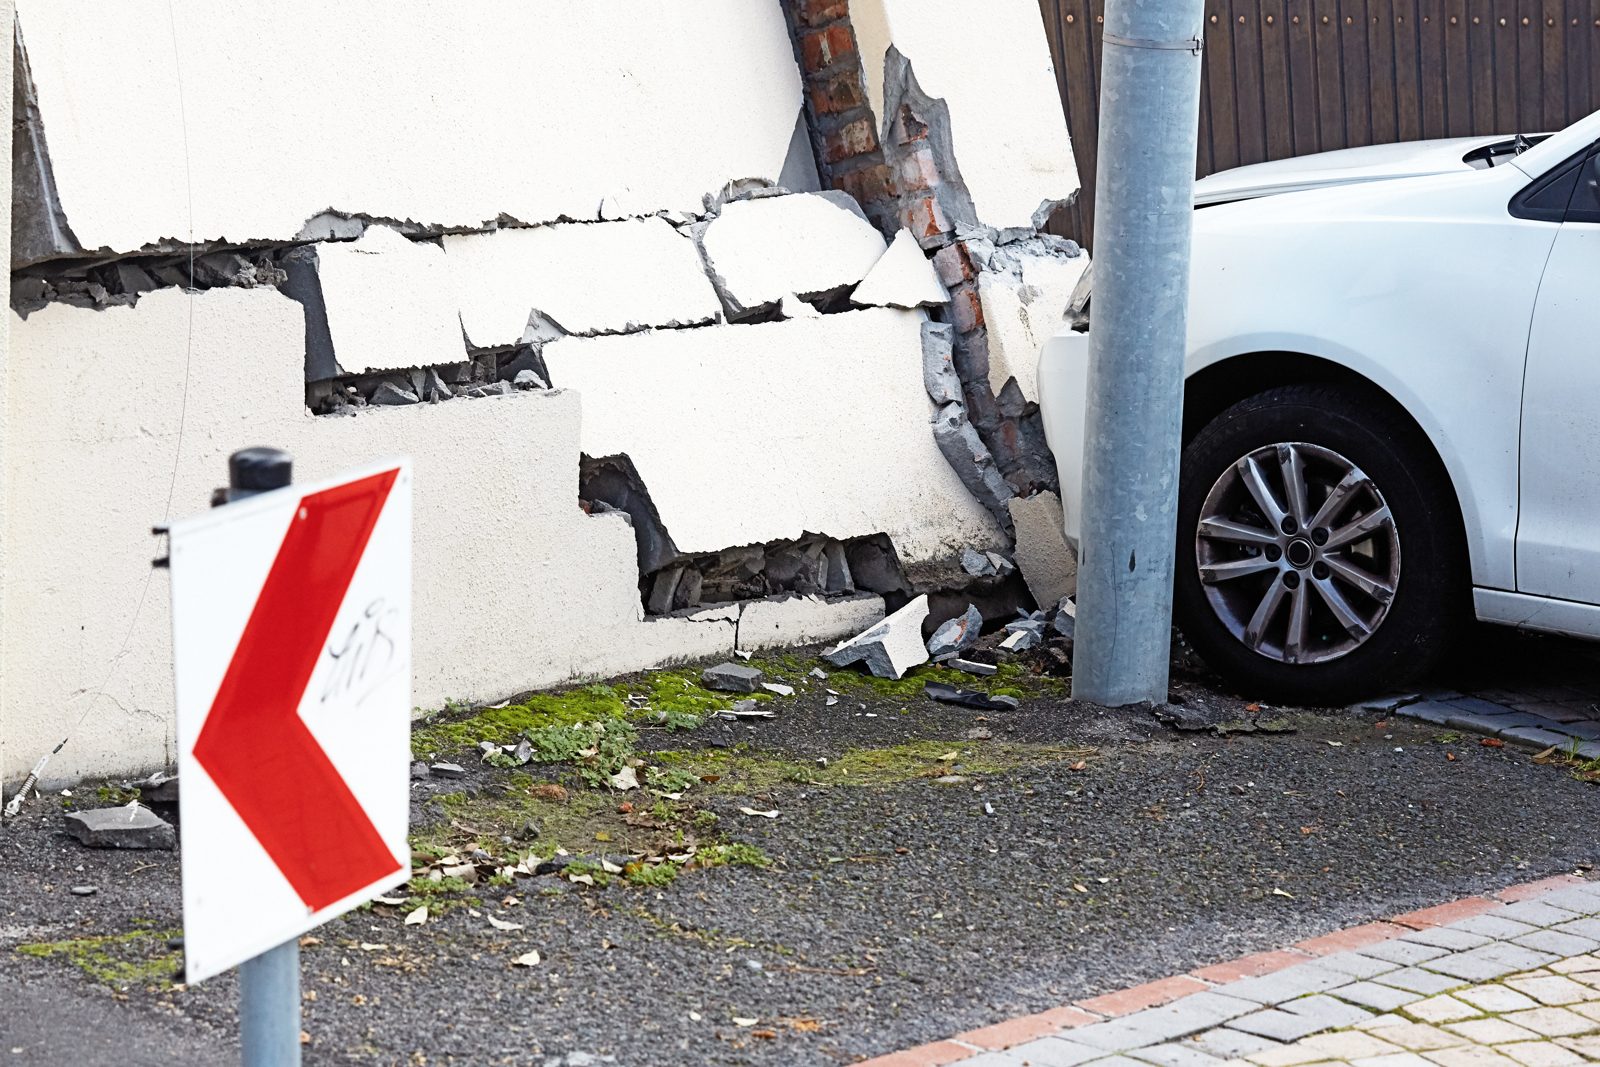
A car leaving the road and striking a house, a small plane making an emergency landing short of a runway, a delivery truck backing into a garage — these losses are jarring, structural, and often expensive. Your own property policy covers vehicle and aircraft impact, and Homeland handles that claim for you. If you have no policy of your own, Homeland helps you recover from the at-fault party’s insurance in Florida.
Have a property claim anywhere in Florida? A licensed Homeland public adjuster comes to you within hours — no need to visit an office. Call (305) 783-3777 (Florida) or (732) 517-3777 (New Jersey), 24/7.
Your own policy covers it, and Homeland handles the claim
Short answer: Your own homeowners or commercial property policy covers vehicle and aircraft impact as a covered peril, regardless of who was driving or flying, and Homeland handles that claim for you; your insurer can pursue the responsible party afterward. No policy of your own? In Florida, Homeland recovers from the driver’s or operator’s liability insurance, supported by the police or incident report.
Most homeowners and commercial property policies cover vehicle and aircraft impact as a named or covered peril, regardless of who was driving or flying. Call Homeland first; a claim on your own policy is typically the fastest way to get repairs started, since your policy doesn’t require establishing fault the way a liability claim against a third party does. Your deductible applies, but your insurer can then pursue the responsible driver or operator’s insurance separately through subrogation.
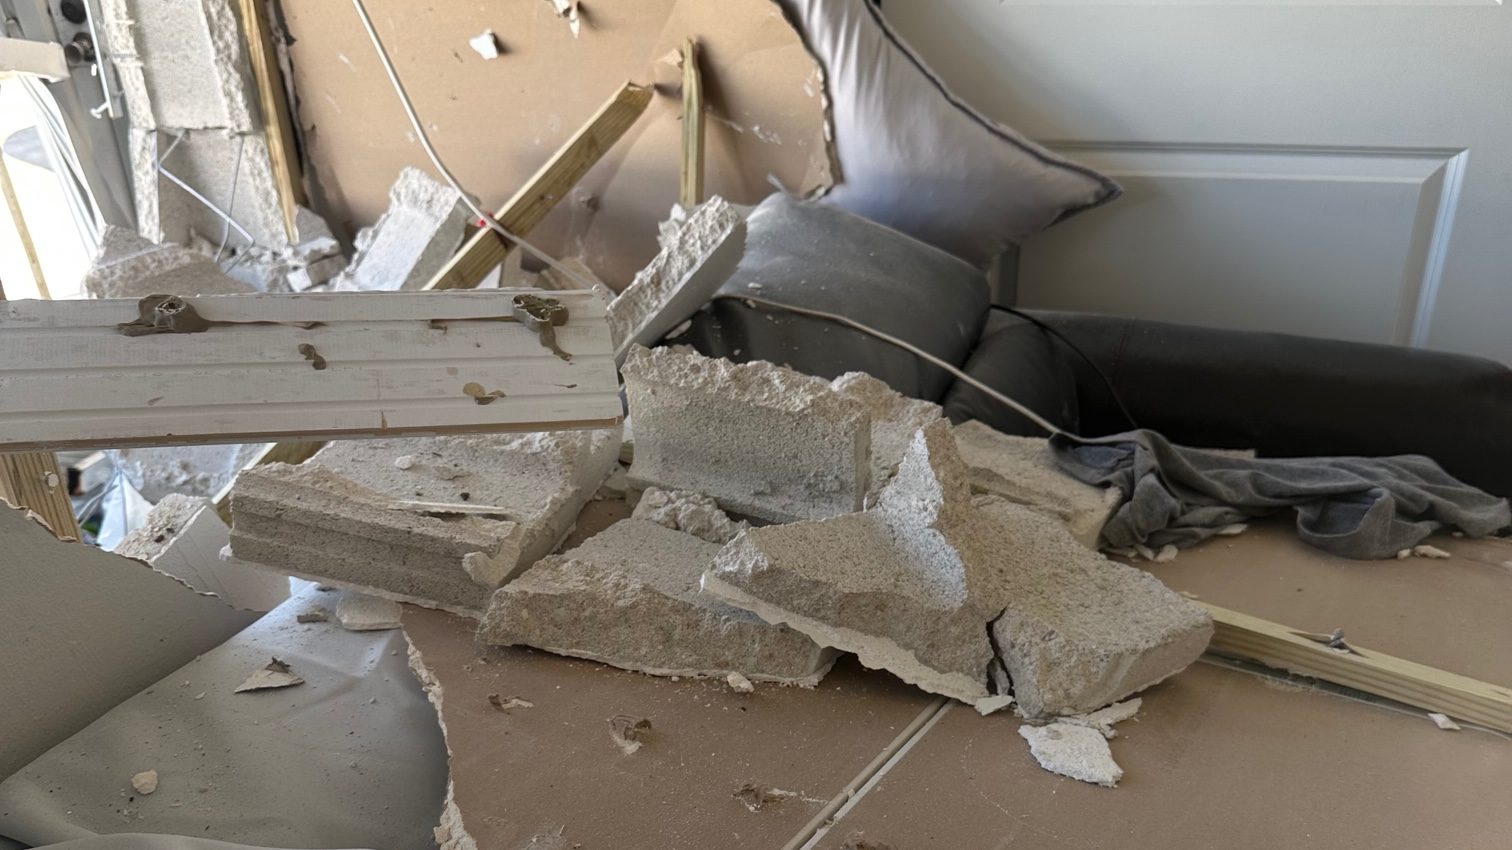
When the third party's liability coverage matters more
If you don’t have adequate property coverage — or none at all — the driver’s auto liability policy, or an aircraft operator’s liability coverage, may be the only path to recovering the cost of repairs. This is also the better route when damage exceeds your own policy limits, since a driver or operator’s liability coverage can sometimes provide a larger pool to draw from. Filing against a third party’s liability coverage generally requires establishing that they were at fault, which is usually documented through a police or incident report.
No policy of your own? In Florida, Homeland recovers from the at-fault party
If you’re underinsured or uninsured in Florida and the damage was clearly caused by someone else’s vehicle or aircraft, Homeland can handle the property damage claim against that party’s liability coverage: third-party damage claims. In New Jersey, Homeland represents you on a claim under your own policy. Documenting the loss thoroughly from the start — the same way you would for any insured claim — puts you in the strongest position regardless of which coverage ultimately pays.
Vehicle-strike claims come up along busy corridors in Hialeah and Pembroke Pines; Homeland handles them under the homeowner's own policy and, in Florida, against the driver's carrier.
Frequently asked questions
Does homeowners insurance cover a car hitting my house?
Should I file with my own insurance or the driver’s insurance?
What documents help after a vehicle hits my property?
What should I do if a car crashes into my house?
This article is for general information only and is not legal or insurance advice. Every policy and every claim is different — call Homeland. We review your policy language with you at no cost.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewThis topic often comes up alongside Damaged by Someone Else, With No Coverage of Your Own?. If your situation involves this kind of loss, see our Third Party Uninsured Damage Claims page for how Homeland can help with the claim itself.