Seawalls, Garages, Roofs and Elevator Pits: Wear and Tear vs. a Covered Loss

Licensed public adjusters serving Florida & New Jersey
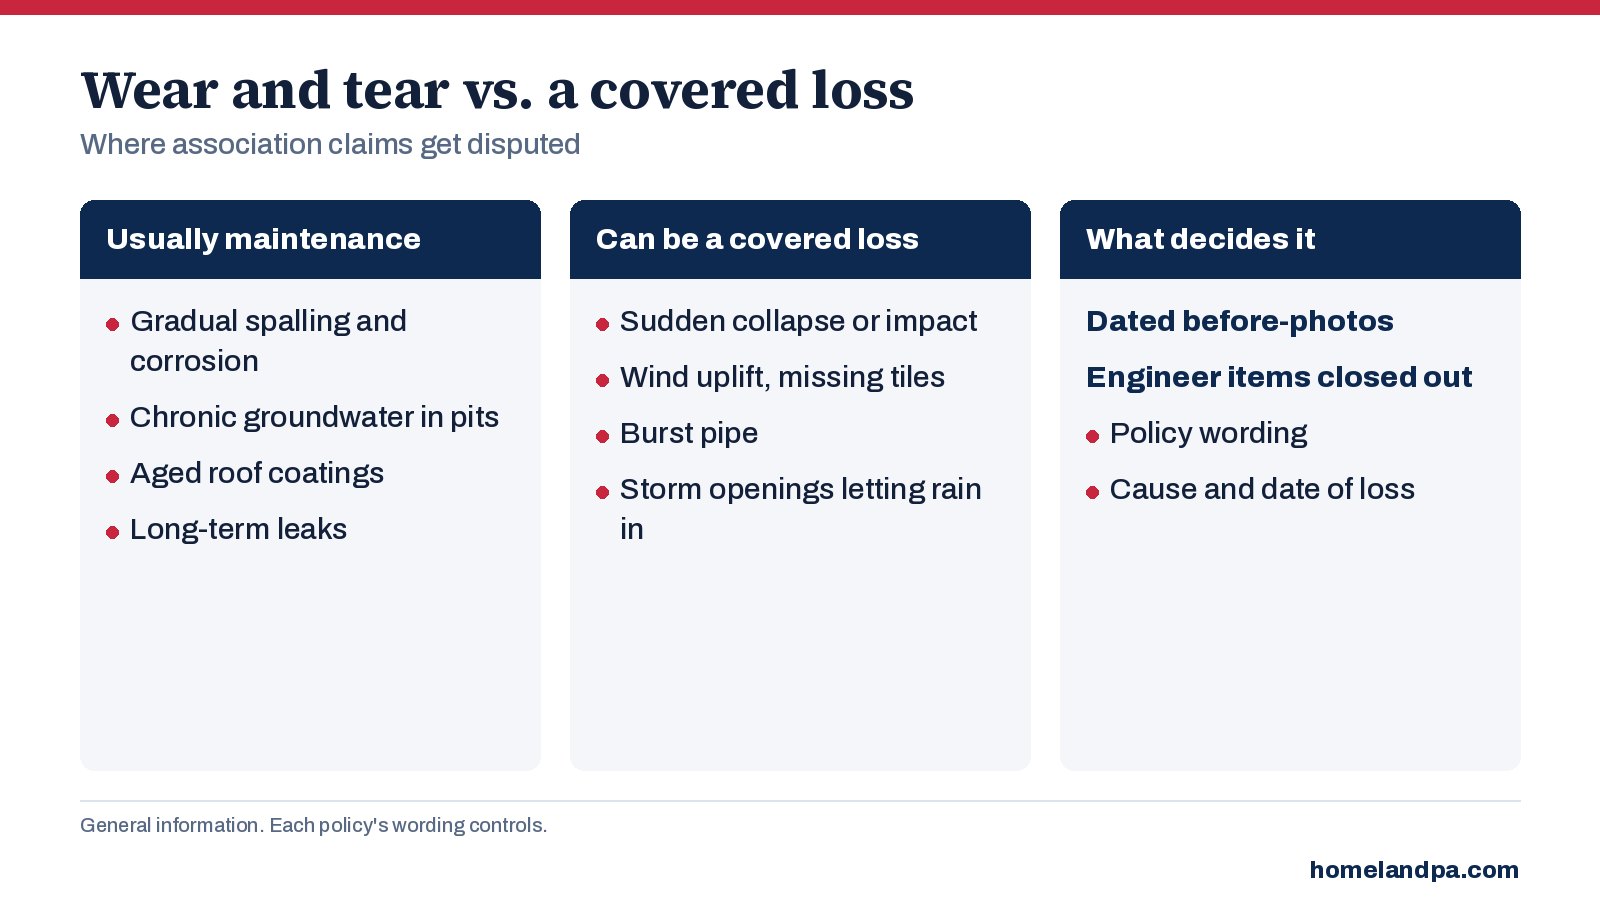
Short answer: property policies pay for sudden, accidental damage from a covered peril, and generally exclude wear and tear, deterioration and lack of maintenance. Seawalls, garage ceilings, elevator pits, spray-foam and tile roofs and mold are where those two ideas collide on association claims. What decides it is usually the evidence: what the component looked like before, and what changed on the date of loss.
Where the disputes happen
- Seawalls and retaining walls: property forms often list seawalls, bulkheads, piers and docks as property not covered unless added by endorsement; storm surge and flood are separate from wind. Read the policy before the storm.
- Garage ceilings and parking structures: spalling and corrosion are deterioration; a sudden collapse, impact or burst pipe is a loss.
- Elevator pits: chronic groundwater is maintenance; storm flooding is a flood claim; a sudden equipment failure may be neither.
- Spray-foam and tile roofs: age and coating wear versus wind uplift, missing or cracked tiles and openings that let rain in.
- Mold: usually covered only as part of a covered water loss, and often sublimited.
How to win the argument before it starts
- Keep dated photos of each component every year and after every storm.
- Act on engineer recommendations and keep close-out letters; open, unrepaired items become the insurer’s argument (see milestone inspections).
- In Florida condos, the association can charge an owner for uninsured damage caused by the owner’s negligence or failure to comply with the declaration (§718.111(11)(j)), so document unit-originated causes too.
- Read the wear-and-tear language: wear and tear exclusion and ensuing loss.
The free Adjuster Advantage for Associations app stores dated condition photos by building component. As a Florida-certified residential contractor and licensed public adjuster, Nelson Avila reviews both sides: how the component was built and how the policy reads.
Frequently asked questions
Does the master policy cover seawall damage?
Is garage ceiling spalling covered?
Sources: Fla. Stat. §718.111(11).
This guide is general information for association boards and managers, current as of October 2026. It is not legal advice. Your governing documents, your policies and your association’s attorney control.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim Review