Loss Assessment Coverage: How the Master Deductible Reaches Unit Owners, and What HO-6 Pays

Licensed public adjusters serving Florida & New Jersey
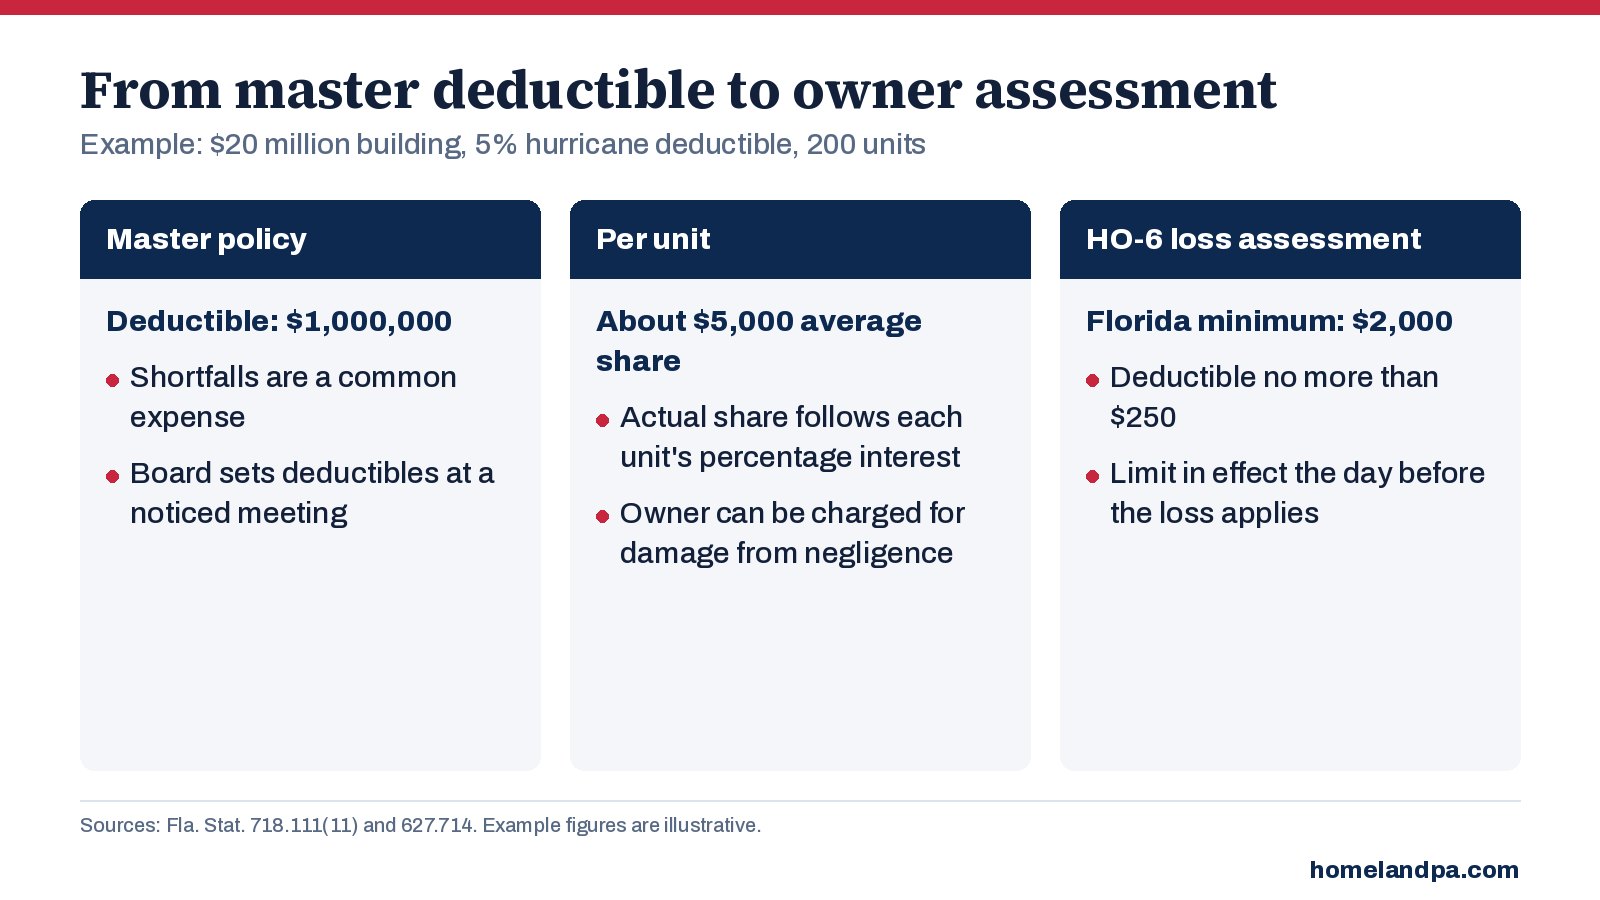
Short answer: when the master policy pays less than the cost of repairs because of a deductible, a sublimit or a gap, Florida law makes the shortfall a common expense, so it usually becomes an assessment to every owner. Loss assessment coverage on a unit owner’s HO-6 can pay that owner’s share when the loss is a type the HO-6 covers. In Florida, every unit owner policy issued or renewed since July 1, 2010 must include at least $2,000 of loss assessment coverage, with a deductible of no more than $250 (§627.714).
How the deductible reaches owners
- “All property insurance deductibles and other damages in excess of property insurance coverage” are generally a common expense (§718.111(11)(j)).
- The owner can be charged for uninsured damage caused by intentional conduct, negligence, or failure to comply with the declaration or rules, by the owner or the owner’s family, tenants or guests.
- The board sets deductibles at a board meeting, based on industry standards and the funds or assessment authority available (§718.111(11)(c)).
- Example: a 5% hurricane deductible on a $20 million building is $1,000,000; spread over 200 units by percentage interest, a typical share is about $5,000, far above the $2,000 minimum.
What loss assessment coverage pays, and what it does not
- It pays the owner’s share of an assessment from a covered type of loss. An assessment for a roof replacement due to age, or for a SIRS funding shortfall, is not a loss.
- The limit that applies is the one in effect one day before the loss; raising it after a storm is forecast does not help that storm (§627.714(2)).
- One limit per loss, however many assessments the board levies for it.
- In New Jersey, check the HO-6 declarations page for the loss assessment limit and compare it with the owner’s share of the deductible.
What boards and managers should tell owners every year
- The master policy’s deductibles, including the hurricane deductible in dollars.
- Each unit’s estimated share, from its percentage interest.
- That owners should check the loss assessment limit on their HO-6 declarations page and consider raising it to their share. Section 718.111(11) does not give the board power to require it; any requirement would come from the declaration, so ask the association’s attorney.
- What the master policy insures and what the owner must insure (floor, wall and ceiling coverings, fixtures, appliances, cabinets and personal property; see Florida Condo Association Insurance Requirements).
After a loss
The size of the assessment depends on the size of the master policy claim. Every dollar the association recovers on the claim is a dollar owners are not assessed. Read Special Assessments After an Association Claim. Owners with a loss assessment claim need the board’s resolution and the master policy claim file; unit-level claims have their own rules.
Frequently asked questions
What is loss assessment coverage?
How much loss assessment coverage does Florida require?
Does loss assessment coverage pay a special assessment for a new roof?
Can a Florida condo board require owners to carry loss assessment coverage?
Sources: Fla. Stat. §627.714; Fla. Stat. §718.111(11).
This guide is general information for association boards and managers, current as of October 2026. It is not legal advice. Your governing documents, your policies and your association’s attorney control. Policy wording varies; each owner should read their own HO-6.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim Review