Condo Association Insurance Renewal: What Drives the Premium and What a Board Can Control

Licensed public adjusters serving Florida & New Jersey
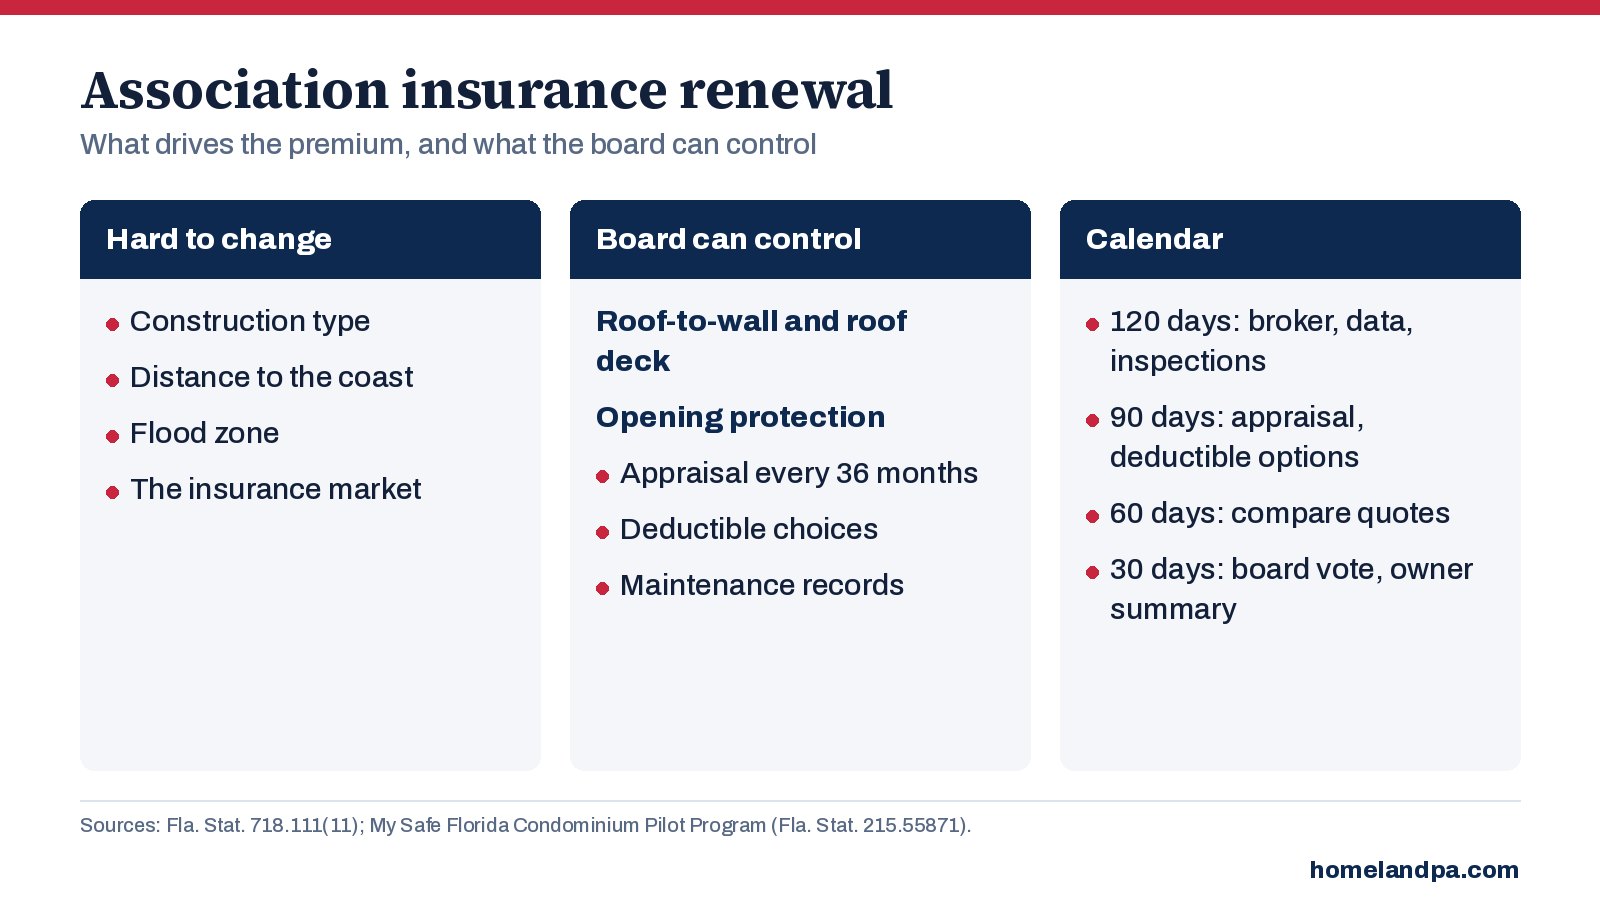
Short answer: for many Florida associations, insurance is the biggest line in the budget. The premium is driven mostly by things the board can’t change quickly (construction type, distance to the coast, flood zone, the market) and some it can: the building’s wind-resistance features, the replacement cost appraisal, deductible choices, documented maintenance and claim history. The board’s job is to start early, document the building, and understand what it is buying.
What the law requires the board to insure
- Owner-controlled associations must use their best efforts to obtain and maintain adequate property insurance (§718.111(11)(d)).
- Coverage is based on replacement cost, set by an independent insurance appraisal or an update of one at least every 36 months (§718.111(11)(a)).
- Deductibles are set by the board at a properly noticed board meeting and must be consistent with industry standards and prevailing practice for similar communities (§718.111(11)(c)).
- Florida HOAs under chapter 720 have no comparable property insurance mandate; the declaration controls.
What the board can control
- Wind-resistance features. Roof-to-wall connections, roof deck attachment, a secondary water barrier and opening protection are what underwriters credit. Document them with a current inspection.
- The My Safe Florida Condominium Pilot Program. For condo buildings three or more stories within 15 miles of the coast, the state program offers a free inspection with estimated insurance savings, and matching grants ($2 from the state for every $1 from the association, up to $175,000) for opening protection and roof work, when funded. Ask Florida DFS about current availability.
- The appraisal. An outdated replacement cost leaves the building underinsured; an inflated one raises the premium.
- Deductibles. A higher hurricane deductible lowers the premium but becomes owners’ assessment after a storm. Decide it with the numbers in front of the board (see Loss Assessment Coverage).
- Maintenance records. Milestone reports, SIRS, roof inspections and close-out letters show a well-kept building.
A renewal calendar that works
- 120+ days out: meet the broker, update the building data, schedule inspections, gather loss history.
- 90 days: confirm the replacement cost appraisal is current (36 months) and decide deductible options to quote.
- 60 days: review quotes side by side: limits, deductibles, sublimits, exclusions and wind/flood structure, not just price.
- 30 days: board decision at a noticed meeting; send owners a one-page summary of what changed and why (see explaining a dues increase).
Most boards do better with one broker they trust than with several brokers approaching the same insurers. The free Adjuster Advantage for Associations app keeps the renewal packet, inspections and prior quotes in one place.
Frequently asked questions
How often must a Florida condo association update its insurance appraisal?
Who decides the master policy deductible?
What is the My Safe Florida Condominium Pilot Program?
Sources: Fla. Stat. §718.111(11); Fla. Stat. ch. 720; Fla. Stat. §215.55871; Florida DFS, My Safe Florida Condominium Pilot Program.
This guide is general information for association boards and managers, current as of October 2026. It is not legal advice. Your governing documents, your policies and your association’s attorney control.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim Review