Claim Closed Without Payment? How to Reopen It

Homeland Public Adjusters · Last reviewed: October 2026
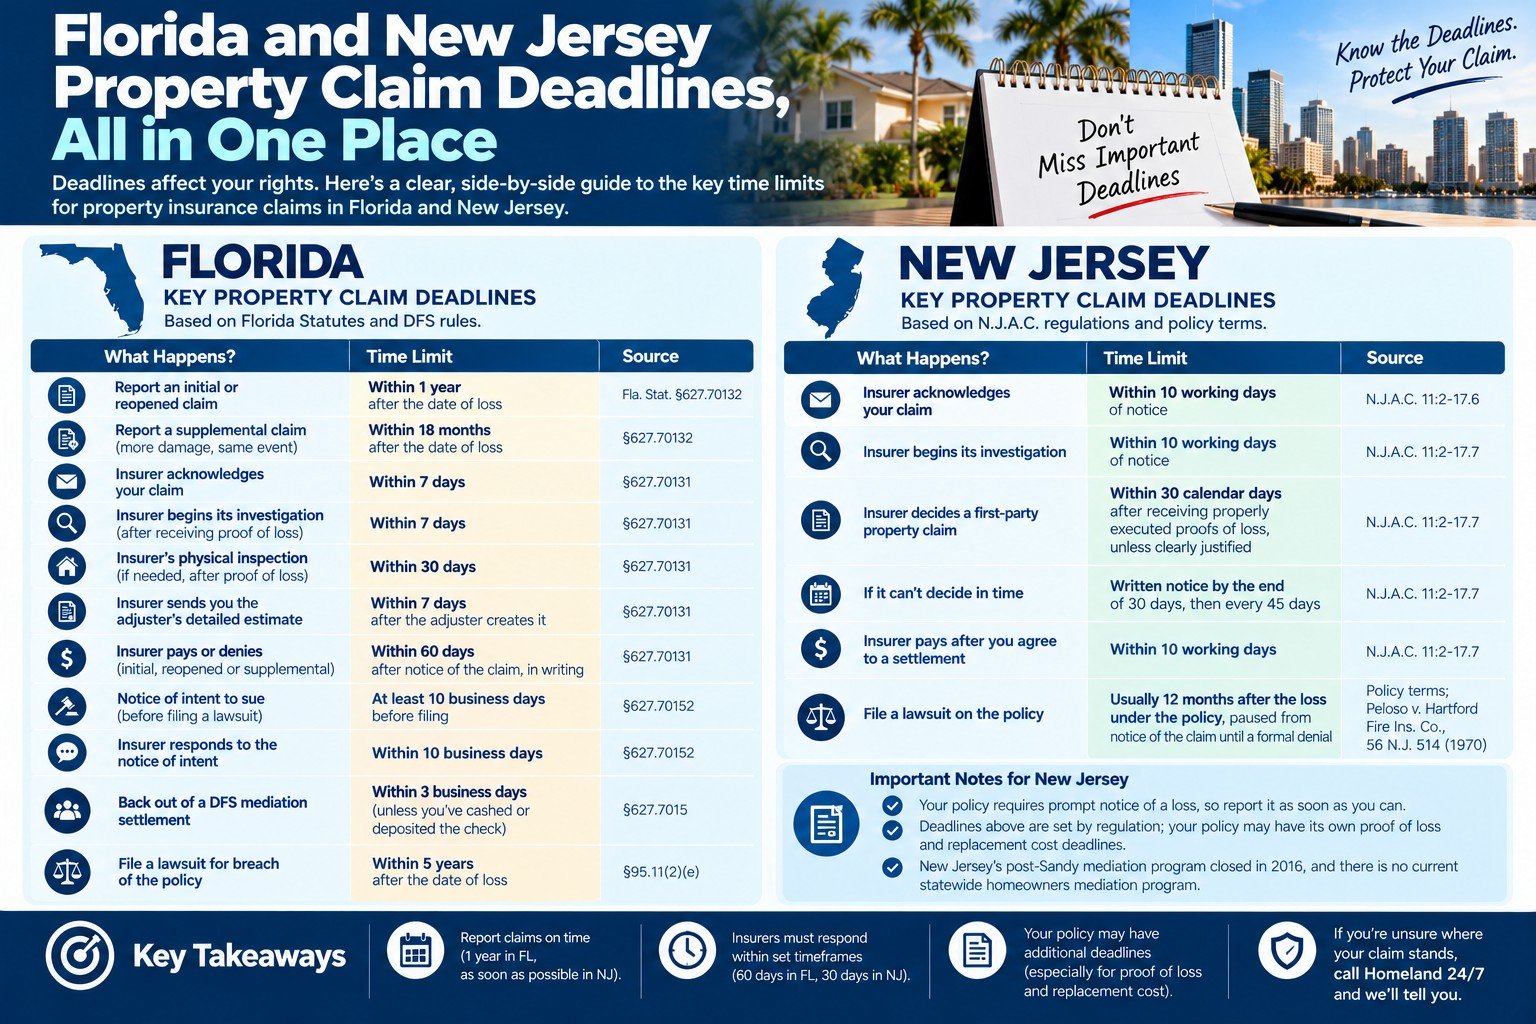
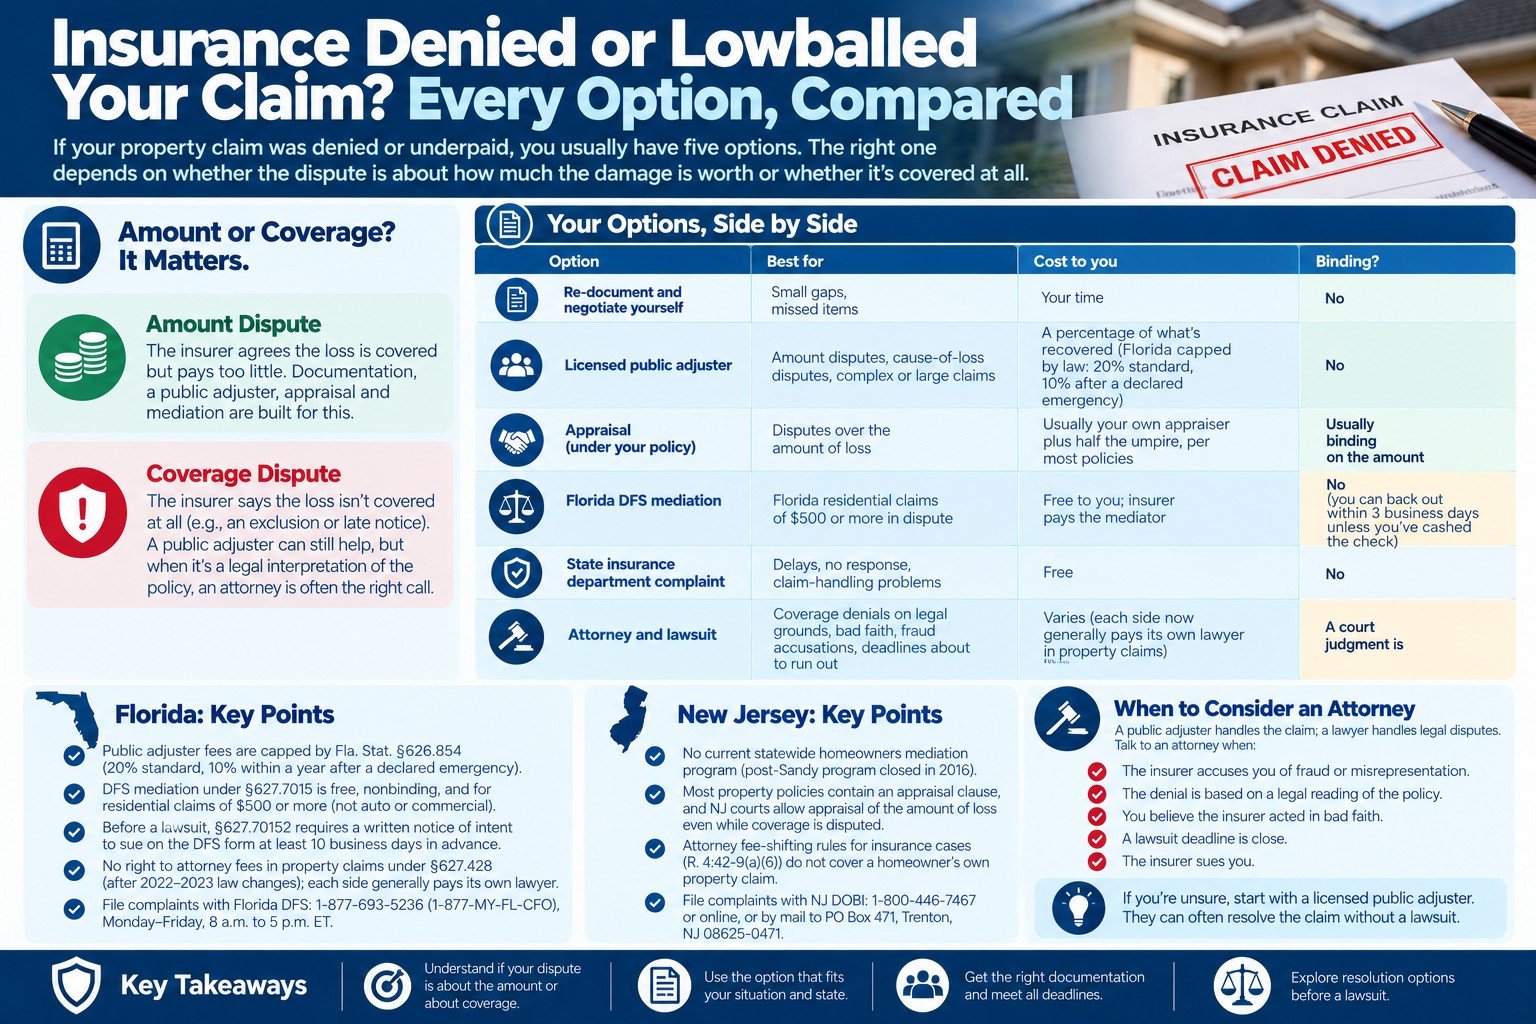
Short answer: A claim “closed without payment” is often not the end. Insurers close claims when the damage seemed to fall below the deductible, the inspection found nothing covered, or information was missing. In Florida you can reopen a claim within 1 year of the date of loss, or file a supplemental claim for additional damage within 18 months.
Why claims get closed without payment
Below the deductible. The insurer's estimate came in under your deductible, often because damage was missed or under-scoped.
No covered damage found. The inspector attributed the damage to wear and tear or another exclusion.
Missing information. Requested documents, photos or a proof of loss weren't provided.
Damage that appeared later. Water damage, mold or roof leaks can show up weeks after a storm.
Reopened vs. supplemental claims in Florida
Florida's Fla. Stat. §627.70132 treats these separately: a reopened claim is a previously closed claim that you ask the insurer to reopen, and a supplemental claim is a claim for additional loss from the same event the insurer already adjusted. Under the current statute, notice of an initial or reopened claim must be given within 1 year after the date of loss, and a supplemental claim within 18 months. For hurricanes and windstorms, the date of loss is tied to the storm itself.
Once you reopen or supplement, the insurer must pay or deny within 60 days after notice, under §627.70131.
| Situation | Florida path | Notice deadline |
|---|---|---|
| Claim closed and you disagree with the result | Reopened claim | 1 year from date of loss |
| More damage found from the same event | Supplemental claim | 18 months from date of loss |
| A new, separate event caused new damage | New claim | 1 year from that date of loss |
New Jersey
New Jersey doesn't use Florida's reopened and supplemental claim deadlines; in New Jersey, your policy terms and case law control. Most New Jersey property policies require a lawsuit within 12 months after the loss, but New Jersey's Supreme Court held in Peloso v. Hartford Fire Insurance Co. (1970) that this period is paused from when you give notice of the claim until the insurer formally denies it. The clock can start running again at a formal denial, so don't wait.
How to reopen a claim effectively
Get the file. Ask for the closing letter, the adjuster's estimate and photos. In Florida, the insurer must send you the adjuster's detailed estimate within 7 days after the adjuster creates it (§627.70131).
Document what was missed with dated photos, moisture readings, a contractor's or independent estimate, and weather data for the date of loss.
Request the reopening in writing, attach the new evidence, and keep proof of when you sent it.
Homeland reopens closed and underpaid claims in Miami, Fort Myers and Newark.
Frequently asked questions
Can I reopen an insurance claim after it was closed?
What is a supplemental claim?
Why would an insurance company close a claim without paying?
Does reopening a claim restart the insurer's deadline?
Many of Homeland's claims start as closed or underpaid claims. We re-inspect, document what was missed, and present the reopened or supplemental claim within the deadlines.
This article is for general information only and is not legal or insurance advice. Statutes, regulations and policy wording change, and how they apply depends on your own policy and the facts of your claim. Homeland Public Adjusters is a public adjusting firm, not a law firm.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Public Adjuster Near Me page to get connected with the Homeland adjuster covering your area.