Insurance Denied or Lowballed Your Claim? Every Option, Compared

Homeland Public Adjusters · Last reviewed: October 2026
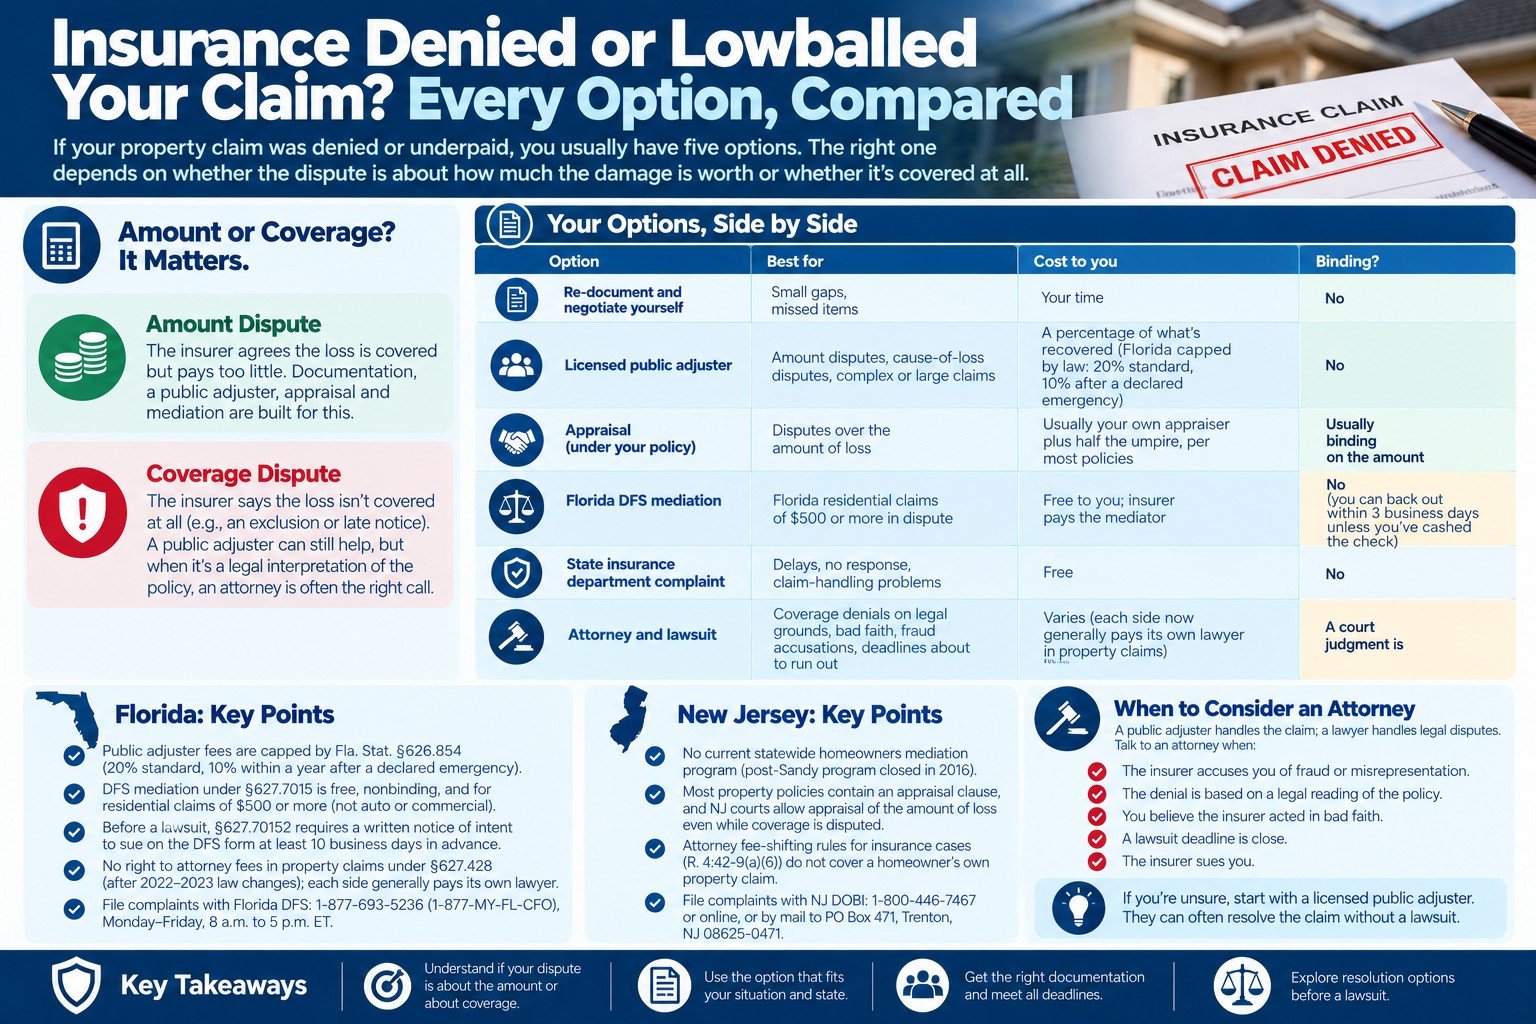
Short answer: If your property claim was denied or underpaid, you usually have five options: negotiate with better documentation (on your own or through a licensed public adjuster), appraisal, mediation (Florida's DFS program), a complaint to the state insurance department, or an attorney and lawsuit. The right one depends on whether the dispute is about how much the damage is worth or whether it's covered at all.
First question: amount or coverage?
An amount dispute means the insurer agrees the loss is covered but pays too little. Documentation, a public adjuster, appraisal and mediation are built for this.
A coverage dispute means the insurer says the loss isn't covered at all, for example because of an exclusion or late notice. Documentation and a public adjuster can still change the outcome when the issue is the cause of the damage; when the issue is a legal reading of the policy, an attorney is often the right call.
Every option, side by side
| Option | Best for | Cost to you | Binding? |
|---|---|---|---|
| Re-document and negotiate yourself | Small gaps, missed items | Your time | No |
| Licensed public adjuster | Amount disputes, cause-of-loss disputes, complex or large claims | A percentage of what's recovered; in Florida capped by law (20% standard, 10% within a year after a declared emergency) | No |
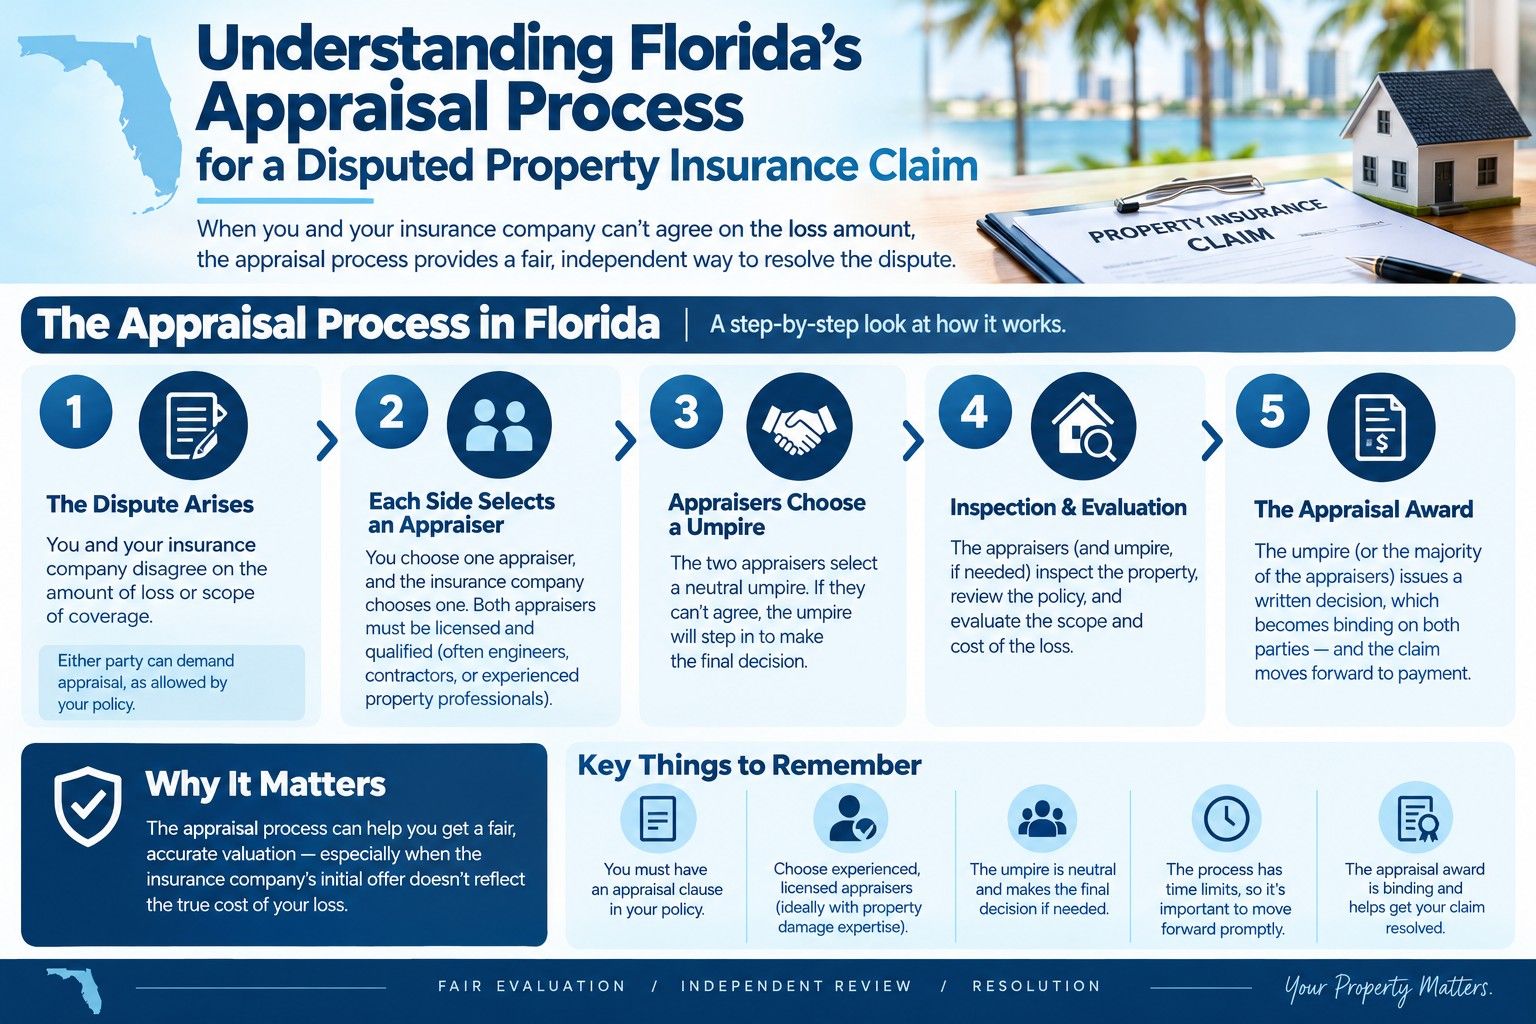
| Appraisal (under your policy) | Disputes over the amount of loss | Usually your own appraiser plus half the umpire, per most policies | Usually binding on the amount |
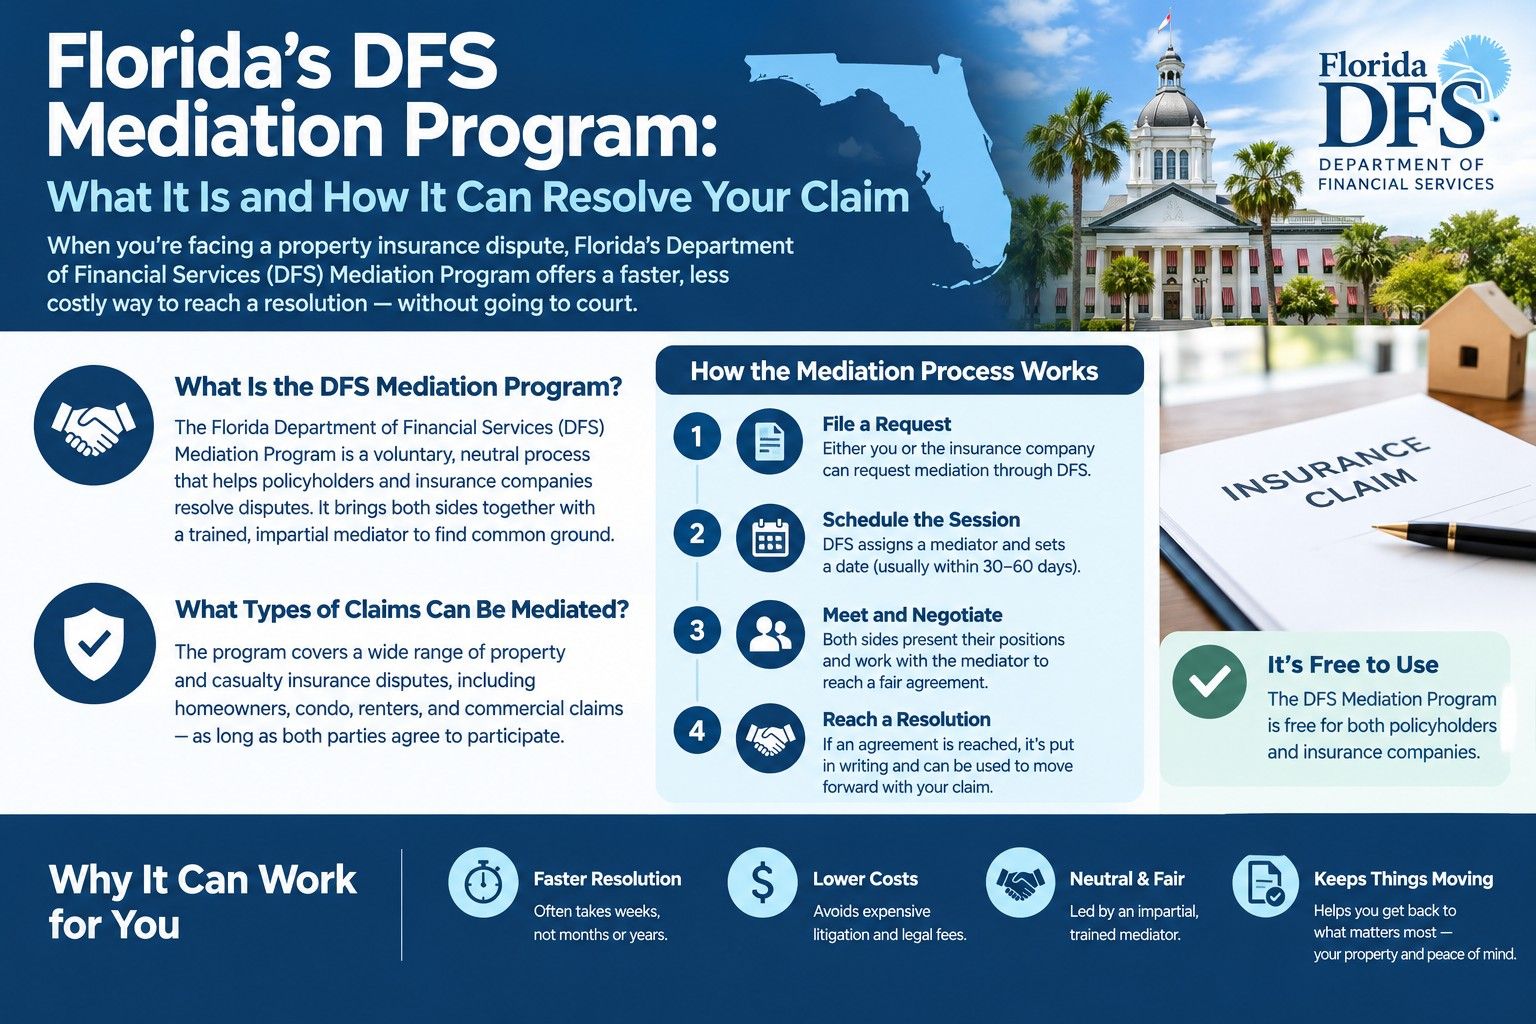
| Florida DFS mediation | Florida residential claims of $500 or more in dispute | Free to you; the insurer pays the mediator | No; you can back out of a settlement within 3 business days unless you've cashed the check |
| State insurance department complaint | Delays, no response, claim-handling problems | Free | No |
| Attorney and lawsuit | Coverage denials on legal grounds, bad faith, fraud accusations, deadlines about to run out | Varies; see the fee changes below | A court judgment is |
Florida specifics
Public adjuster fees are capped by Fla. Stat. §626.854; see our article on public adjuster fees.
DFS mediation under §627.7015 is paid for by the insurer, is nonbinding, and covers personal lines and commercial residential claims, not commercial or auto coverages. Disputes under $500 aren't eligible unless both sides agree. More in our DFS mediation guide.
Before a lawsuit, §627.70152 requires written notice of intent to sue on the DFS form at least 10 business days before filing; the insurer then has 10 business days to respond, and may require appraisal or another alternative dispute resolution method.
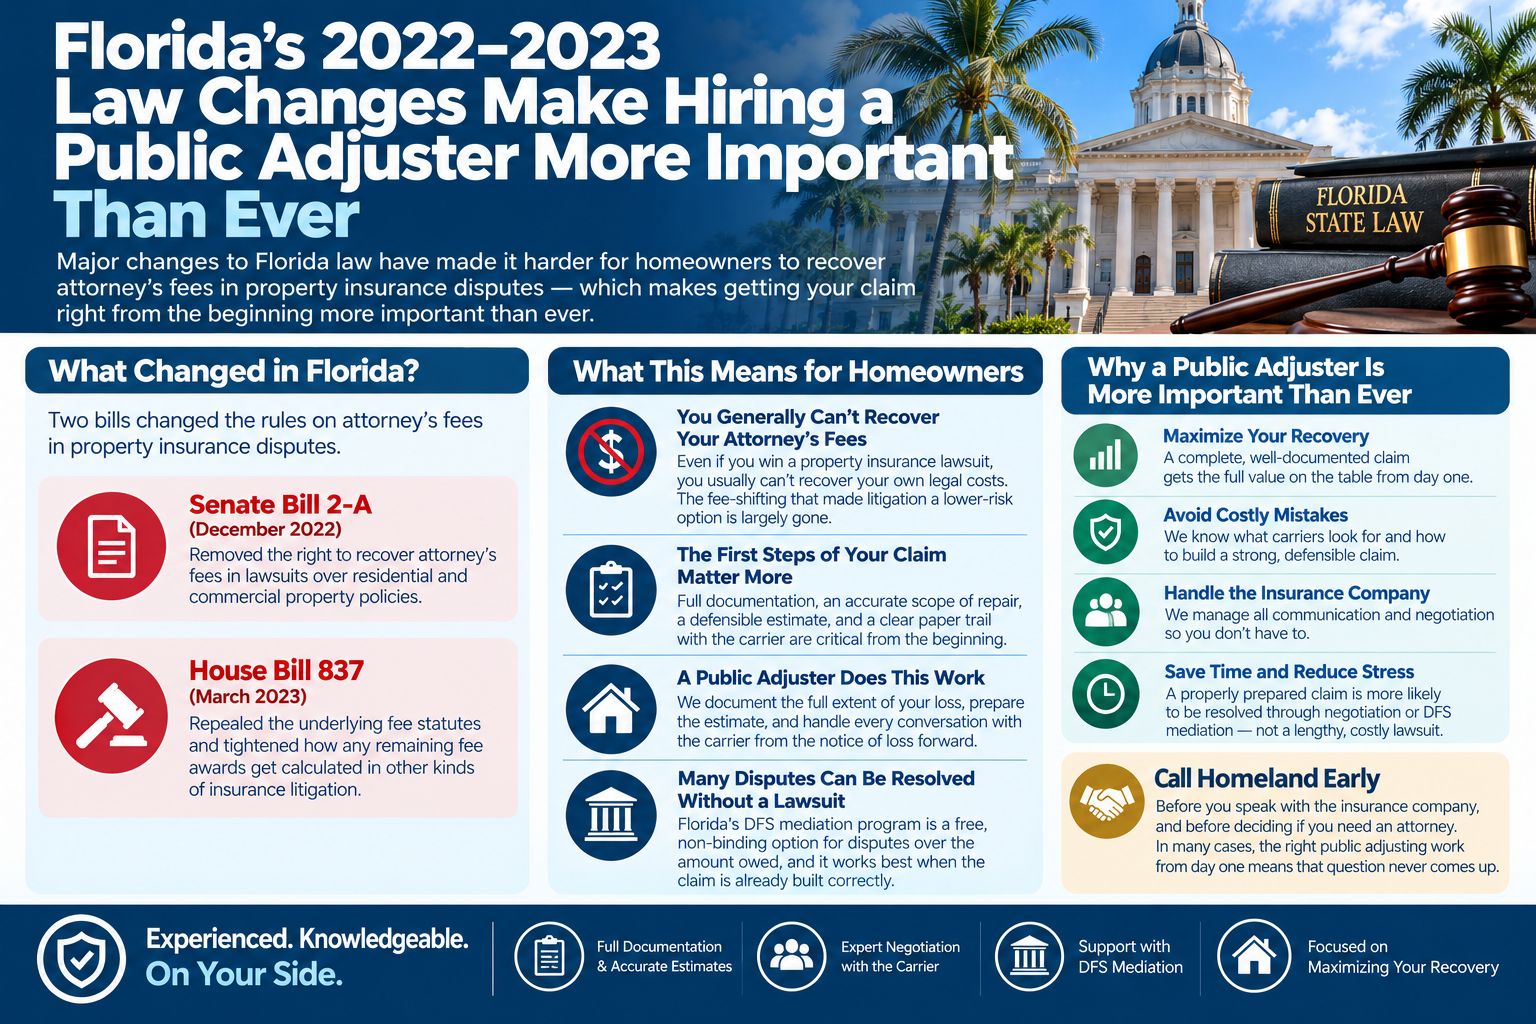
Attorney fees: in December 2022, Florida removed the right to attorney fees under §627.428 in suits under residential or commercial property policies, and in 2023 House Bill 837 repealed that section entirely. The declaratory-judgment fee section created in 2023 (§86.121) doesn't apply to property policies either. In practice, each side now generally pays its own lawyer, which is why many property disputes are worth trying to resolve before a lawsuit. See the 2022–2023 law changes.
Complaints go to the Florida Department of Financial Services (DFS) Division of Consumer Services, toll-free at 1-877-693-5236 (1-877-MY-FL-CFO), 8 a.m. to 5 p.m. ET, Monday through Friday.
New Jersey specifics
Complaints go to the NJ Department of Banking and Insurance (DOBI): online, by the Consumer Hotline at 1-800-446-7467, or by mail to PO Box 471, Trenton, NJ 08625-0471. Formal complaints must be in writing, with the company name, policy number and supporting documents.
Mediation: New Jersey's post-Sandy mediation program closed to new requests in 2016, and there is no current statewide homeowners mediation program like Florida's.
Appraisal: most New Jersey property policies contain an appraisal clause, and New Jersey courts have allowed appraisal of the amount of loss even while coverage is disputed.
Attorney fees: New Jersey's court rule shifting fees in insurance cases (R. 4:42-9(a)(6)) applies to liability policies, and courts have held it doesn't cover a homeowner's own property claim. New Jersey's 2022 Insurance Fair Conduct Act is limited to auto uninsured and underinsured motorist claims.
When an attorney is the better choice
A public adjuster handles the claim; a lawyer handles legal disputes. Talk to an attorney when the insurer accuses you of fraud or misrepresentation, when the denial rests on a legal reading of the policy, when you believe the insurer acted in bad faith, when a lawsuit deadline is close, or when the insurer sues you.
Homeland handles disputed claims in Broward County, Palm Beach County and Ocean County.
Frequently asked questions
What can I do if my insurance claim is denied?
Public adjuster or attorney: which do I need?
Is appraisal binding?
Does New Jersey have a mediation program like Florida's?
Homeland is a public adjusting firm, not a law firm. If your claim is a dispute over the damage or its value, we can take it from here; if it needs a lawyer, we'll tell you.
This article is for general information only and is not legal or insurance advice. Statutes, regulations and policy wording change, and how they apply depends on your own policy and the facts of your claim. Homeland Public Adjusters is a public adjusting firm, not a law firm.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Public Adjuster Near Me page to get connected with the Homeland adjuster covering your area.