Pipe Burst, AC Leak or Roof Leak in Florida: Who to Call First

Homeland Public Adjusters · Last reviewed: October 2026
Short answer: Stop the water first: shut the main valve for a burst pipe, turn the system off for an AC leak, and catch or cover a roof leak if it’s safe. Then photograph and video everything before anything is moved or thrown away. Then call Homeland first, 24/7, at (305) 783-3777: a licensed public adjuster comes to your property within hours, anywhere in Florida, and helps you report the claim with the damage documented. Bring in a plumber, AC technician, roofer or water-mitigation company as needed to stop the damage, and keep every invoice.
Have a property claim anywhere in Florida? A licensed Homeland public adjuster comes to you within hours — no need to visit an office. Call (305) 783-3777 (Florida) or (732) 517-3777 (New Jersey), 24/7.
1. Stop the water and make the home safe
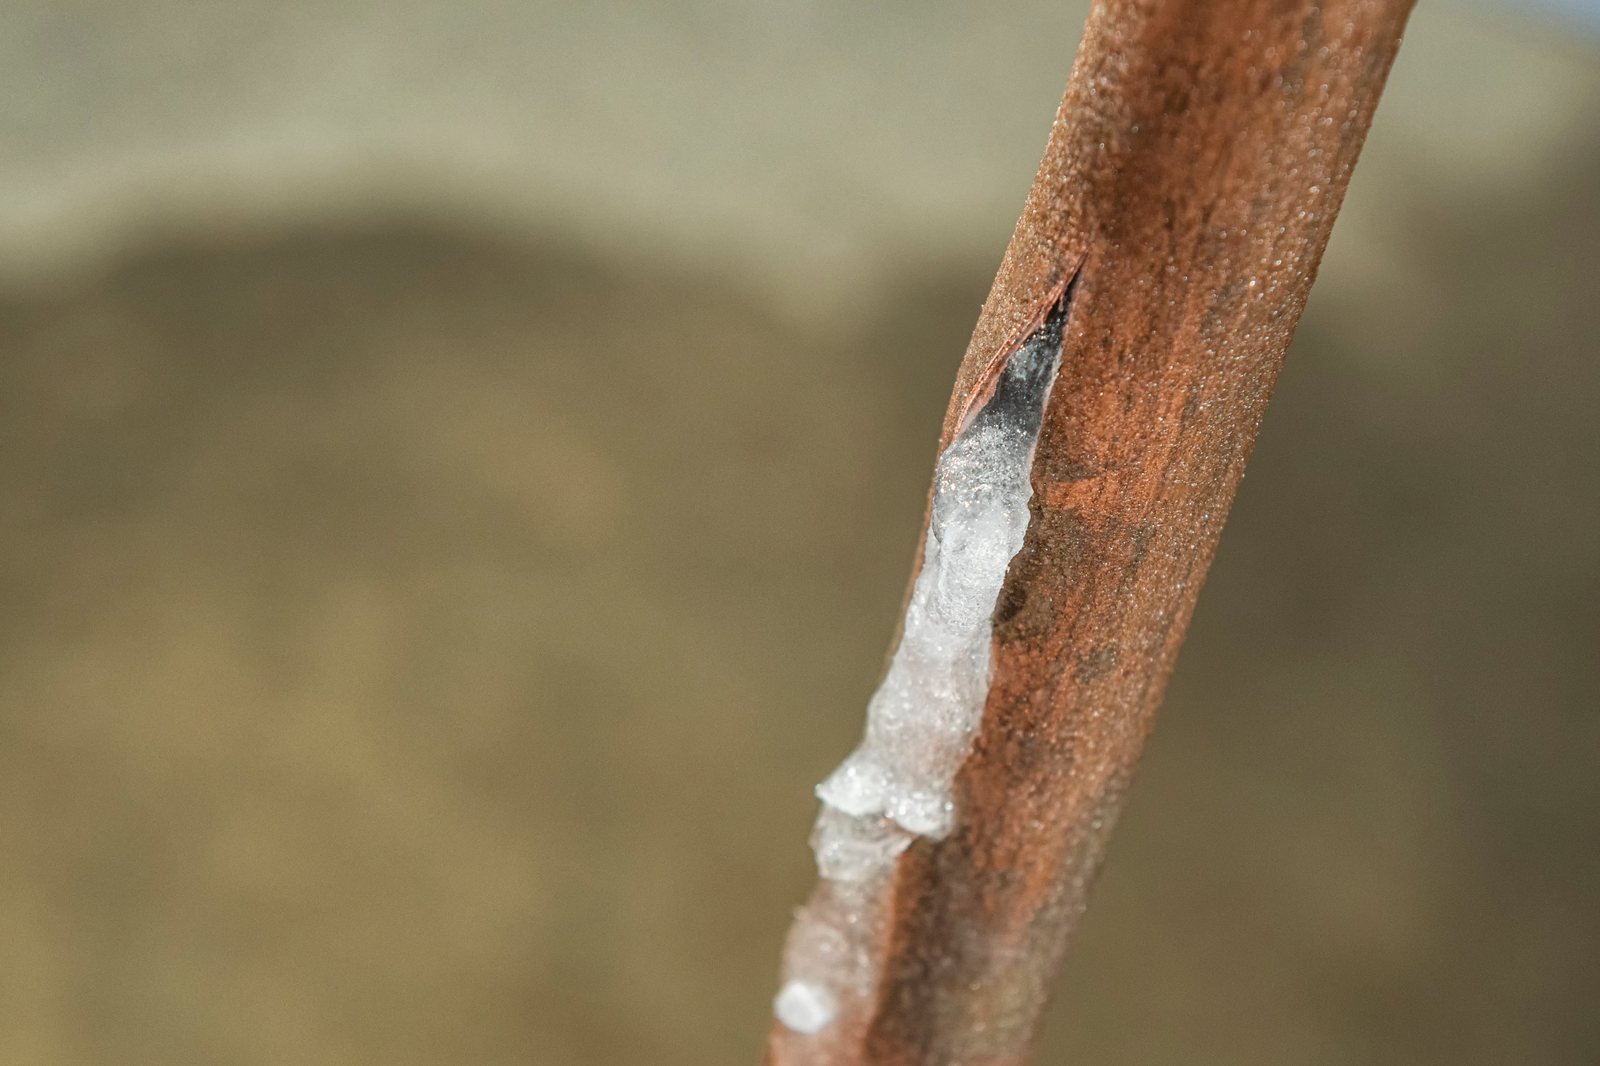
- Burst or leaking pipe: shut off the main water valve, then open a low faucet to drain the lines. If water is near outlets or the electrical panel, turn off the power at the breaker only if you can reach it without standing in water.
- AC leak: turn the system off at the thermostat and the breaker. Leaks often come from a clogged condensate drain line or an overflowing drain pan; don’t run the unit until it is checked.
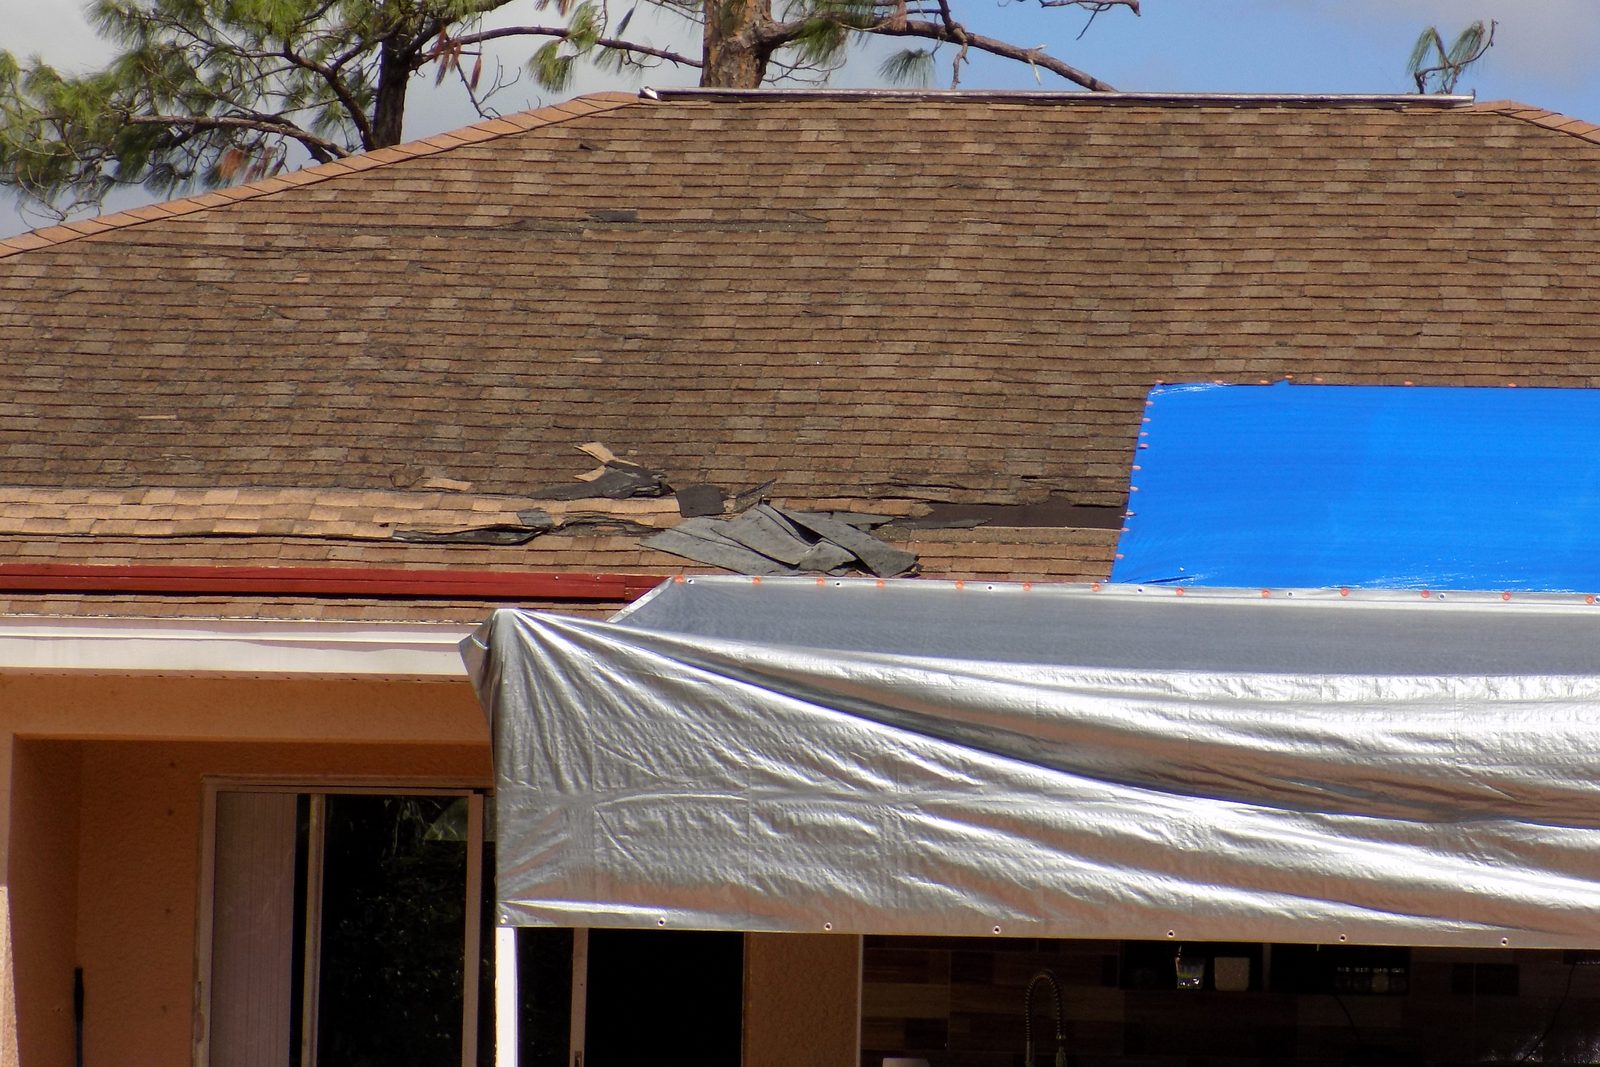
- Roof leak: catch the water, move belongings and pull back wet rugs. Never climb onto a wet or storm-damaged roof; a roofer can tarp it.
- Water heater: close the cold-water supply valve on top of the tank and turn off its power or gas.
Your policy expects this. Most homeowners policies list the same duties after a loss: protect the property from further damage, make reasonable and necessary repairs to protect it, and keep an accurate record of repair expenses. Temporary repairs are part of your job; permanent repairs can usually wait until the damage is documented.
2. Document before anything is removed
- Wide photos of each affected room, then close-ups; a slow video walk-through with the date.
- The source: the pipe or fitting, the AC drain line or pan, the opening in the roof.
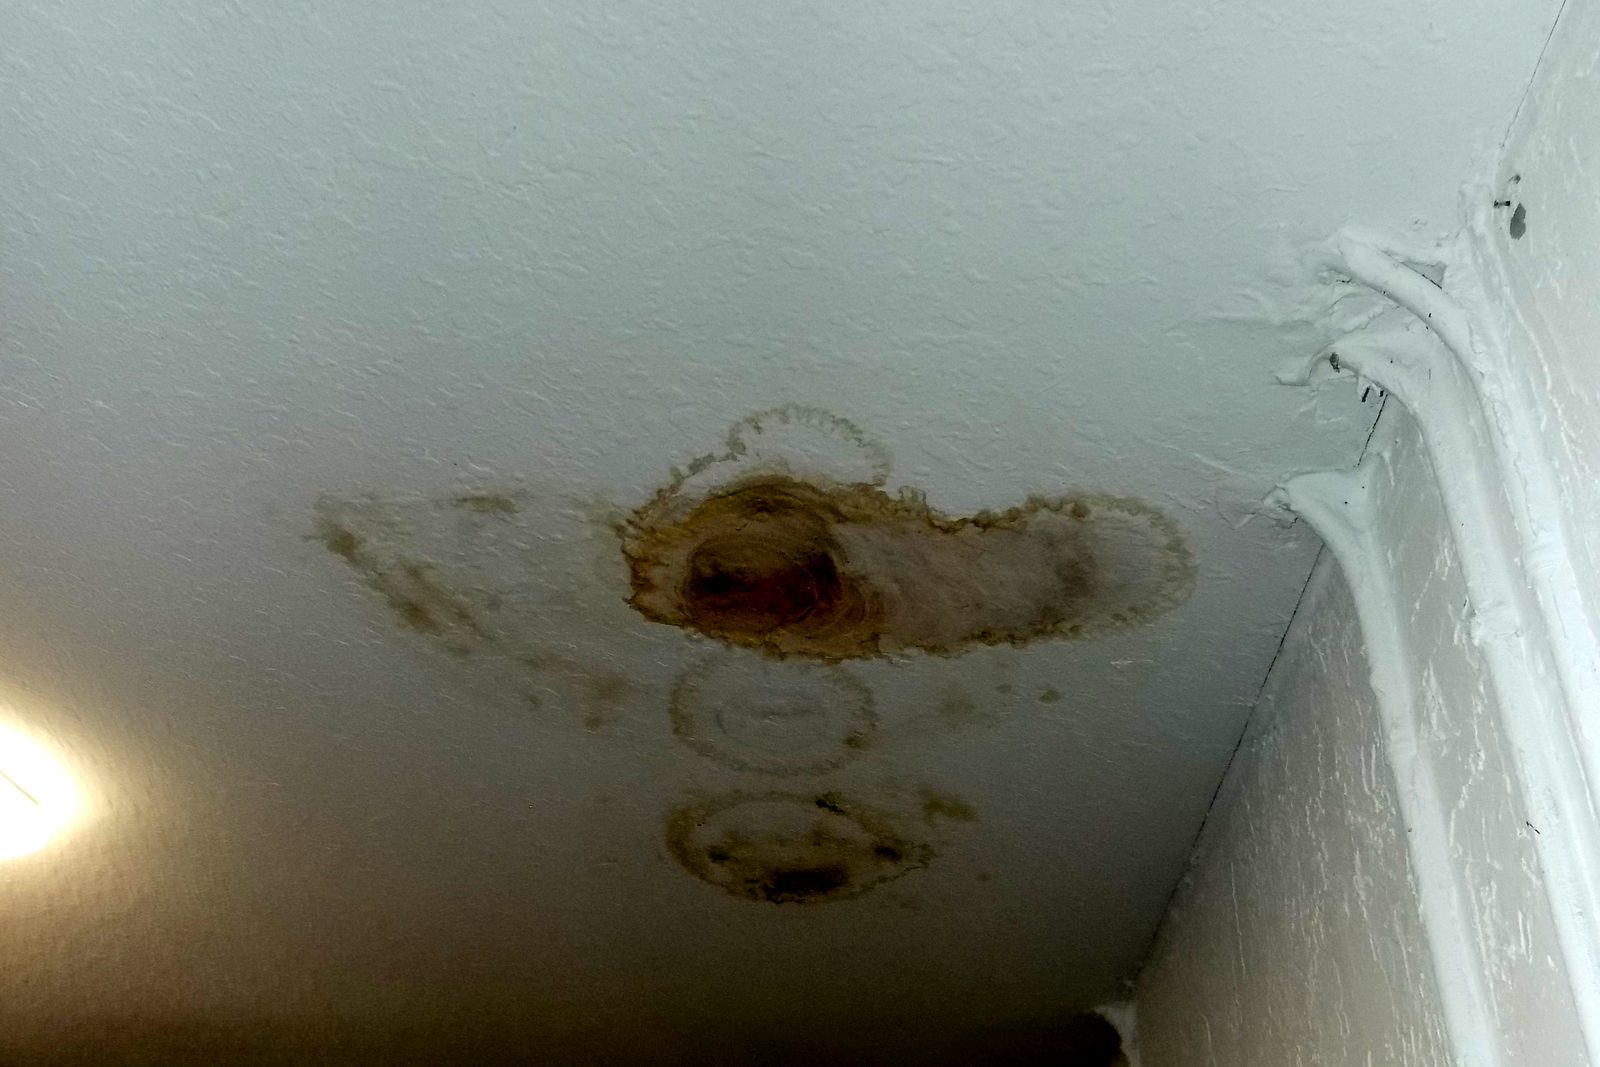
- Water lines on walls, ceilings, cabinets and flooring, and any damaged belongings before they are thrown out. Keep a sample of flooring, carpet or pad.
- When you found the water, and every invoice, moisture reading and drying log from the companies that helped.
3. Call Homeland first
Before you call anyone about the claim itself, call us 24/7 at (305) 783-3777. A licensed Homeland public adjuster comes to your property, anywhere in Florida, documents the whole loss, helps you give the insurer notice, and writes an itemized estimate so the insurer’s inspection is measured against the full damage. No Recovery, No Fee. Hablamos español.
Insurers often ask how long the water had been leaking, because many policies exclude continuous or repeated seepage. Answer accurately and let the documentation speak; see long-term leak denials.
Who does what
| Who | What they do |
|---|---|
| Plumber, AC technician or roofer | Stops the source and repairs the cause. Ask for a written note of what failed. |
| Water-mitigation company | Extracts water, dries the structure and records moisture readings. |
| Licensed public adjuster (Homeland) | Works for you: documents the whole loss, writes the itemized estimate, presents and negotiates the claim. |
| The insurer’s adjuster | Adjusts the claim for the insurance company. |
In Florida, a contractor can’t negotiate your claim unless also licensed as a public adjuster (§626.854(16)).
Deadlines that matter
- Report a new claim within 1 year after the date of loss; a supplemental claim within 18 months (§627.70132).
- If the insurer inspects in person, it must do so within 30 days after it receives your proof-of-loss statements (§627.70131(3)(b)).
- The insurer must pay or deny within 60 days after it receives notice of the claim, unless factors beyond its control cause the delay (§627.70131(7)(a)).
More detail: burst pipes · AC leaks · roof leaks · ceiling leaks · water heaters · Florida’s $10,000 water damage sublimit.
Frequently asked questions
Should I call my insurance company first?
Can I start cleanup before the insurer inspects?
Does Homeland come to me?
Sources (checked October 30, 2026)
- Fla. Stat. §627.70132: notice deadlines for new, reopened and supplemental claims
- Fla. Stat. §627.70131: insurer deadlines, including pay or deny within 60 days ((7)(a)) and inspection within 30 days ((3)(b))
- Fla. Stat. §626.854: public adjuster rules, fee caps and cancellation rights
- Florida DFS: Mediation and Neutral Evaluation
- Florida DFS, Division of Consumer Services (helpline 1-877-693-5236)
This article is for general information only and is not legal or insurance advice. Statutes, regulations and policy wording change, and how they apply depends on your own policy and the facts of your claim. Homeland Public Adjusters is a public adjusting firm, not a law firm.
- Insurance Denied Your Property Claim in Florida? What to Do Next
- Public Adjuster or Lawyer for a Florida Insurance Claim?
- Kitchen & Grease Fire Insurance Claims
- Neighbor's Tree Fell on My House: Who Pays?
- Water Heater Leaking? What to Do & If Insurance Pays
 Nelson Avila
 Yeni Martinez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Denied and Underpaid Claims page.