Water Claim Denied as a “Long-Term Leak” or “Repeated Seepage”?

Homeland Public Adjusters · Last reviewed: October 2026
Short answer: Many Florida policies exclude damage from “constant or repeated seepage or leakage” of water over a period of 14 or more days. A denial on that basis is about timing: the insurer says the water had been leaking for at least two weeks. Your answer is evidence of when the leak actually started, and which damage happened when.
What the wording usually says
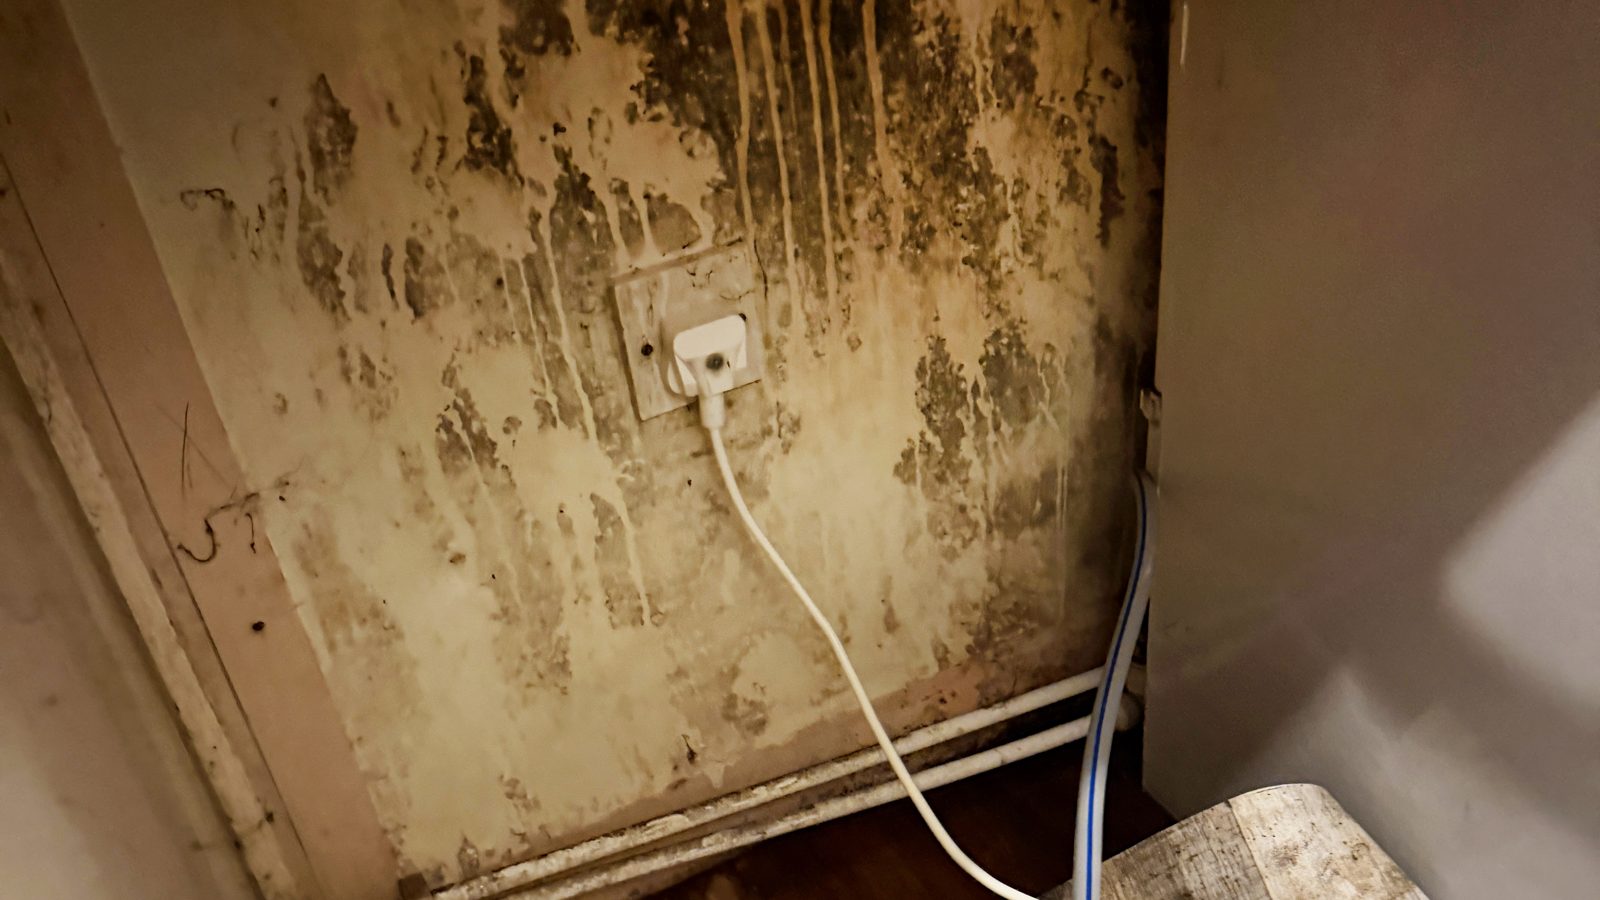
The language is not uniform. Many Florida carrier forms exclude seepage or leakage “over a period of 14 or more days.” Other policies use older wording such as “over a period of weeks, months or years.” Some also pair it with exclusions for wear and tear, deterioration, rot and mold. Read the exact wording in your own policy and any water-damage endorsement; Florida also has policies with a $10,000 water damage sublimit.
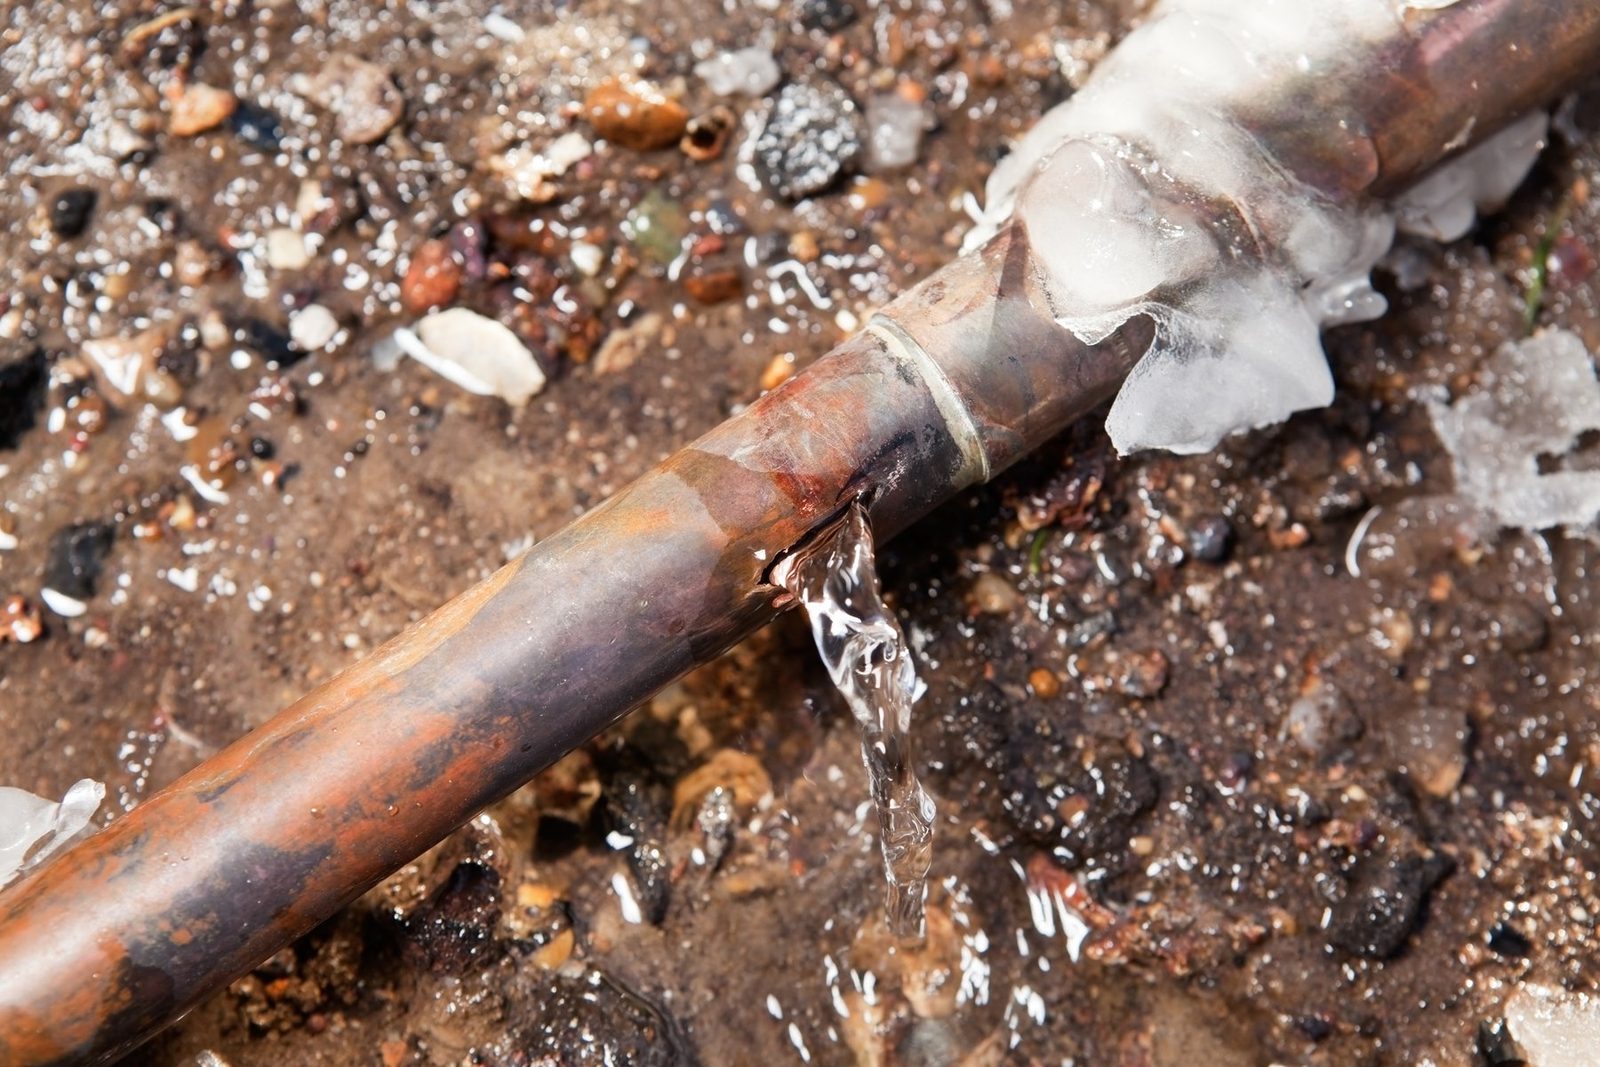
What a Florida court held
In Hicks v. American Integrity Insurance Co. of Florida (Fla. 5th DCA 2018), the policy excluded seepage or leakage “over a period of 14 or more days.” The court held that the exclusion does not unambiguously exclude losses caused by leakage over 13 days or less, so damage from the first 13 days of a longer leak was covered. The point for any claim: even when a leak ran longer than 14 days, part of the damage may still be payable.
How to show when a leak started
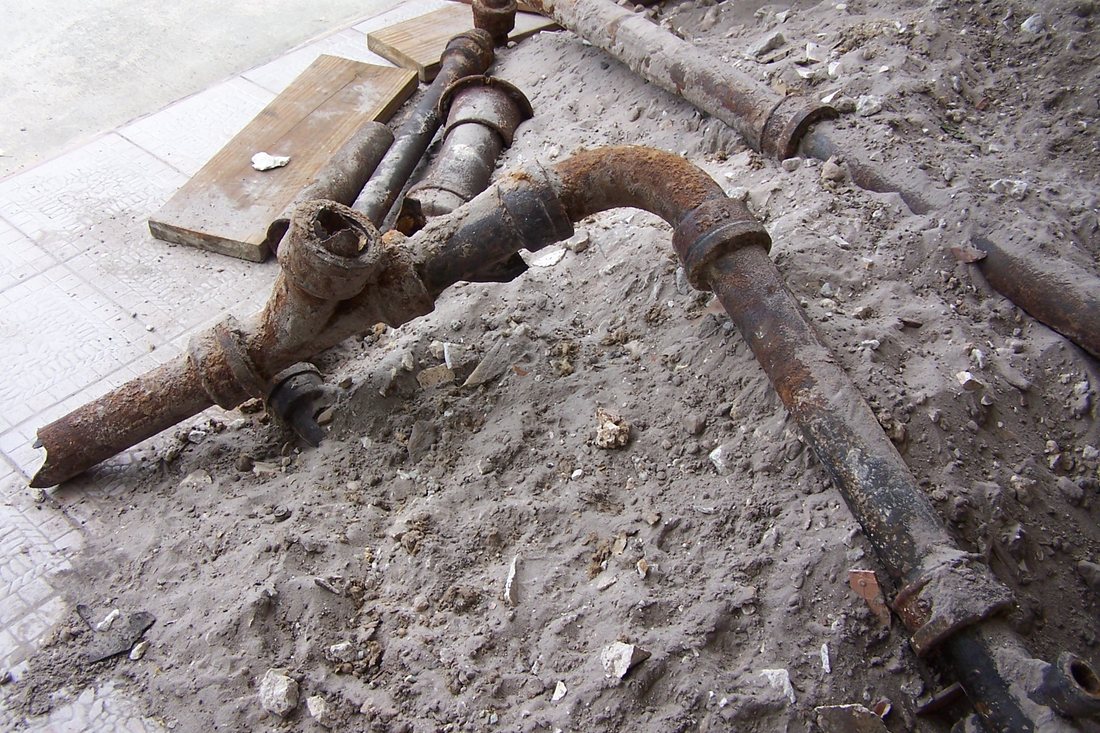
- A plumber’s or leak-detection report on the source, the type of failure and how it failed
- Moisture mapping that shows how far the water spread, room by room
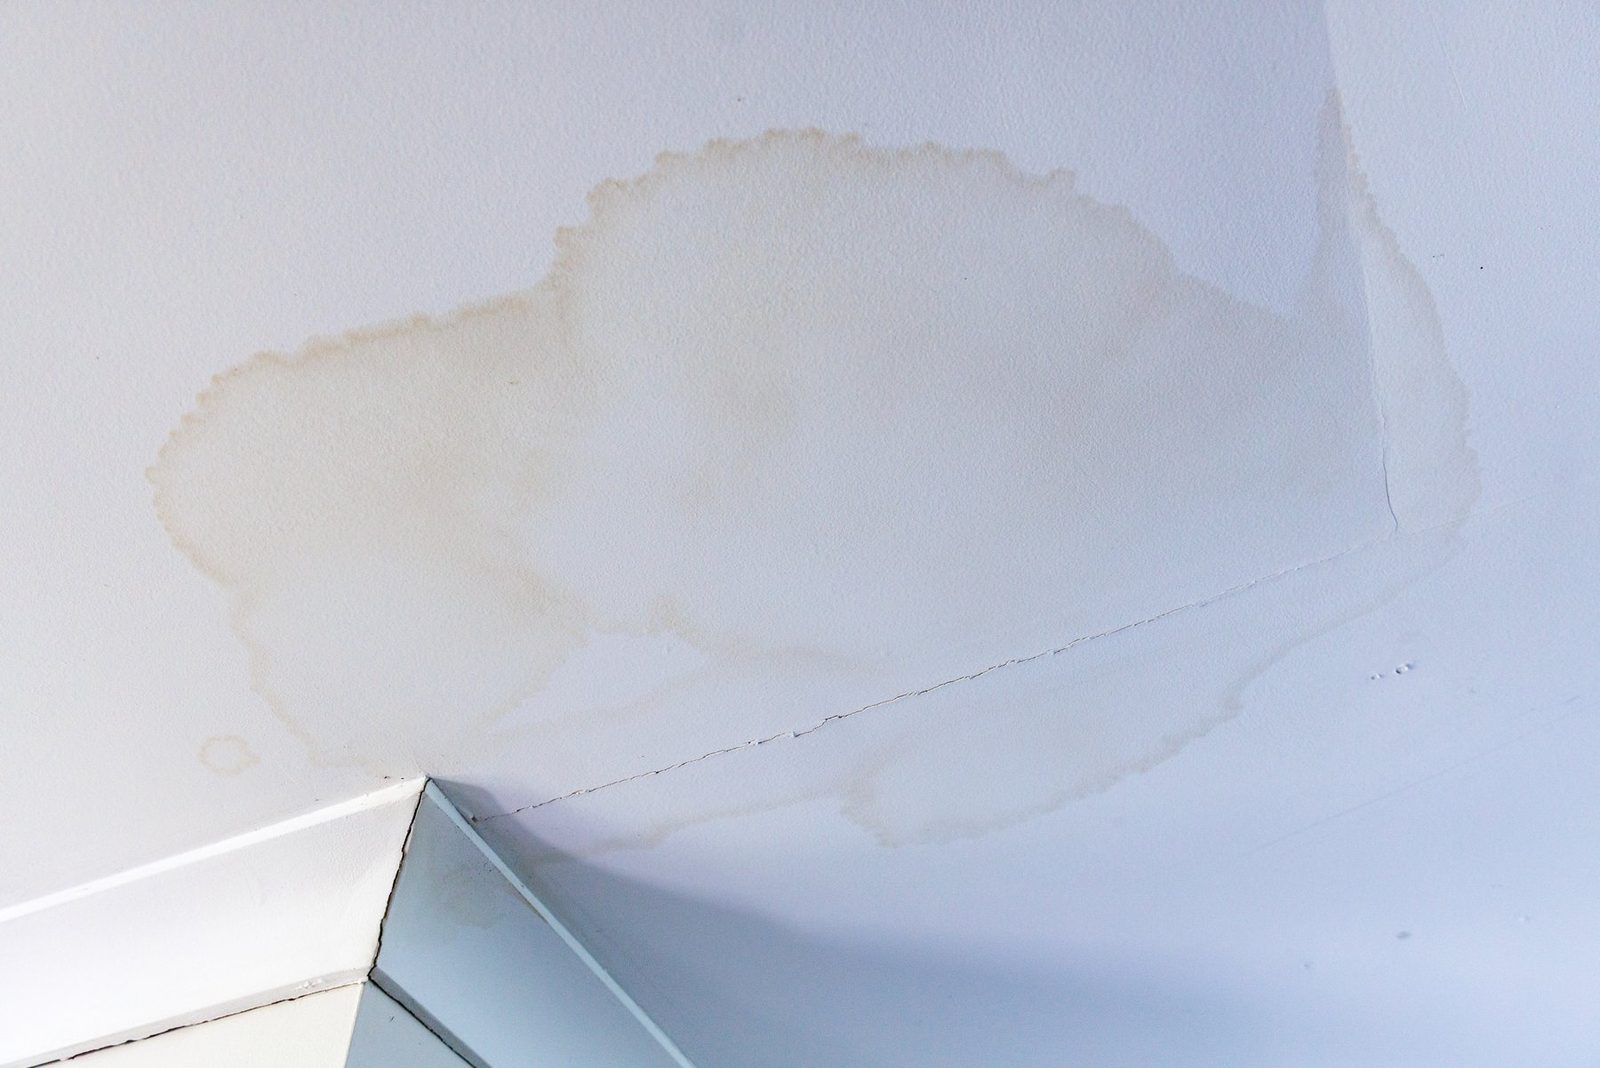
- Dated photos, water bills showing a sudden jump, and when you first saw stains or smelled water
- The failed part itself: keep the pipe, fitting, supply line or valve
The standard ISO homeowners form (HO 00 03 05 11) also covers “ensuing loss” after certain exclusions: even when the cause is excluded, resulting damage not excluded elsewhere may be covered. See ensuing loss and appliance leak claims.
Frequently asked questions
Is a slow leak covered by homeowners insurance?
What did Hicks v. American Integrity decide?
How can I prove the leak was recent?
Is mold from a leak covered?
Call Homeland first. Before you answer the insurer, sign anything or accept a final number, call us 24/7 at (305) 783-3777 in Florida or (732) 517-3777 in New Jersey. We read the letter against your policy, document the loss and present the claim for you. Hablamos español.
This article is for general information only and is not legal or insurance advice. Statutes, regulations and policy wording change, and how they apply depends on your own policy and the facts of your claim. Homeland Public Adjusters is a public adjusting firm, not a law firm.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Denied and Underpaid Claims page.