Claim Denied for “Late Notice”? The Florida and New Jersey Rules

Homeland Public Adjusters · Last reviewed: October 2026
Short answer: Late notice means the insurer says it learned of the loss too late. In Florida, a hard deadline applies by statute; inside that deadline, the question is whether the delay actually hurt the insurer’s ability to investigate. In New Jersey, courts have long required insurers to show “appreciable prejudice” before late notice forfeits coverage under occurrence policies.
Florida: the statutory deadlines
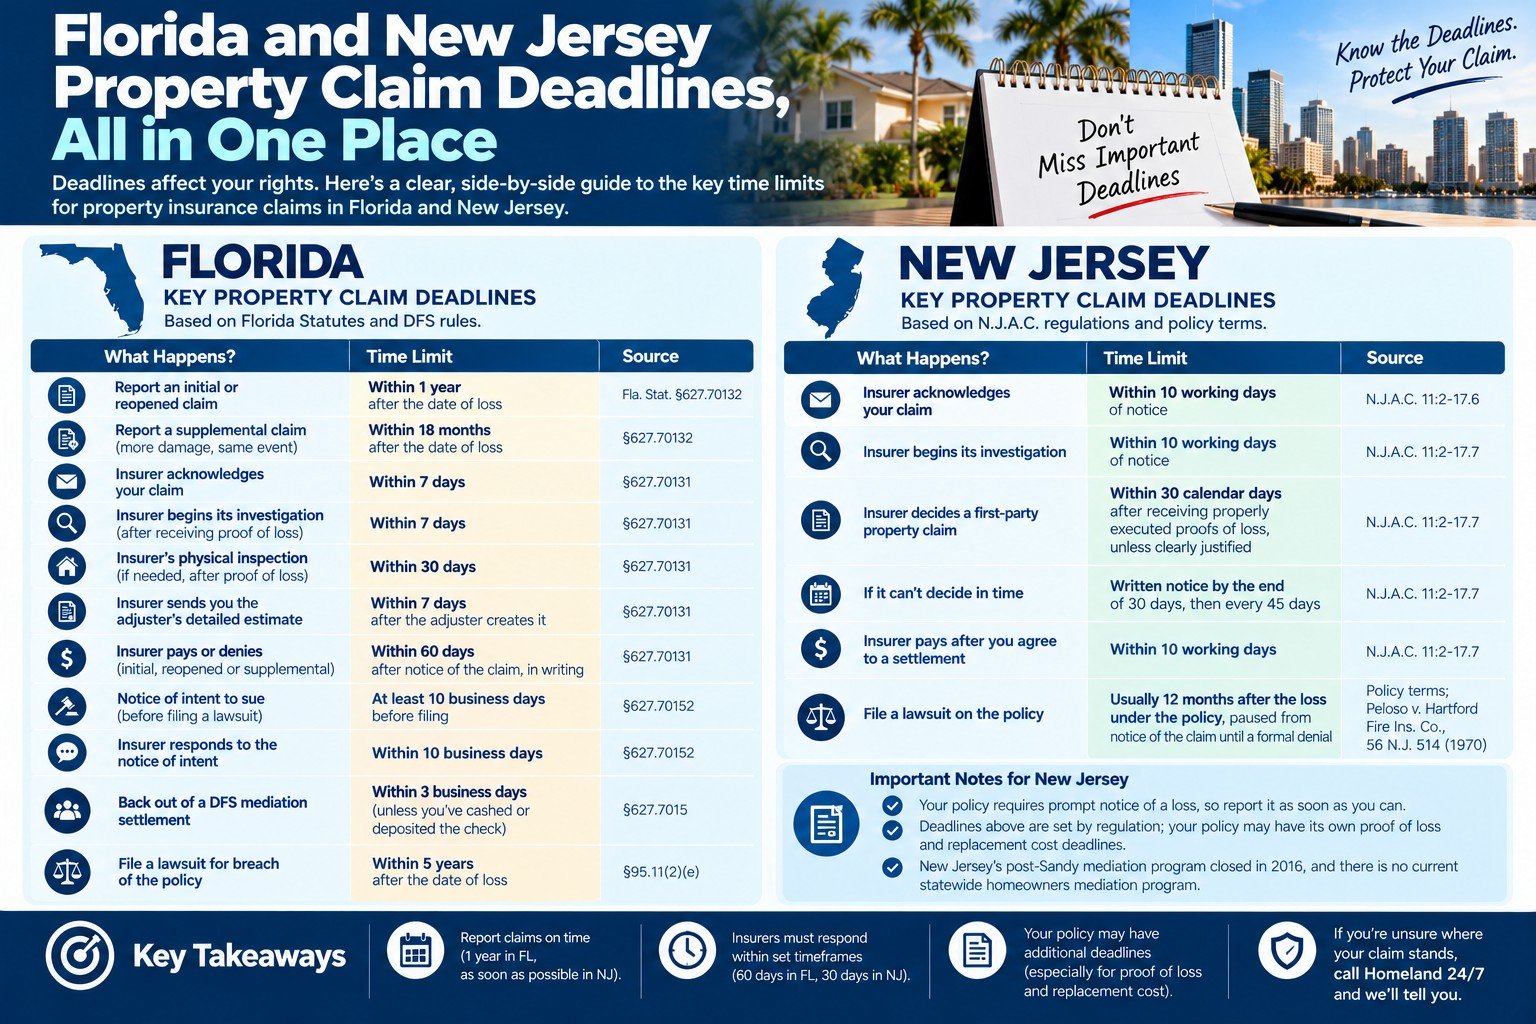
Under Fla. Stat. §627.70132, a claim is barred unless notice was given within 1 year after the date of loss for an initial or reopened claim, and within 18 months for a supplemental claim. For a hurricane, the date of loss is the date the hurricane made landfall; for other windstorms and severe weather it is the date the National Oceanic and Atmospheric Administration (NOAA) verifies the event. See every Florida and New Jersey claim deadline.
Within those windows, most policies also require “prompt” notice. An insurer relying on that language will usually argue the delay kept it from seeing the damage as it was. Evidence that answers that argument: dated photos, repair invoices, weather records and anything that shows the condition of the property at the time of the storm.
New Jersey: appreciable prejudice
New Jersey’s Supreme Court held in Cooper v. Government Employees Insurance Co. (1968) that an insurer must show a breach of the notice provision and “a likelihood of appreciable prejudice” to deny coverage for late notice, and the court has described that rule as clearly applying to occurrence-based policies. How it applies to a first-party property claim depends on the facts, so treat any late-notice letter in New Jersey as something to have reviewed.
New Jersey regulations also say the insurer remains liable for hidden damage directly related to the loss (N.J.A.C. 11:2-17.10(a)3). The 12-month suit limit in the standard fire policy is paused from the time notice is given until the insurer formally denies (Peloso v. Hartford Fire, 1970); check your own policy’s wording.
When the damage showed up later
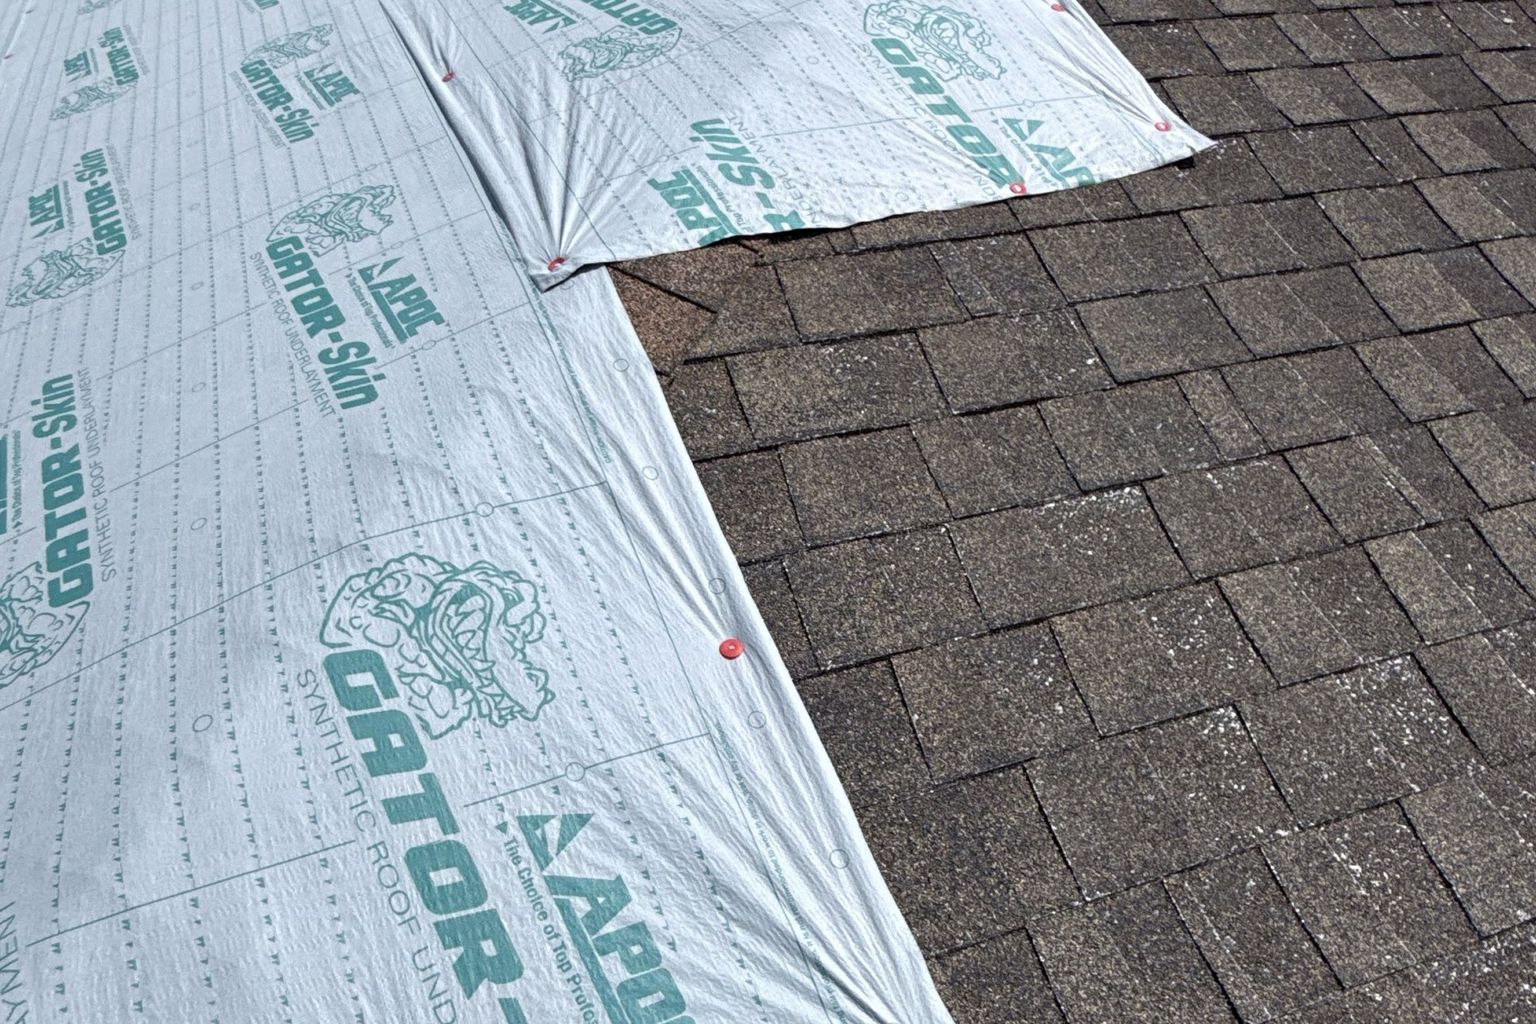
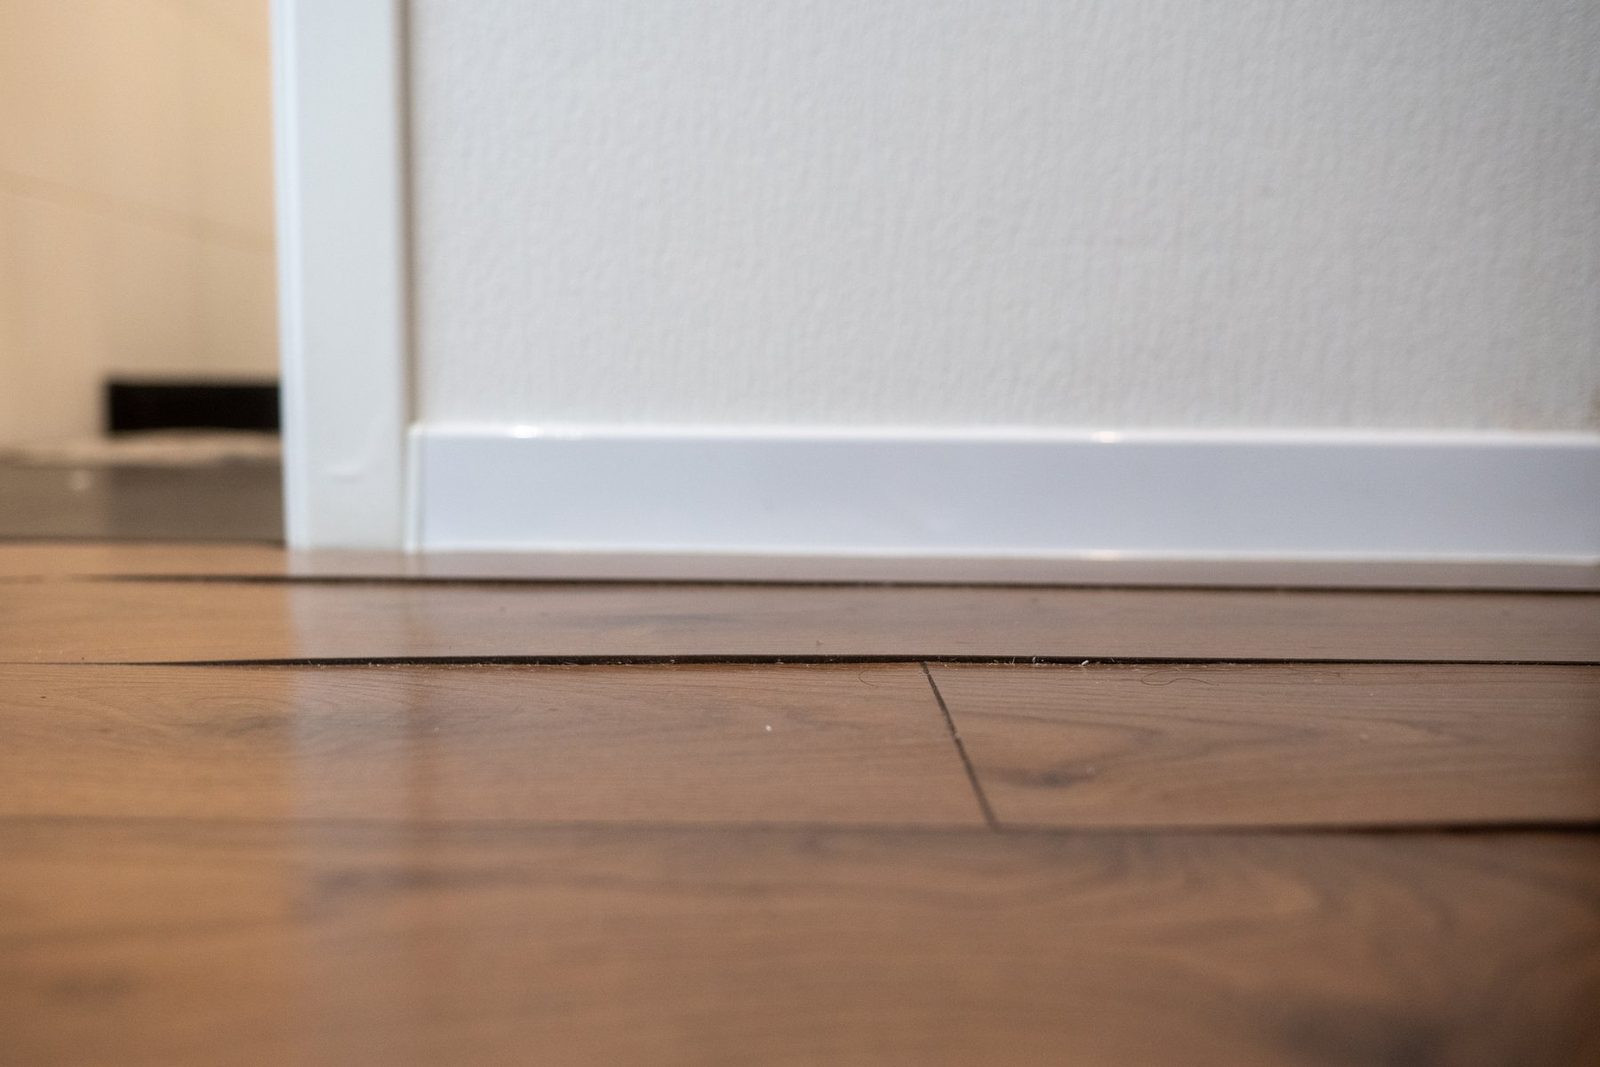
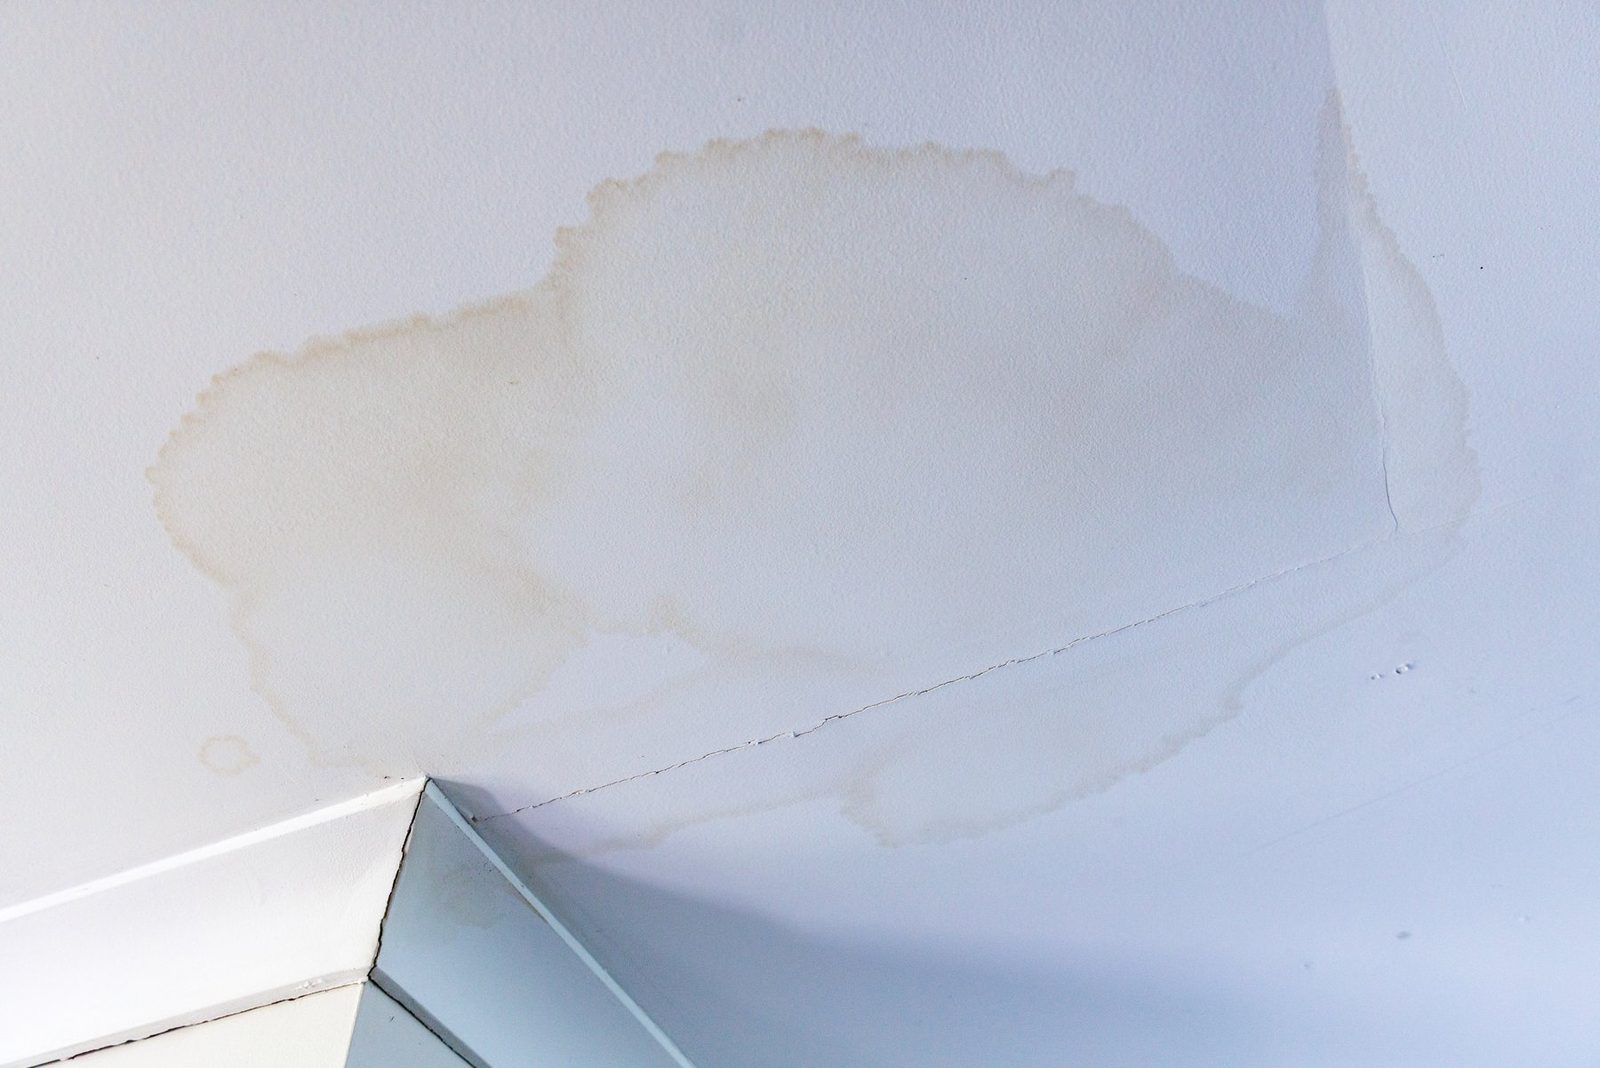
Roof leaks, hidden water and cracked framing often appear weeks after a storm. Write down when you first noticed each item and what you saw, keep the photos with their dates, and get the damage documented before any repair covers it up. That timeline is usually the heart of a late-notice dispute.
Frequently asked questions
How long do I have to report hurricane damage in Florida?
Can a claim be denied for late notice inside the 1-year window?
What does appreciable prejudice mean in New Jersey?
I just found damage from last year's storm. Is it too late?
Call Homeland first. Before you answer the insurer, sign anything or accept a final number, call us 24/7 at (305) 783-3777 in Florida or (732) 517-3777 in New Jersey. We read the letter against your policy, document the loss and present the claim for you. Hablamos español.
This article is for general information only and is not legal or insurance advice. Statutes, regulations and policy wording change, and how they apply depends on your own policy and the facts of your claim. Homeland Public Adjusters is a public adjusting firm, not a law firm.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Denied and Underpaid Claims page.