Does Homeowners Insurance Cover Burst Pipes?

Homeland Public Adjusters · Last reviewed: October 2026
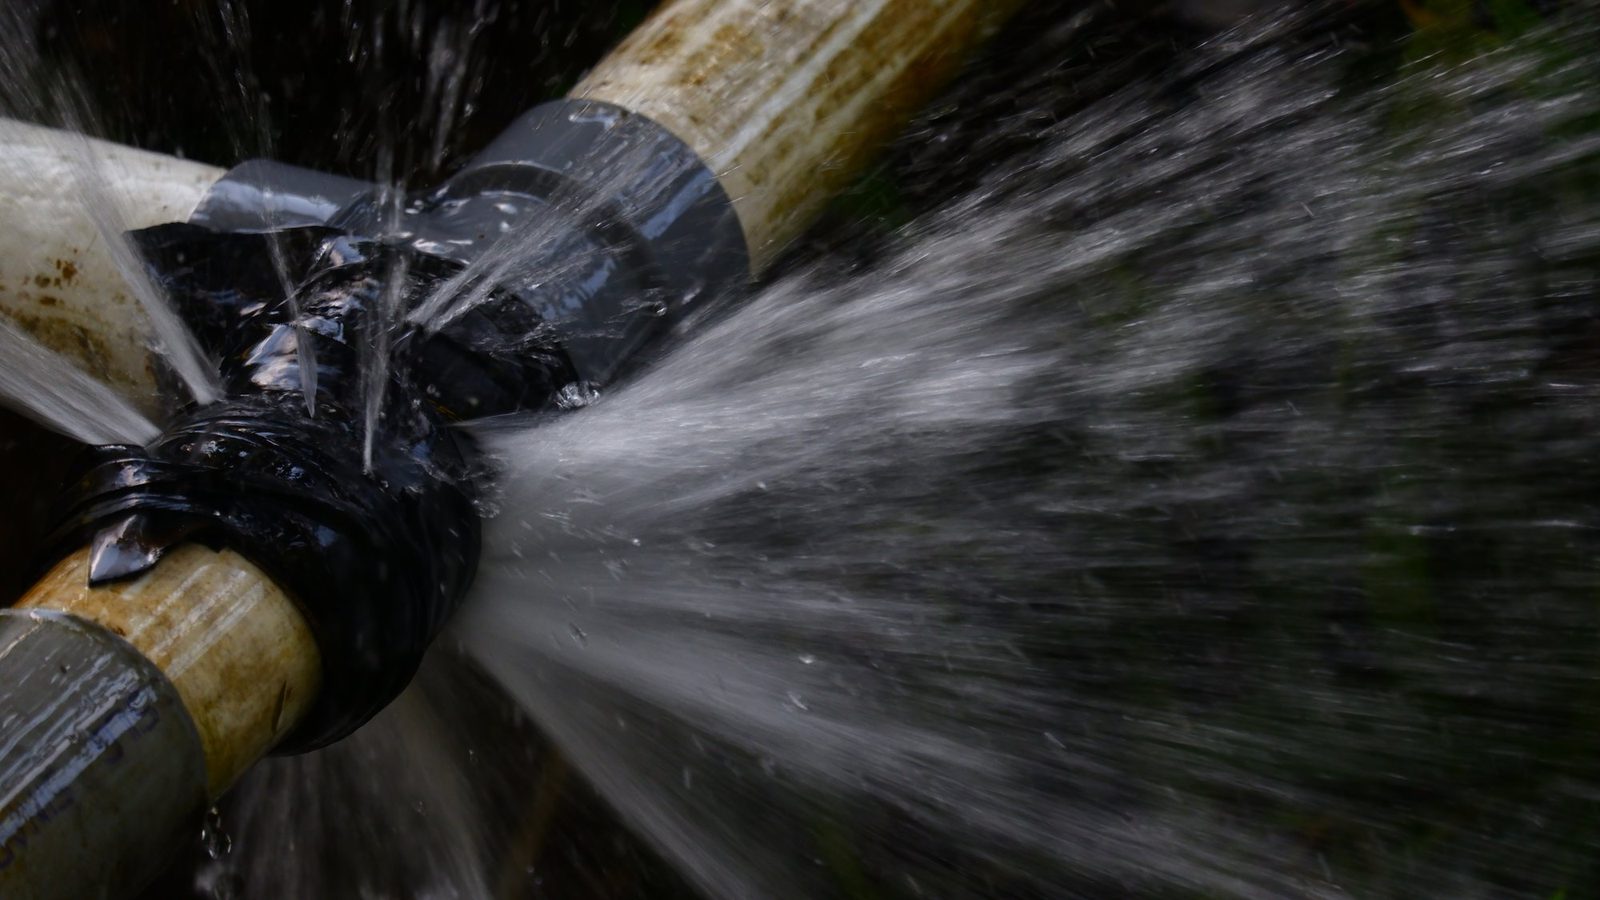
Short answer: Usually, yes. Most standard homeowners policies cover the sudden, accidental water damage a burst pipe causes to your home and belongings. They generally don't cover slow leaks, the worn-out pipe itself, or damage from a pipe that froze while the house was left unheated or the water wasn't shut off. Your own policy's wording decides.
Have a property claim anywhere in Florida? A licensed Homeland public adjuster comes to you within hours — no need to visit an office. Call (305) 783-3777 (Florida) or (732) 517-3777 (New Jersey), 24/7.
What is usually covered
The standard homeowners form covers sudden and accidental discharge of water from a plumbing system: a pipe that bursts, a supply line that fails, a water heater that lets go. That means the damage to floors, walls, cabinets, ceilings and belongings, plus the cost of tearing out and replacing the part of the building needed to reach the leak. Additional living expenses apply if you can't stay in the home.
What is usually not covered
Gradual leaks and seepage. Water that dripped for weeks behind a wall is typically excluded as a repeated or continuous leak, even when the final damage is large.
The pipe itself. Policies generally pay for the damage the water caused, not to replace the pipe, valve or appliance that failed.
Wear, corrosion and neglect. Deterioration isn't a sudden event.
Freezing without reasonable care. The standard ISO homeowners form, as reproduced by Insurance Journal, excludes loss caused by freezing of plumbing, heating, air conditioning or sprinkler systems unless you "used reasonable care to maintain heat in the building" or shut off the water supply and drained the systems. A vacant or unheated home during a hard freeze is the scenario most likely to draw a freezing denial.
Florida: the $10,000 water damage cap
A growing number of Florida policies cap non-weather water damage, including burst pipes, at $10,000 unless you buy the cap off. Emergency water removal by a restoration company can use up that cap before repairs begin. See Florida's $10,000 water damage sublimit.
New Jersey: frozen pipes
New Jersey winters make the freezing exclusion the issue that decides most burst-pipe claims there. Maintaining heat while you're away, and documenting that you did (thermostat settings, utility bills, a neighbor's check-ins), is what keeps the claim covered. Once Homeland files the claim, N.J.A.C. 11:2-17.7 requires the insurer to decide a first-party property claim within 30 calendar days after it receives properly executed proofs of loss. Ice dams and snow-load damage are covered in our New Jersey winter perils guide.
What to do when a pipe bursts
Shut off the water at the main valve, then the electricity to wet areas if it's safe.
Photograph everything before cleanup: the pipe, the water, the damage, the meter reading.
Keep the failed part. Don't let a plumber throw away the burst section; it's evidence of a sudden failure.
Dry the home and keep every invoice.
Call Homeland first: we give notice inside the deadlines. In Florida, notice is due within 1 year of the date of loss under Fla. Stat. §627.70132.
Homeland handles burst-pipe and water claims in Miami, Clearwater and Edison.
Frequently asked questions
Does homeowners insurance cover a burst pipe?
Does insurance cover frozen pipes that burst?
Will insurance pay to replace the pipe?
Is there a limit on water damage claims in Florida?
Homeland documents burst-pipe losses the way insurers evaluate them: cause, timing, scope and the policy language that applies. Call before you talk to the insurance company.
This article is for general information only and is not legal or insurance advice. Statutes, regulations and policy wording change, and how they apply depends on your own policy and the facts of your claim. Homeland Public Adjusters is a public adjusting firm, not a law firm.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Public Adjuster Near Me page to get connected with the Homeland adjuster covering your area.