Water Damage Restoration in Florida: Who Pays for It?
Homeland Public Adjusters · Last reviewed: November 2026
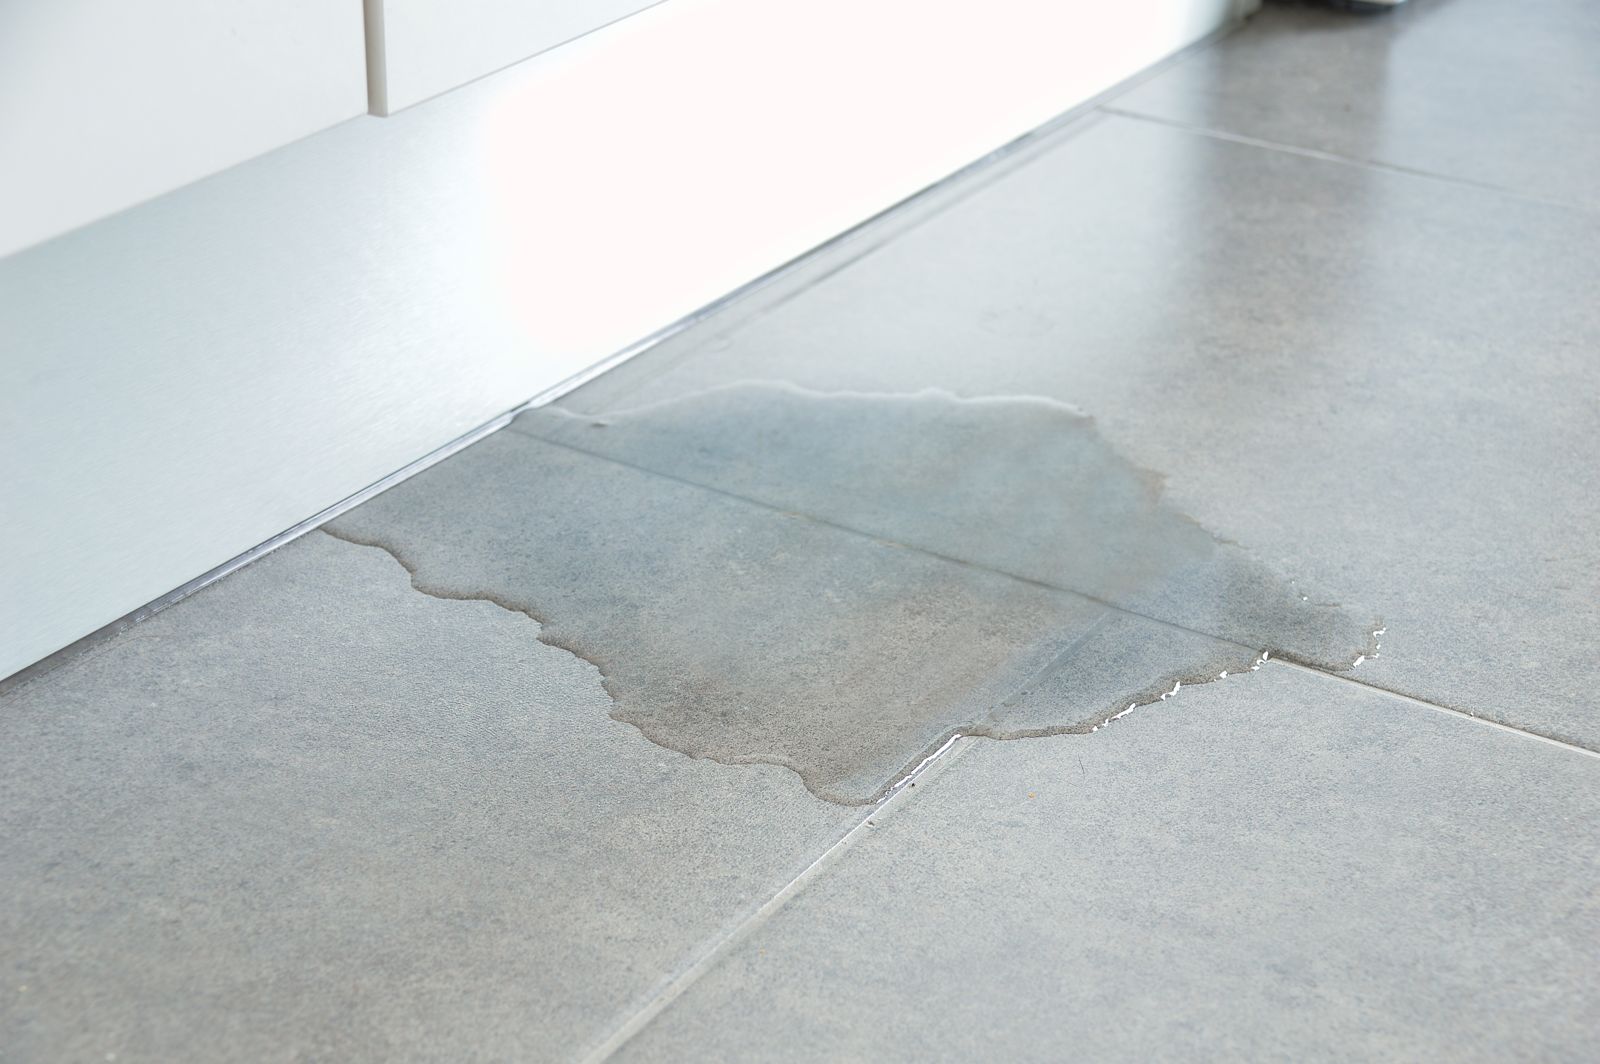
Short answer: A water damage restoration company (also called a water-mitigation company) extracts the water and dries the home. Whether insurance pays for that work depends on your policy: what caused the water, and the limits and deductible that apply. Homeland is a public adjusting firm, not a restoration company. We don’t extract water or rebuild; we work for you on the insurance claim. Call Homeland first, 24/7, at (305) 783-3777: we document the loss and report the claim to your insurer for you.
Have a property claim anywhere in Florida? A licensed Homeland public adjuster comes to you within hours — no need to visit an office. Call (305) 783-3777 (Florida) or (732) 517-3777 (New Jersey), 24/7.
What a water damage restoration company does
- Stops further damage: extracts standing water and removes materials that can’t be dried.
- Dries the structure with air movers and dehumidifiers and records moisture readings until it is dry.
- Later, a contractor repairs and rebuilds what was removed.
Your policy expects this. Most homeowners policies list the same duties after a loss: protect the property from further damage, and keep a record of what you spend doing it.
Document before anything is removed
- Wide photos of each affected room, then close-ups; a slow video walk-through with the date.
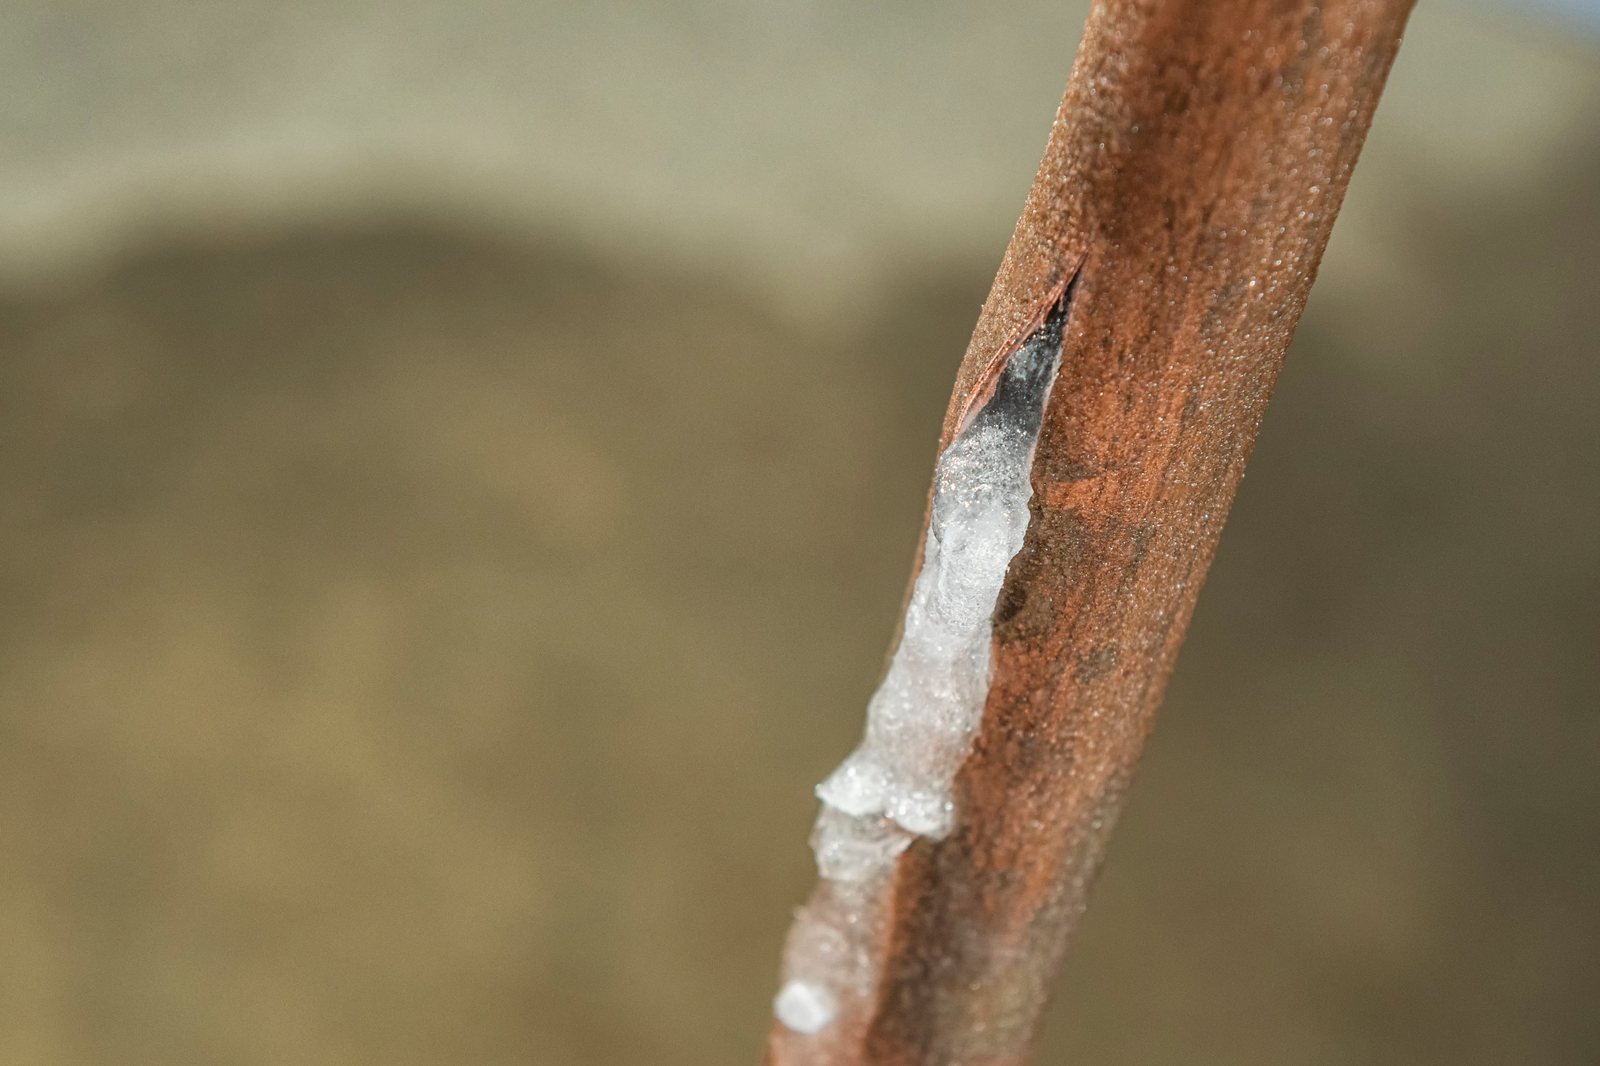
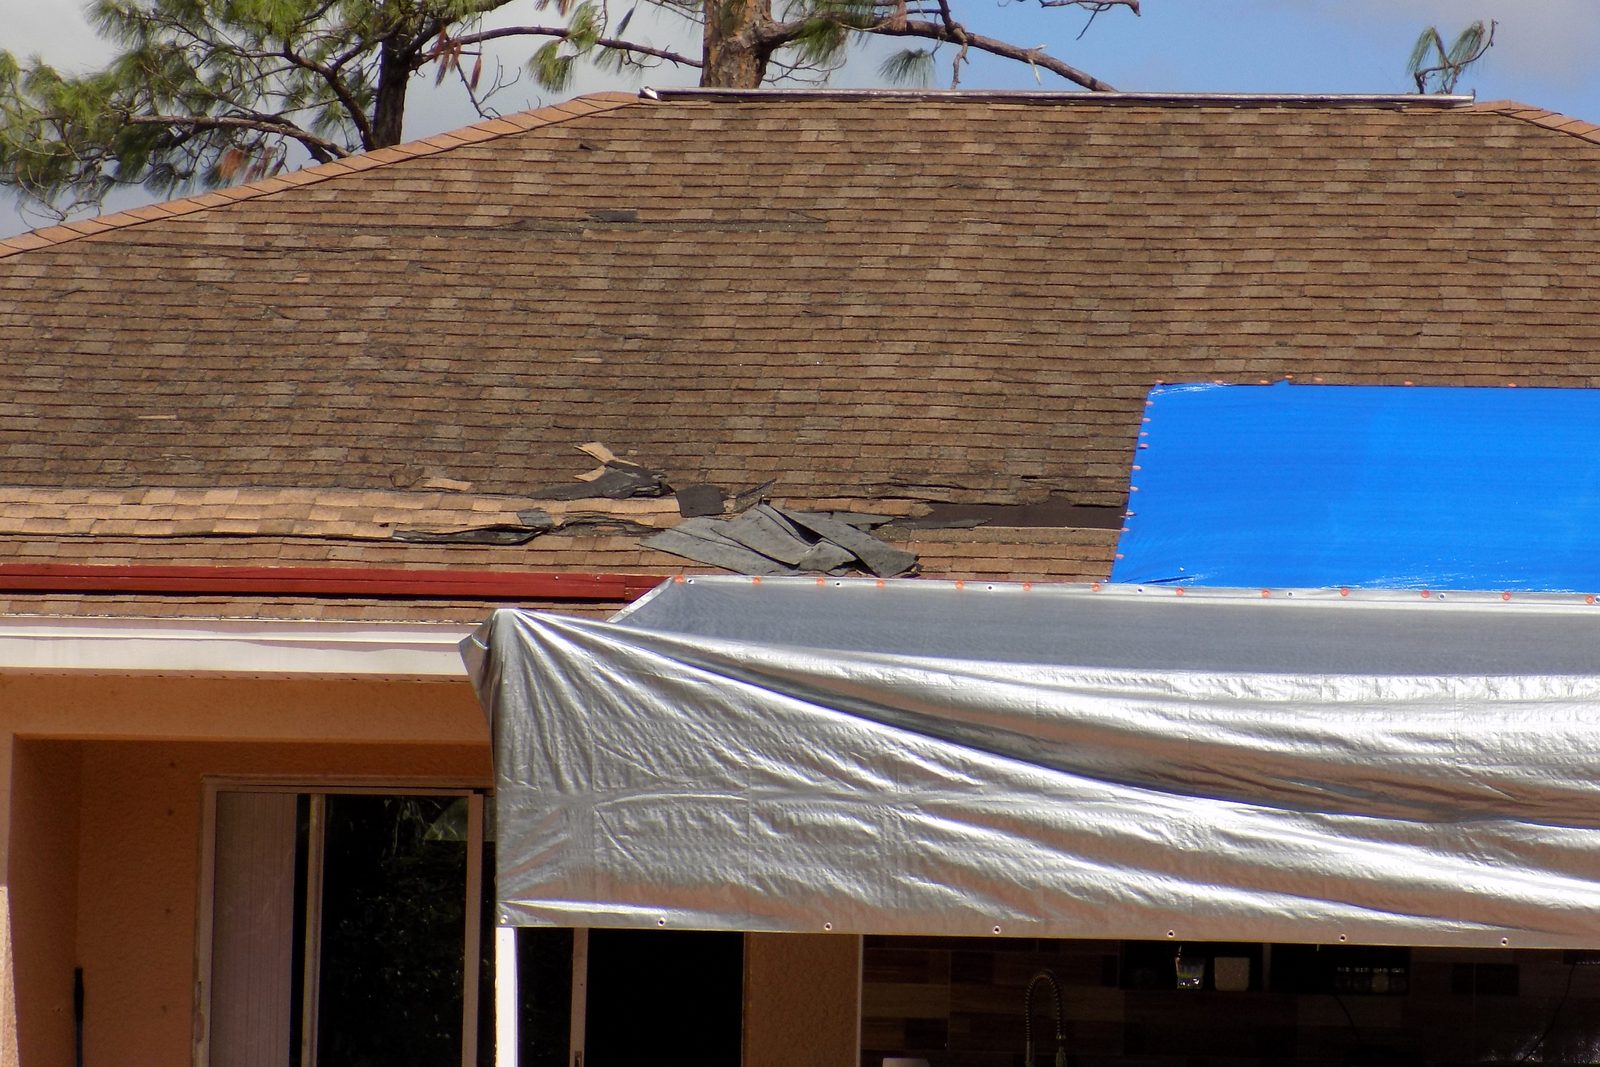
- The source of the water: the pipe or fitting, the appliance, the AC drain line or pan, the opening in the roof.
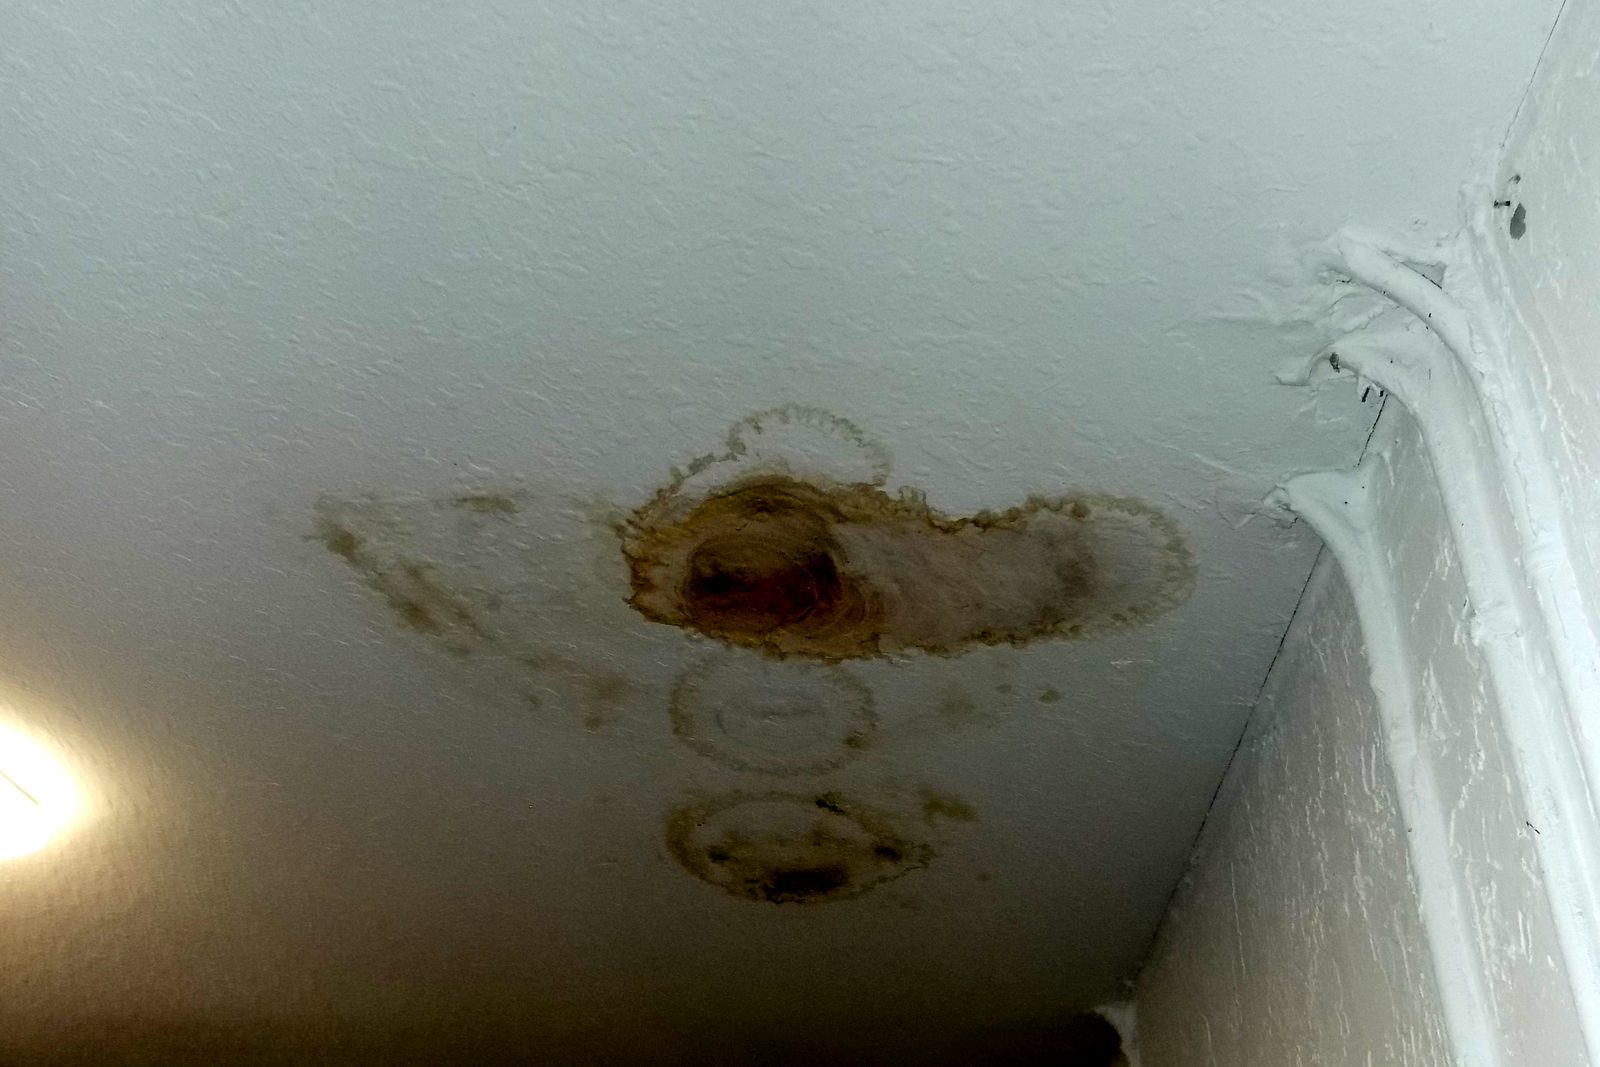
- Water lines on walls, ceilings, cabinets and flooring, and damaged belongings before they are thrown out.
- When you found the water, and every invoice, moisture reading and drying log from the companies that helped.
What to get in writing from the restoration company
- A written scope of work and price before the work starts.
- Daily moisture readings and drying logs, and photos of everything that is removed.
- An itemized invoice, not a single lump sum.
- Read every page before you sign. A work authorization is one thing; a document that transfers your claim rights or your insurance payment to the company is another.
In Florida, a contractor can’t negotiate your claim unless also licensed as a public adjuster (§626.854(16)).
Who pays, and the limits to check
- The cause decides coverage. Sudden and accidental water, such as a burst pipe, is treated differently from a long-term leak: see long-term leak denials.
- Some Florida policies cap water damage: see Florida’s $10,000 water damage sublimit.
- Mold often has its own cap: see mold claims capped at $10,000.
- Water that rises from outside is flood, under a separate flood policy: see flood damage restoration and cleanup.
Who does what
| Who | What they do |
|---|---|
| Plumber, AC technician or roofer | Stops the source and repairs the cause. Ask for a written note of what failed. |
| Water-mitigation company | Extracts water, dries the structure and records moisture readings. |
| Licensed public adjuster (Homeland) | Works for you: documents the whole loss, writes the itemized estimate, presents and negotiates the claim. |
| The insurer’s adjuster | Adjusts the claim for the insurance company. |
Deadlines that matter
- Report a new claim within 1 year after the date of loss; a supplemental claim within 18 months (§627.70132).
- The insurer must pay or deny within 60 days after it receives notice of the claim, unless factors beyond its control cause the delay (§627.70131(7)(a)).
More detail: who to call first after a pipe burst, AC leak or roof leak · burst pipes · AC leaks · water damage claims.
Frequently asked questions
Is Homeland a water damage restoration company?
Can I start cleanup before the insurer inspects?
Do I have to use the restoration company the insurer suggests?
Does Homeland come to me?
Sources (checked November 19, 2026)
- Fla. Stat. §627.70132: notice deadlines for new, reopened and supplemental claims
- Fla. Stat. §627.70131: insurer deadlines, including pay or deny within 60 days ((7)(a)) and inspection within 30 days ((3)(b))
- Fla. Stat. §626.854: public adjuster rules, fee caps and cancellation rights
This article is for general information only and is not legal or insurance advice. Statutes, regulations and policy wording change, and how they apply depends on your own policy and the facts of your claim. Homeland Public Adjusters is a public adjusting firm, not a law firm.
- Insurance Denied Your Property Claim in Florida? What to Do Next
- Public Adjuster or Lawyer for a Florida Insurance Claim?
- Pipe Burst, AC Leak or Roof Leak in Florida: Who to Call First
- Flood Damage Restoration in Florida: Protect the Claim First
- Kitchen & Grease Fire Insurance Claims
- Neighbor's Tree Fell on My House: Who Pays?
 Nelson Avila
 Yeni Martinez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Denied and Underpaid Claims page.