The Insurer Wants Its Own Contractor: Managed Repair in Florida and New Jersey

Homeland Public Adjusters · Last reviewed: October 2026
Short answer: Managed repair lets the insurer choose the contractor and repair the damage instead of paying you to repair it. In Florida it exists only where your policy includes it, usually as an endorsement, and no Florida statute sets its rules. In New Jersey, regulations bar insurers from requiring repairs by a particular contractor as a condition of payment.
Where managed repair comes from in Florida
We found no Florida statute that creates or regulates managed repair programs. They come from policy endorsements filed with and approved by the Office of Insurance Regulation, Florida statutes only mention the right to repair in passing:
- The Homeowner Claims Bill of Rights (§627.7142), which the insurer must provide within 14 days of the first claim communication, tells policyholders to confirm any managed repair provisions or optional preferred vendors before signing repair contracts.
- §627.7011(6)(e) says the replacement cost statute does not prohibit an insurer from exercising its right to repair.
What still applies
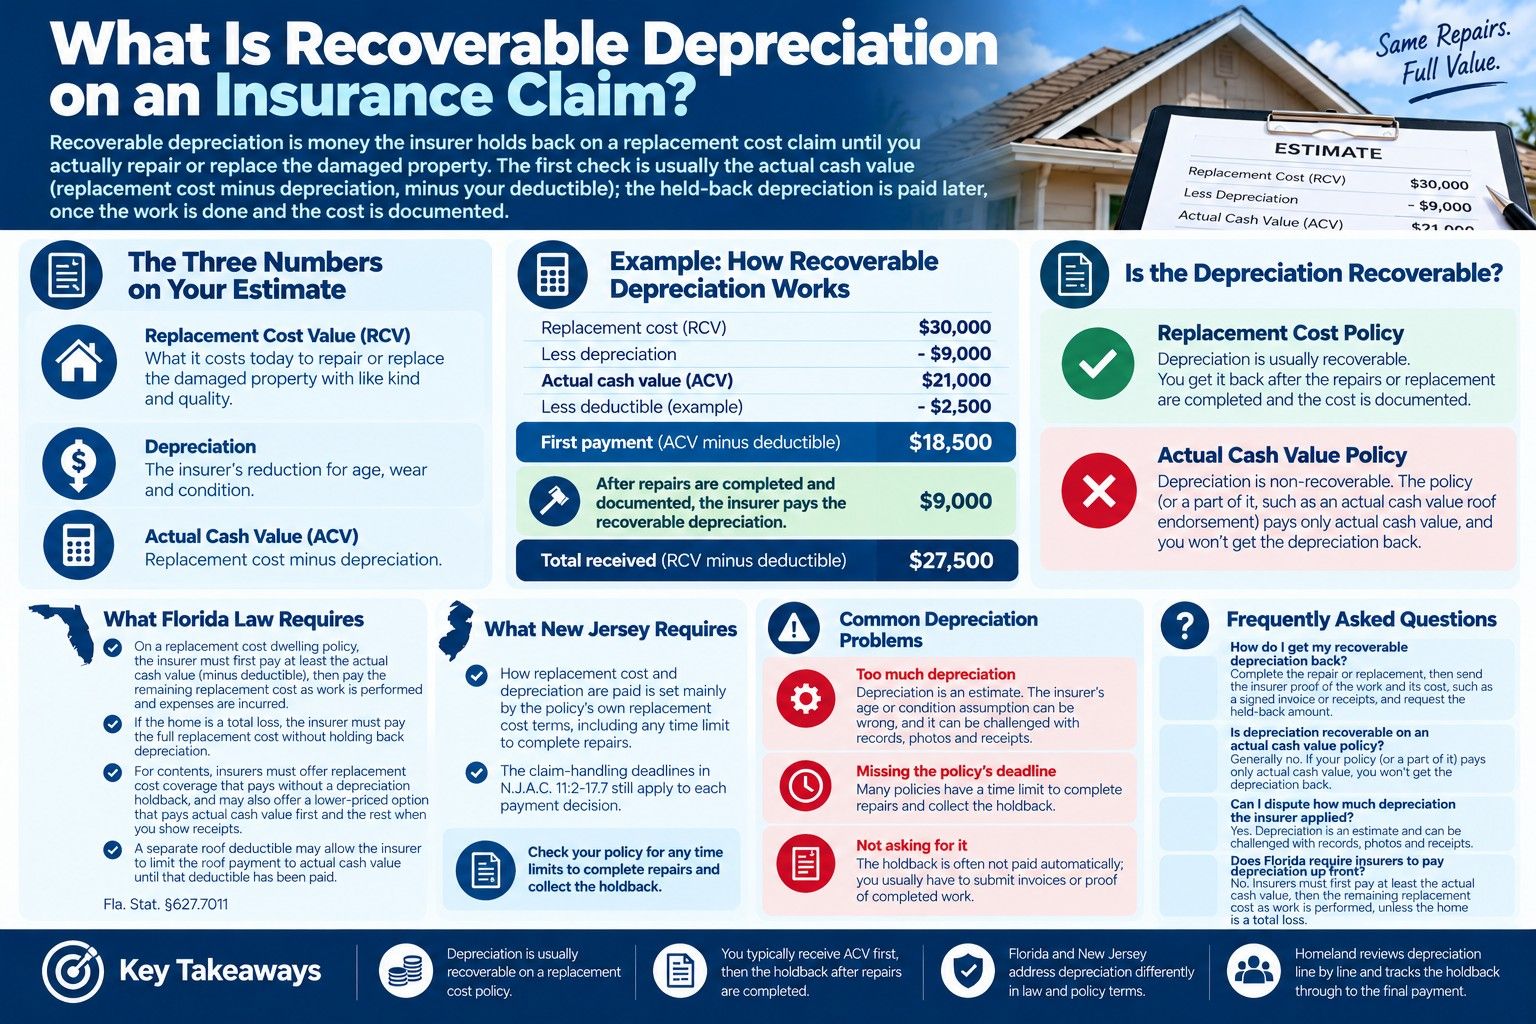
Under §627.7011(3)(a), the insurer generally must first pay at least the actual cash value of a covered dwelling loss, then the rest as repairs are done, and for a total loss it must pay replacement cost without holding back depreciation. A managed repair election also doesn’t answer the question of scope: what is damaged and what the repair must include is still the core of the claim.
Questions to ask
- Does my policy actually have a managed repair endorsement? Check the declarations page and endorsements list
- When must the insurer elect to repair, and how is that communicated?
- Who warrants the work, and what happens if the repair is incomplete or defective?
- What scope of work did the insurer approve, and does it include everything damaged?
- What happens to emergency services and repairs already done?
New Jersey is different
N.J.A.C. 11:2-17.10(a)6 says an insurer shall not require, as a condition to payment of claims, that repairs be made by a particular contractor, unless it is exercising a repair right in the policy.
Frequently asked questions
Can my Florida insurer make me use its contractor?
Is there a Florida law on managed repair?
Can a New Jersey insurer require a particular contractor?
Does managed repair change what is damaged?
Call Homeland first. Before you answer the insurer, sign anything or accept a final number, call us 24/7 at (305) 783-3777 in Florida or (732) 517-3777 in New Jersey. We read the letter against your policy, document the loss and present the claim for you. Hablamos español.
This article is for general information only and is not legal or insurance advice. Statutes, regulations and policy wording change, and how they apply depends on your own policy and the facts of your claim. Homeland Public Adjusters is a public adjusting firm, not a law firm.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Denied and Underpaid Claims page.