Claim Closed as “Below Your Deductible”? How to Check the Math

Homeland Public Adjusters · Last reviewed: October 2026
Short answer: A “below deductible” letter means the insurer’s own estimate of your covered damage came out lower than your deductible, so it pays nothing. It is a math result, not a finding that the damage isn’t covered. If the estimate left damage out, the answer changes.
How common is it?
Very. In OIR’s Hurricane Milton claims data (as of December 9, 2025), “damage below deductible” was the single largest reason listed for claims closed without payment: 51,625 claims across all lines of business. In its April 9, 2025 OIR release, OIR said below-deductible decisions were 41% of Milton claims closed without payment, and 33% for Hurricane Helene.
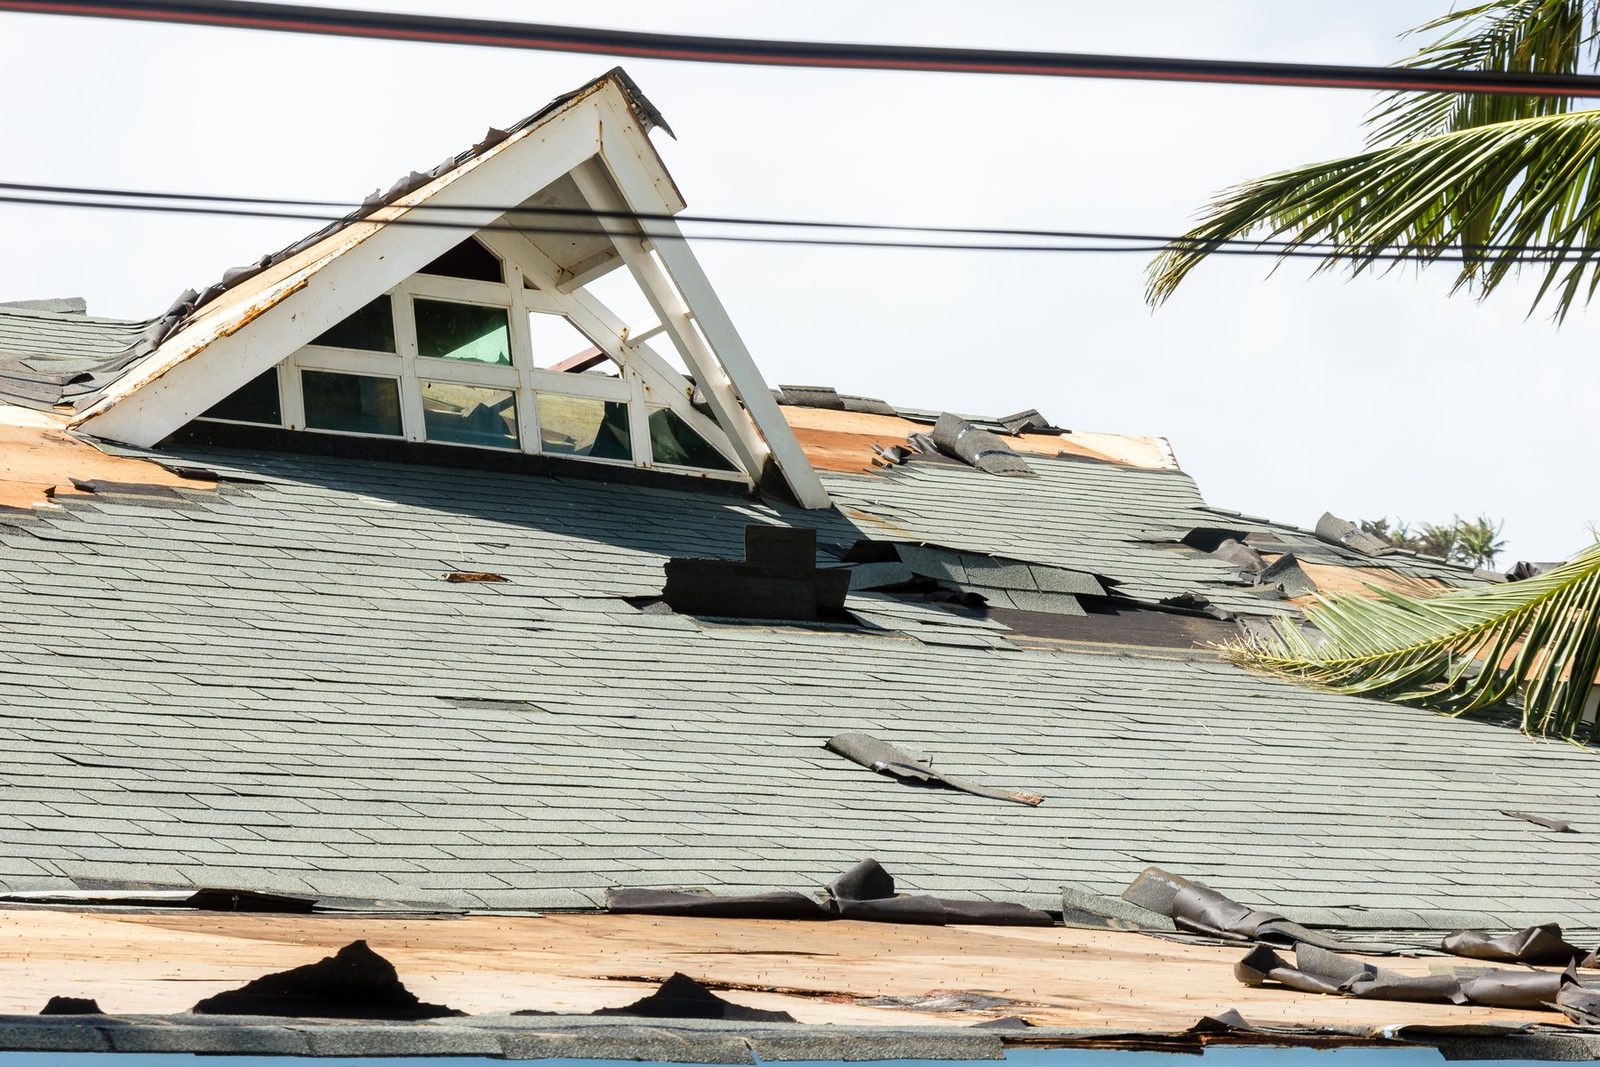
Why the math can be wrong
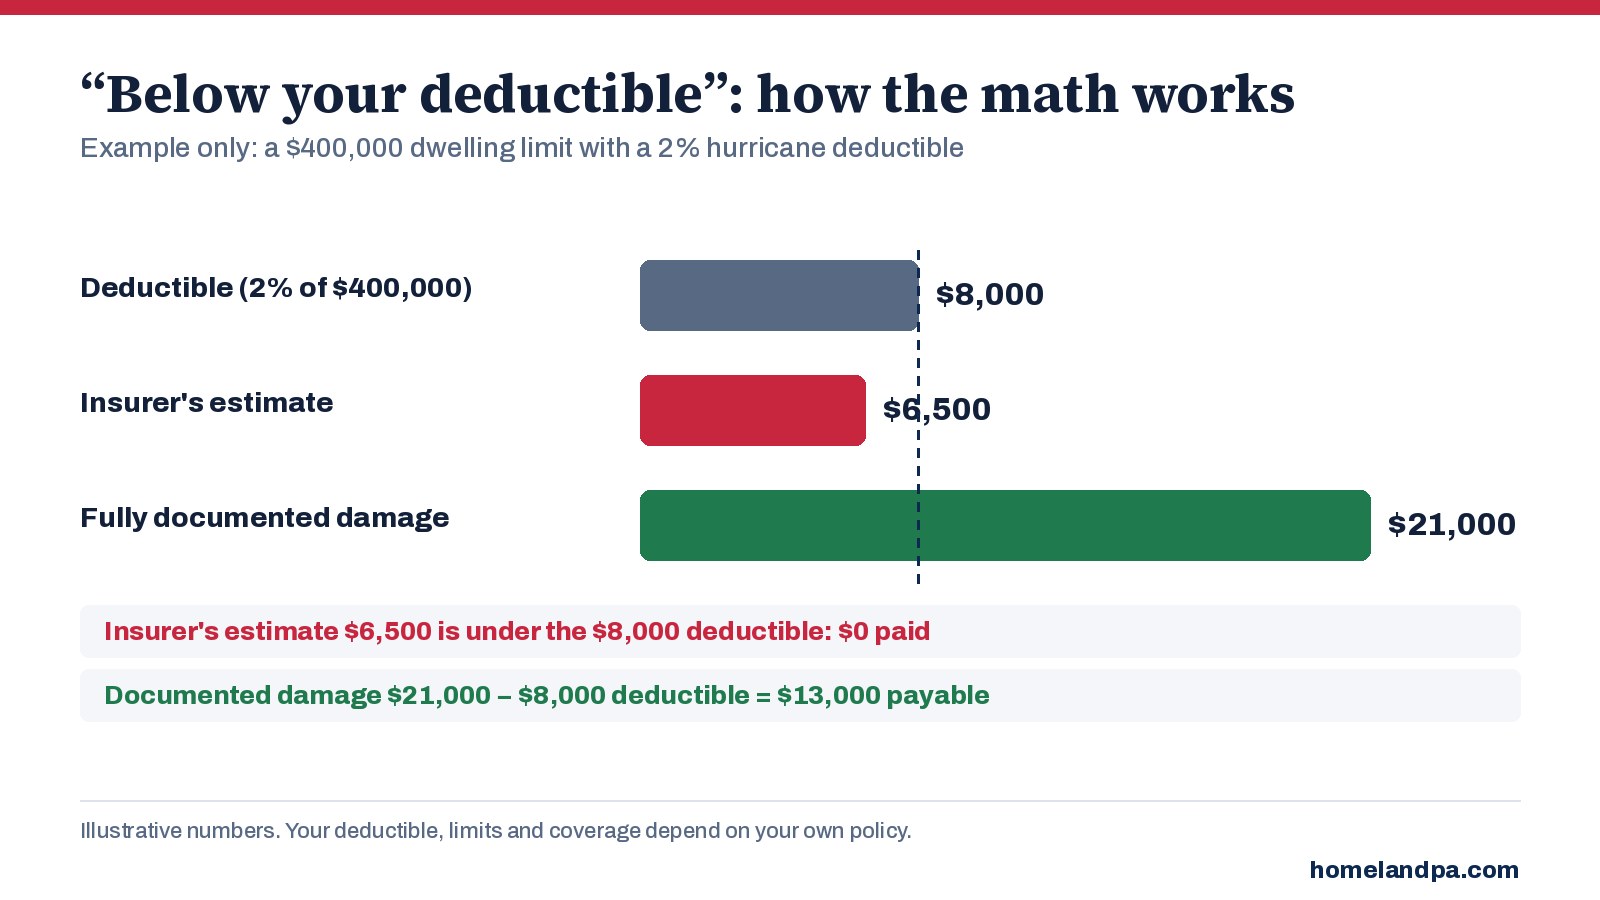
The deductible is fixed by your policy. A Florida hurricane deductible is usually a percentage of the dwelling limit, so on a $400,000 home a 2% deductible is $8,000 (see how hurricane deductibles work). The estimate is the part that moves. Items we often find missing from a low estimate:
- Interior damage: ceilings, insulation, drywall and flooring wet by water that came in through storm openings
- The full roof area, not only the most visible slope or a handful of shingles or tiles
- Repairs the building code requires, when the policy includes ordinance or law coverage
- Matching and the cost of tearing out and replacing materials to reach the damage
- Contents, fences, screen enclosures and other structures that the estimate never listed
What Florida and New Jersey rules give you
Florida. Under Fla. Stat. §627.70131(3)(e), the insurer must send you a copy of any detailed estimate within 7 days after it is generated, with no request needed, and any later payment or denial must come with a written explanation of “the basis in the insurance policy, in relation to the facts or applicable law” (7)(a). A claim closed this way can be reopened within 1 year of the date of loss, and a supplemental claim made within 18 months (Fla. Stat. §627.70132). For a hurricane, the date of loss is the landfall date.
New Jersey. N.J.A.C. 11:2-17.10(a)15 requires the insurer to give you a copy of its estimate before negotiations begin, and any depreciation must be itemized by dollar amount under 17.10(a)2.
What you can do
Get the estimate and compare it room by room with what you actually see. Document what is missing with dated photos, measurements and moisture readings. Present it as a reopened or supplemental claim within the deadlines, and if the dispute is only about the amount, look at appraisal or Florida’s free DFS mediation (every option, compared).
Frequently asked questions
Is a below-deductible letter a denial?
Can I reopen a claim closed below the deductible?
Does the hurricane deductible apply to every hurricane claim?
Do I have to pay to have the estimate checked?
Call Homeland first. Before you answer the insurer, sign anything or accept a final number, call us 24/7 at (305) 783-3777 in Florida or (732) 517-3777 in New Jersey. We read the letter against your policy, document the loss and present the claim for you. Hablamos español.
This article is for general information only and is not legal or insurance advice. Statutes, regulations and policy wording change, and how they apply depends on your own policy and the facts of your claim. Homeland Public Adjusters is a public adjusting firm, not a law firm.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Denied and Underpaid Claims page.