How Much Does a Public Adjuster Cost in Florida and New Jersey?

Homeland Public Adjusters · Last reviewed: October 2026
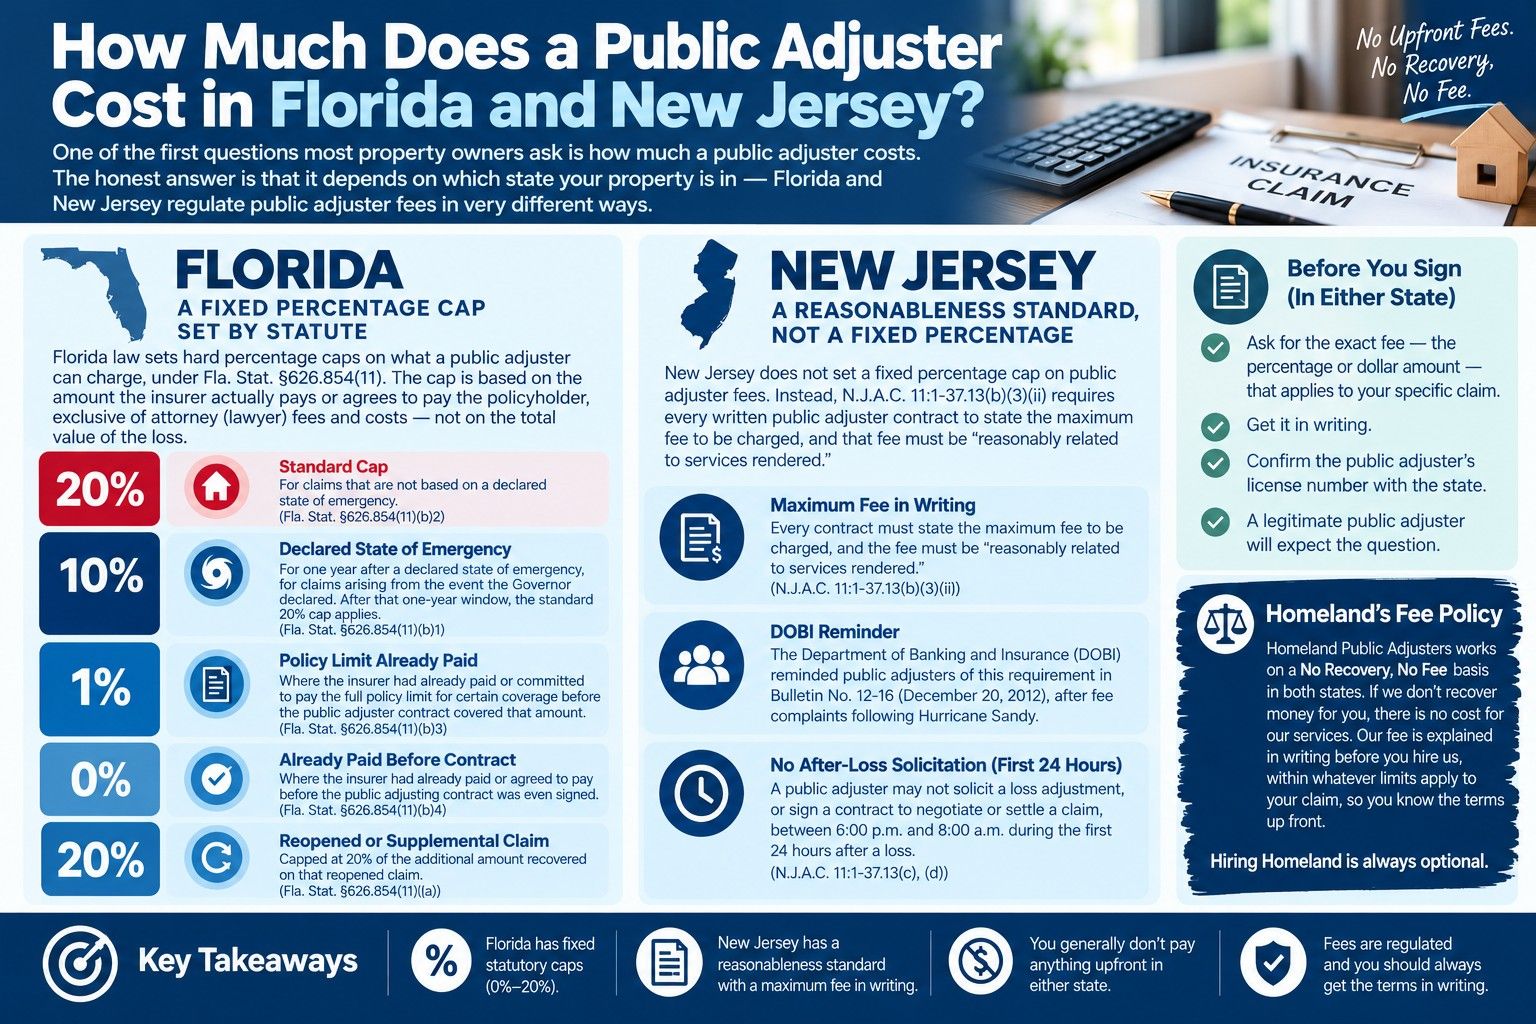
One of the first questions most property owners ask is how much a public adjuster costs. The honest answer is that it depends on which state your property is in — Florida and New Jersey regulate public adjuster fees in very different ways.
Have a property claim? Florida: a licensed Homeland public adjuster comes to your property within hours. New Jersey: statewide. No need to visit an office. Call (305) 783-3777 (Florida) or (732) 517-3777 (New Jersey), 24/7.
Florida: a fixed percentage cap set by statute
Short answer: Florida caps public adjuster fees by statute (Fla. Stat. §626.854(11)); the caps are on our fees page. New Jersey sets no fixed percentage; the written contract must state the maximum fee, and it must be reasonably related to the services rendered.
Florida law sets hard percentage caps on what a public adjuster can charge, under Fla. Stat. §626.854(11). The cap is based on the amount the insurer actually pays or agrees to pay the policyholder, exclusive of attorney (lawyer) fees and costs — not on the total value of the loss.
The caps differ for standard claims, for claims from a declared state of emergency during the year after the declaration, and where the insurer pays, or agrees to pay, before or soon after the contract is signed (§626.854(11)(b)). On a reopened or supplemental claim, the fee can’t be based on earlier payments (§626.854(11)(a)). The figures for each case are on our fees page.
Three more rules protect the policyholder: the fee can’t be based on the deductible (§626.854(11)(c)); it can’t be based on additional living expenses unless you agree in a separate written agreement (§626.854(11)(d)); and the rate can’t go up just because the claim goes to litigation (§626.854(11)(e)).
Your right to cancel in Florida. You can cancel a public adjuster contract without penalty or obligation within 10 days after signing it. If the contract was signed for a loss from a declared state of emergency, you can cancel within 30 days after the date of loss or 10 days after signing, whichever is longer. You can also cancel if the public adjuster doesn’t give you and your insurer a written estimate within 60 days, unless the delay is beyond the adjuster’s control. The contract must print this notice in bold 18-point type just above your signature (§626.854(7) and (12)).
New Jersey: a reasonableness standard, not a fixed percentage
New Jersey does not set a fixed percentage cap on public adjuster fees. Instead, N.J.A.C. 11:1-37.13(b)(3)(ii) requires every written public adjuster contract to state the maximum fee to be charged, and that fee must be “reasonably related to services rendered.” The Department of Banking and Insurance (DOBI) has reminded public adjusters of this requirement directly, in Bulletin No. 12-16 (December 20, 2012), after fee complaints following Hurricane Sandy.
New Jersey regulation also protects against high-pressure, after-loss solicitation: a public adjuster may not solicit a loss adjustment, or sign a contract to negotiate or settle a claim, between 6:00 p.m. and 8:00 a.m. during the first 24 hours after a loss (N.J.A.C. 11:1-37.13(c), (d)).
Homeland's fee policy
Homeland Public Adjusters works on a No Recovery, No Fee basis in both states: if we don't recover money for you, there is no cost for our services. Our fee is explained in writing before you hire us, within whatever limits apply to your claim, so you know the terms up front.
The same fee rules apply whether your claim is in Miami, Tampa or Newark.
Frequently asked questions
What is the maximum public adjuster fee in Florida?
Does New Jersey cap public adjuster fees?
This article is for general information only and is not legal or insurance advice. Statutory and regulatory fee limits can change, and how they apply depends on the facts of your specific claim — always review your own contract or speak with a licensed public adjuster about your situation.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Public Adjuster Near Me page to get connected with the Homeland adjuster covering your area.