
Wind Mitigation, 4-Point and Roof Inspections in Florida: What Each One Is and When You Need It
Homeland Public Adjusters · Last reviewed: October 2026
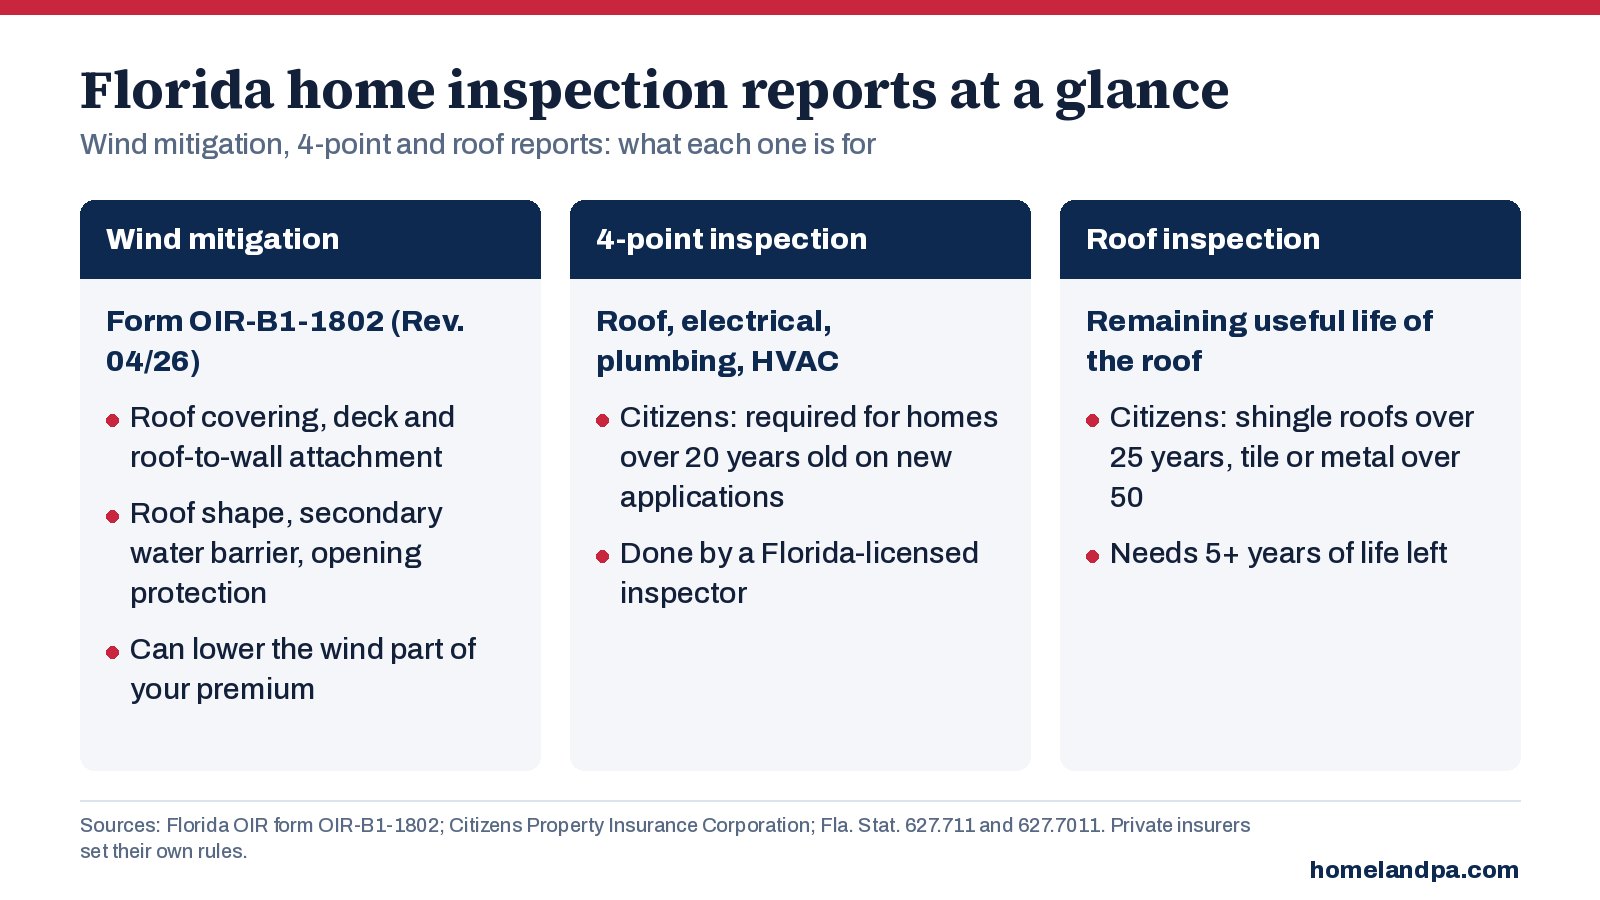
Short answer: a wind mitigation inspection documents the features that help your home resist wind, and it can lower the wind part of your premium. A 4-point inspection checks the roof, electrical, plumbing and heating and air conditioning systems, and insurers often ask for one before they insure an older home. A roof inspection (often called a roof certification) estimates how many years of useful life the roof has left. They are three different reports, done for three different reasons.
Have a property claim anywhere in Florida? A licensed Homeland public adjuster comes to you within hours — no need to visit an office. Call (305) 783-3777 (Florida) or (732) 517-3777 (New Jersey), 24/7.
Wind mitigation inspection (form OIR-B1-1802)
Florida uses one statewide form, the Uniform Mitigation Verification Inspection Form, OIR-B1-1802. The current version is Rev. 04/26, required for inspections done on or after April 1, 2026; it adds the FORTIFIED Roof, Silver and Gold designations. Citizens Property Insurance Corporation still accepts the prior version (Rev. 01/12) if it was completed within five years before April 1, 2026 and the home has had no structural changes.
The inspector records the features the form asks about, including:
- the roof covering and the building code it meets,
- how the roof deck is attached,
- how the roof is tied to the walls (toe nails, clips, single or double wraps),
- the roof shape (for example, hip roofs),
- a secondary water barrier under the roof covering, and
- protection over windows, doors and other openings.
Florida law requires insurers’ rate filings to include actuarially reasonable discounts for these features (§627.0629, Florida Statutes), and since October 1, 2023 insurers must describe their mitigation discounts on their websites. How much you save depends on your insurer and your home.
Who can sign the form (§627.711(2)(a)): a home inspector licensed under §468.8314 who has completed at least 3 hours of hurricane mitigation training and passed a proficiency exam; a building code inspector; a licensed general, building or residential contractor; a professional engineer; a professional architect; or another inspector the insurer recognizes.
4-point inspection
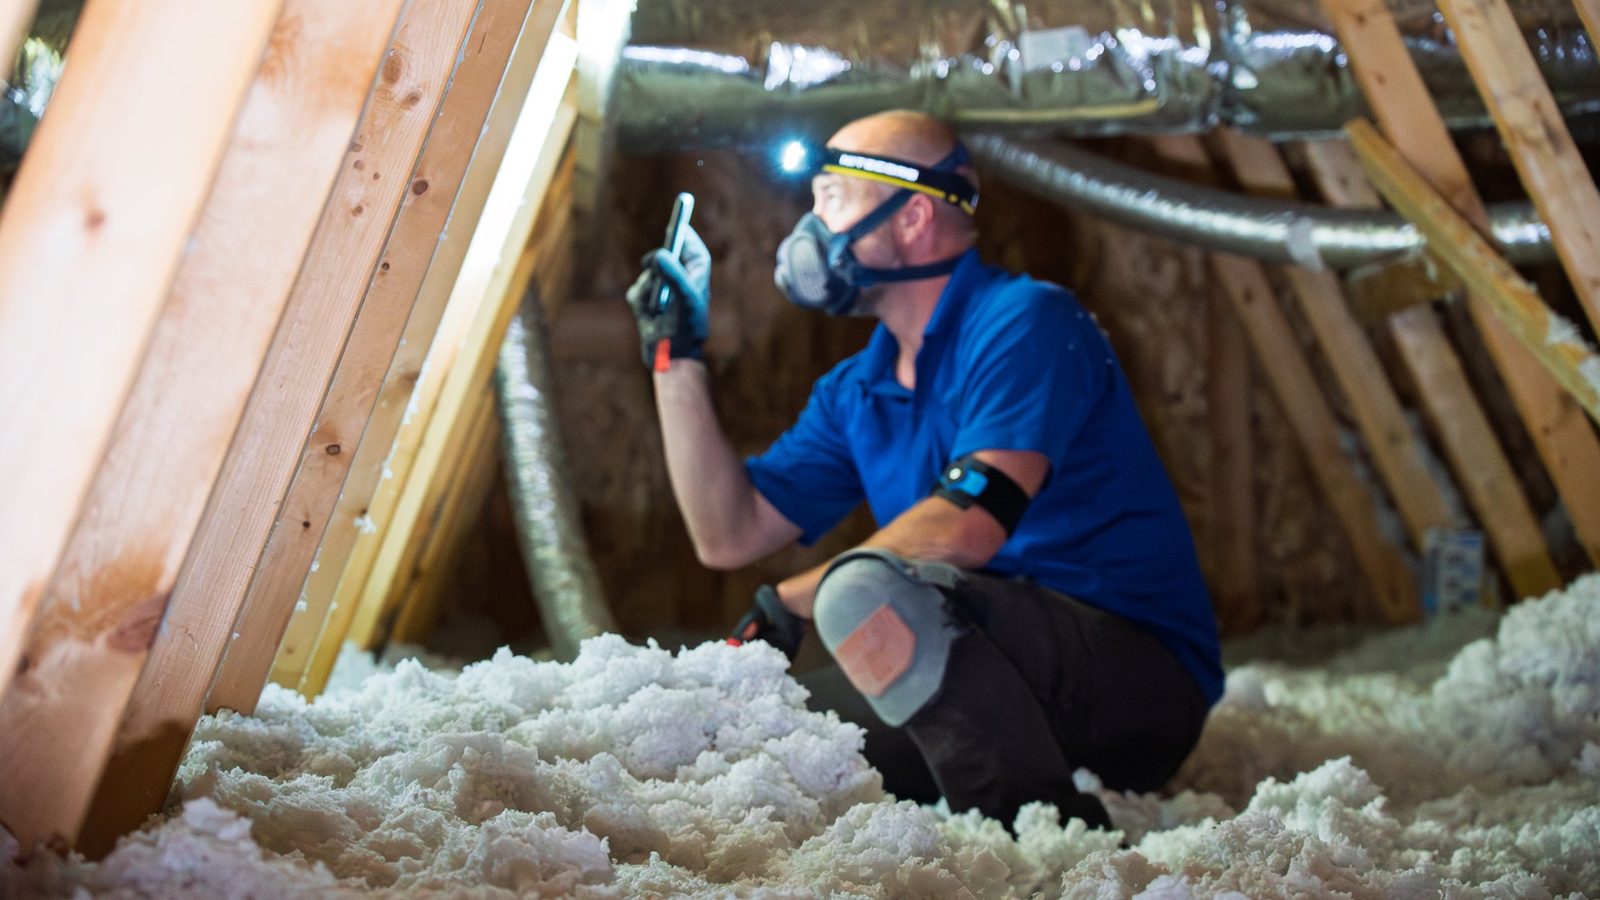
A 4-point inspection is a snapshot of four systems: roof, electrical, plumbing and HVAC. It is an underwriting report, not a wind discount. Citizens requires a 4-point inspection on new property owner, dwelling and mobile home applications for homes more than 20 years old, done by a Florida-licensed inspector. Private insurers set their own age limits.
Roof inspection or roof certification
A roof inspection estimates the remaining useful life of the roof. Citizens asks for documentation showing at least 5 years of remaining life on shingle roofs over 25 years old and on tile, metal and other long-life roofs over 50 years old.
Florida law also limits how insurers can use roof age. For policies issued or renewed on or after July 1, 2022 (§627.7011(5)):
- An insurer may not refuse to issue or renew a homeowners policy solely because the roof is less than 15 years old.
- If the roof is 15 years old or older, you may have it inspected, at your own expense, by an authorized inspector. If the inspection shows at least 5 years of useful life left, the insurer may not refuse to issue or renew solely because of the roof’s age.
How much do these inspections cost?
- Wind mitigation: free for eligible homeowners through the state’s My Safe Florida Home program while it has funding. The free inspection is for site-built, owner-occupied single-family homes and townhouses with a homestead exemption; condos, mobile homes and rentals are not eligible. Check the program site for current status. From a private inspector, Insurify puts the typical cost at about $75 to $150.
- 4-point: the Florida Department of Financial Services’ Four-Point Inspection Guide says a standalone 4-point inspection may typically cost $100 to $300.
- Prices vary by inspector, home size and location, and many inspectors price a wind mitigation and a 4-point together. Ask for the price in writing first.
Why these reports matter on a claim
These reports are dated records of your home’s condition before a loss. After a storm, the insurer may argue that a roof leak is wear and tear, or that damage was already there. A recent wind mitigation, 4-point or roof report, with photos, is evidence of what the home looked like before the storm. Keep a copy of every report. In the free Adjuster Advantage app, the Certificate Pack keeps your reports together, with reminders before they get old.
If your claim has already been denied as wear and tear, read Roof Claim Denied for Wear and Tear or Cosmetic Damage and the glossary entry on the wear and tear exclusion.
Frequently asked questions
What is the difference between a wind mitigation and a 4-point inspection?
Which wind mitigation form is current in Florida?
When does Citizens require a 4-point inspection?
Can my insurer drop me because my roof is old?
How much does a wind mitigation inspection cost in Florida?
Who can do a wind mitigation inspection in Florida?
Sources: Citizens, Uniform Mitigation Verification Inspection Form changes (OIR-B1-1802 Rev. 04/26); Citizens Property Insurance Corporation, inspections; Florida Statutes §627.711; §627.0629; §627.7011; Florida CFO, Four-Point Inspection Guide; My Safe Florida Home, inspection eligibility; Insurify, wind mitigation.
This guide is general information, current as of October 2026. It is not legal or underwriting advice. Each insurer sets its own inspection rules within Florida law; your insurer’s requirements and your policy control.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim Review