Florida Attorney General Investigates “Anti-Public Adjuster” Policy Endorsements

Licensed public adjusters serving Florida & New Jersey
Florida Attorney General James Uthmeier announced on October 20, 2026 that his office is investigating “anti-public adjuster” clauses in property insurance policies, clauses that can let an insurer deny an entire claim if the policyholder hires a public adjuster. The office subpoenaed documents from Velocity Risk Underwriters, LLC, asking for records on its trade group memberships, its communications with other insurers, and any agreements to stop homeowners from using public adjusters. “Homeowners should be allowed to hire an advocate on their side too,” Uthmeier said in the announcement. The release did not cite a specific law.
What the endorsement says
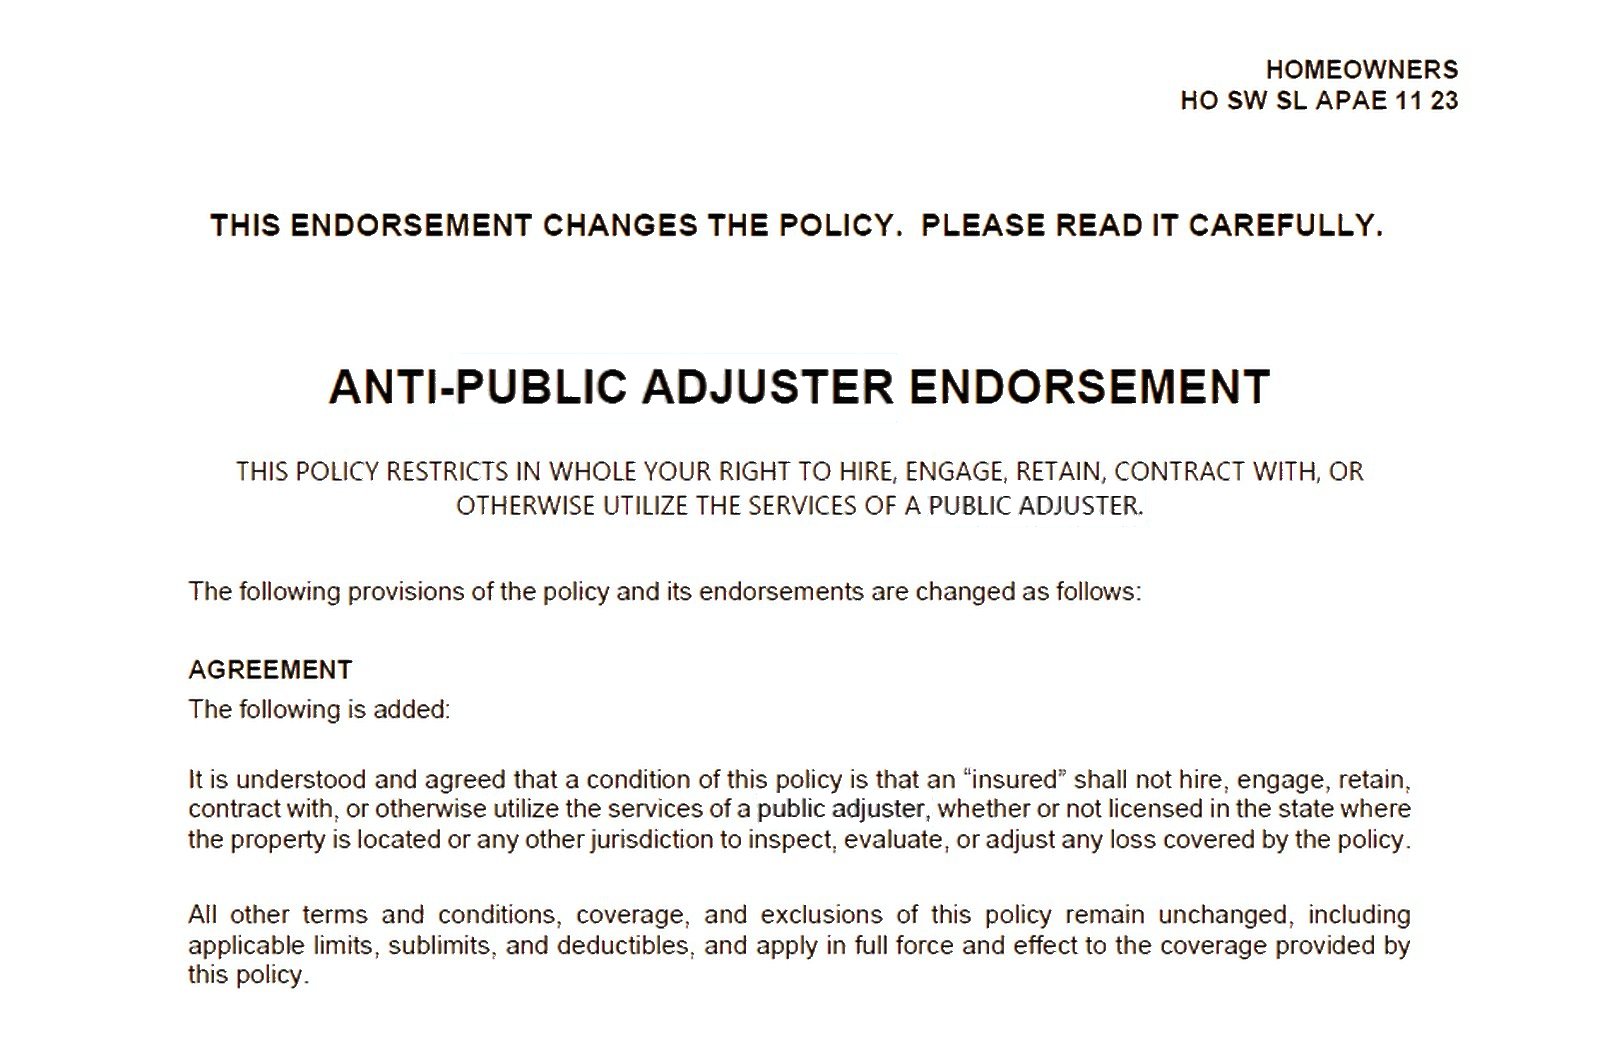
Homeland has reviewed a 2026 Florida homeowners policy written through Swyfft, with Benchmark Specialty Insurance Company, a surplus lines insurer, as the insurance company. Its list of forms includes an “Anti-Public Adjuster Endorsement” (form HO SW SL APAE 11 23). The endorsement states that “this policy restricts in whole your right to hire, engage, retain, contract with, or otherwise utilize the services of a public adjuster,” and adds a condition that an insured “shall not hire, engage, retain, contract with, or otherwise utilize the services of a public adjuster, whether or not licensed in the state where the property is located or any other jurisdiction to inspect, evaluate, or adjust any loss covered by the policy.”
Velocity, in a statement to Insurance Journal, said its policies with this kind of endorsement are “non-admitted, surplus lines property policies” issued to commercial insureds, and that it does not write personal homeowners policies in Florida. The Swyfft policy Homeland reviewed is a homeowners policy.
The lawsuit
In October 2025, the Florida Association of Public Insurance Adjusters (FAPIA) and the National Association of Public Insurance Adjusters sued Velocity in Miami-Dade Circuit Court, alleging the endorsement violates antitrust and unfair trade practice laws. The case is pending. According to Insurance Journal, the complaint also cites American Integrity Insurance, an admitted carrier, which offers a premium discount to policyholders who agree not to use a public adjuster.
Why surplus lines matters
Surplus lines (also called non-admitted, or excess and surplus) insurers cover properties the standard market often won’t, such as older homes, coastal homes and homes with older roofs. Under Florida’s Surplus Lines Law, chapter 627 of the insurance code, the chapter that sets most of the rules for admitted insurers’ policies and rates, does not apply to surplus lines insurance unless a provision says it does (§626.913(4)). That is how provisions like this one can appear in a policy. Surplus lines insurance is also excluded from the Florida Insurance Guaranty Association (FIGA), so if a surplus lines insurer fails, FIGA does not pay its claims (§631.52).
What to do if you have a policy like this
- Look at the “Forms and Endorsements” list on your declarations page for an anti-public adjuster endorsement, or for a premium discount tied to not using one.
- Before you buy or renew, ask your agent whether the policy restricts your right to outside help with a claim, and what a policy without that restriction would cost.
- If you already have a claim and your policy has this endorsement, call us before you sign anything. We’ll review your policy and tell you plainly what we can do, and when a licensed attorney is the right call.
Sources: Florida Attorney General news release, October 20, 2026; Insurance Journal, October 21, 2026; Claims Journal, October 23, 2026; Insurance Journal, November 3, 2025; Florida Statutes §626.913 and §631.52; homeowners policy form HO SW SL APAE 11 23.
This article reports on public records and news coverage as of October 23, 2026. It is general information, not legal advice; the lawsuit and the investigation described are ongoing.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim Review