Code Upgrade and Ordinance-or-Law Coverage: What Commercial Owners Miss

Homeland Public Adjusters · Last reviewed: October 2026
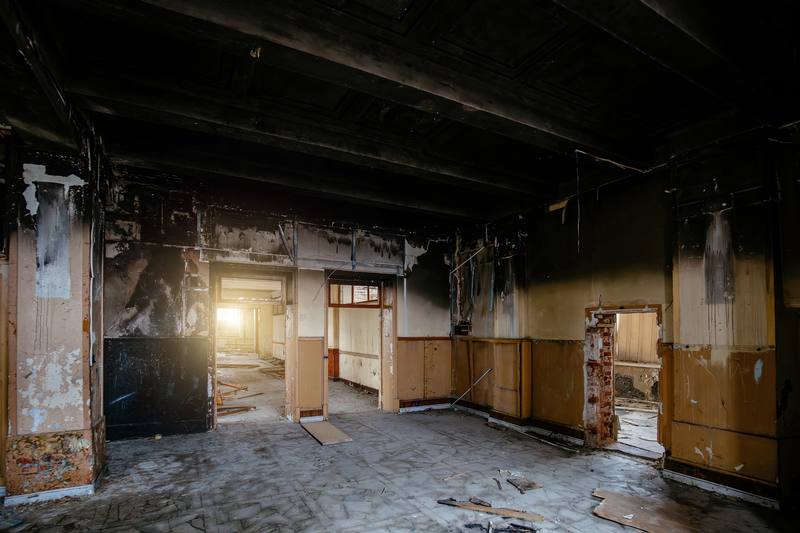
Building codes change over time, and older commercial buildings are frequently grandfathered under the code that existed when they were built, until a significant loss forces a repair, at which point many jurisdictions require the repaired portion, sometimes the whole building, to be brought up to current code.
Why this creates a coverage gap
A standard commercial property policy typically pays to repair what was damaged, back to its condition before the loss, not to upgrade it to current code. If code compliance requires more extensive work than the damage alone would call for, that difference can fall outside standard coverage unless ordinance-or-law coverage is specifically included.
The three pieces ordinance-or-law coverage typically addresses, where it exists
Coverage for the value of the undamaged portion of the building the code now requires you to demolish or alter, the cost of demolishing and clearing that portion, and the increased cost of construction to meet current code on the rebuild.
If you own an older commercial building, confirming whether this coverage exists on your policy is worth a conversation now. If you’re already dealing with a loss and a code-compliance requirement has come up, call Homeland before you speak with the insurance company.
Code-upgrade costs are a recurring issue on commercial claims in Miami Beach, Fort Myers and Hoboken.
Frequently asked questions
What is ordinance-or-law coverage?
Does a standard commercial policy pay for code upgrades after a loss?
Can I add ordinance-or-law coverage after damage happens?
This article is for general information only and is not legal or insurance advice. Every policy and every claim is different — always review your own policy language or speak with a licensed public adjuster about your specific situation.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewThis topic often comes up alongside Documenting a Commercial Property Loss: Where to Start. If your situation involves this kind of loss, see our Business & Commercial page for how Homeland can help with the claim itself.