You Renovated Your Condo. Does Your Policy Know?

Homeland Public Adjusters · Last reviewed: October 2026
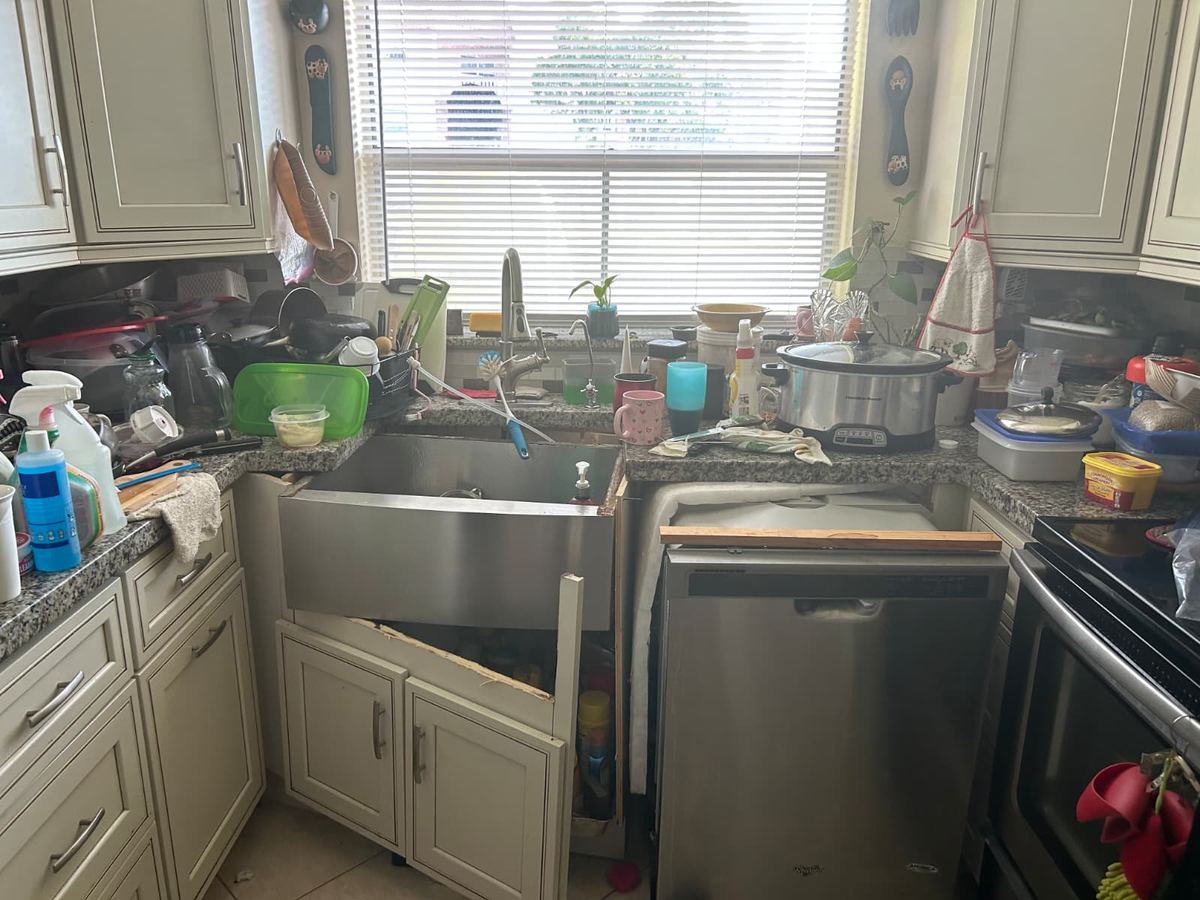
Florida condo owners renovate often — new kitchens, upgraded flooring, converted dens. Most never update their own policy to reflect it. The gap matters at claim time: standard condo unit coverage is frequently written to the building’s original specifications, and anything added beyond that line may not be covered unless the policy’s “additions and alterations” coverage has been specifically increased.
Have a property claim anywhere in Florida? A licensed Homeland public adjuster comes to you within hours — no need to visit an office. Call (305) 783-3777 (Florida) or (732) 517-3777 (New Jersey), 24/7.
The two numbers that matter
Short answer: Condo unit coverage is often written to the building’s original specifications, so a renovation that cost more than your policy’s improvements (additions and alterations) amount can leave the difference out of pocket after a loss. Keep a simple list of what you renovated, when and roughly what it cost.
Most condo unit policies carry a baseline amount for improvements to the unit, separate from the personal-property limit for belongings. If the actual renovation cost is well above that baseline, the difference can come out of pocket after a loss, even on an otherwise valid claim.
What to do now, not after a loss
A simple list — what was renovated, approximately when, and roughly what it cost — kept with your policy documents and updated any time you make a significant change. It won’t fix an existing underinsurance gap by itself, but it gives Homeland something concrete to work with if a loss happens before the policy catches up.
Renovated units are everywhere in Coral Gables, Aventura and Hoboken, and Homeland documents the upgrades a master policy will not cover.
Frequently asked questions
Are my condo renovations covered by my insurance?
What should I keep on file after renovating my condo?
This article is for general information only and is not legal or insurance advice. Every policy and every claim is different — call Homeland. We review your policy language with you at no cost.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewThis topic often comes up alongside When a Neighbor's Unit Catches Fire: Whose Policy Responds?. If your situation involves this kind of loss, see our Condo & HOA Associations page for how Homeland can help with the claim itself.