What Is a Public Adjuster and How to Choose One in Florida or New Jersey

Homeland Public Adjusters · Last reviewed: October 2026
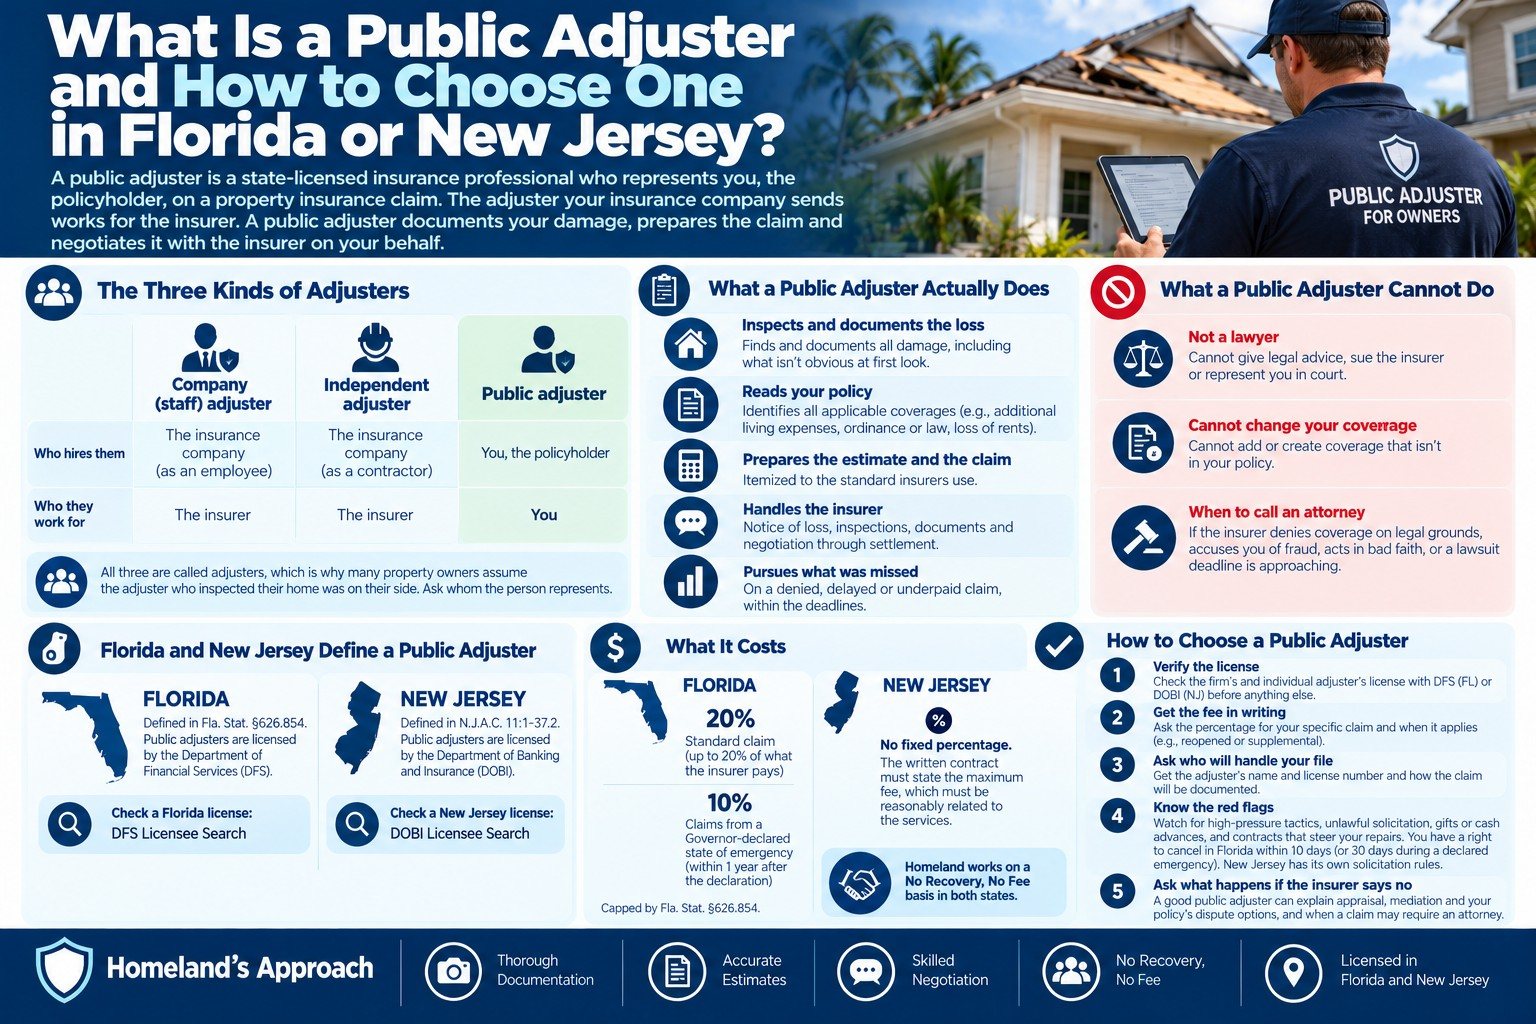
Short answer: A public adjuster is a state-licensed insurance professional who represents you, the policyholder, on a property insurance claim. The adjuster your insurance company sends works for the insurer. A public adjuster documents your damage, prepares and presents the claim, and negotiates it with the insurer on your behalf, usually for a percentage of what you recover.
The three kinds of adjusters
| Adjuster | Who hires them | Who they work for |
|---|---|---|
| Company (staff) adjuster | The insurance company, as an employee | The insurer |
| Independent adjuster | The insurance company, as a contractor, often after a big storm | The insurer |
| Public adjuster | You, the policyholder | You |
All three are called adjusters, which is why many property owners assume the adjuster who inspected their home was on their side. Ask whom the person represents.
How Florida and New Jersey define a public adjuster
Florida's Fla. Stat. §626.854 defines a public adjuster as someone who, for compensation, prepares, completes or files an insurance claim for an insured or third-party claimant, or acts for them in negotiating or settling a covered claim. Public adjusters in Florida are licensed by the Department of Financial Services, and you can check any license on the DFS licensee search.
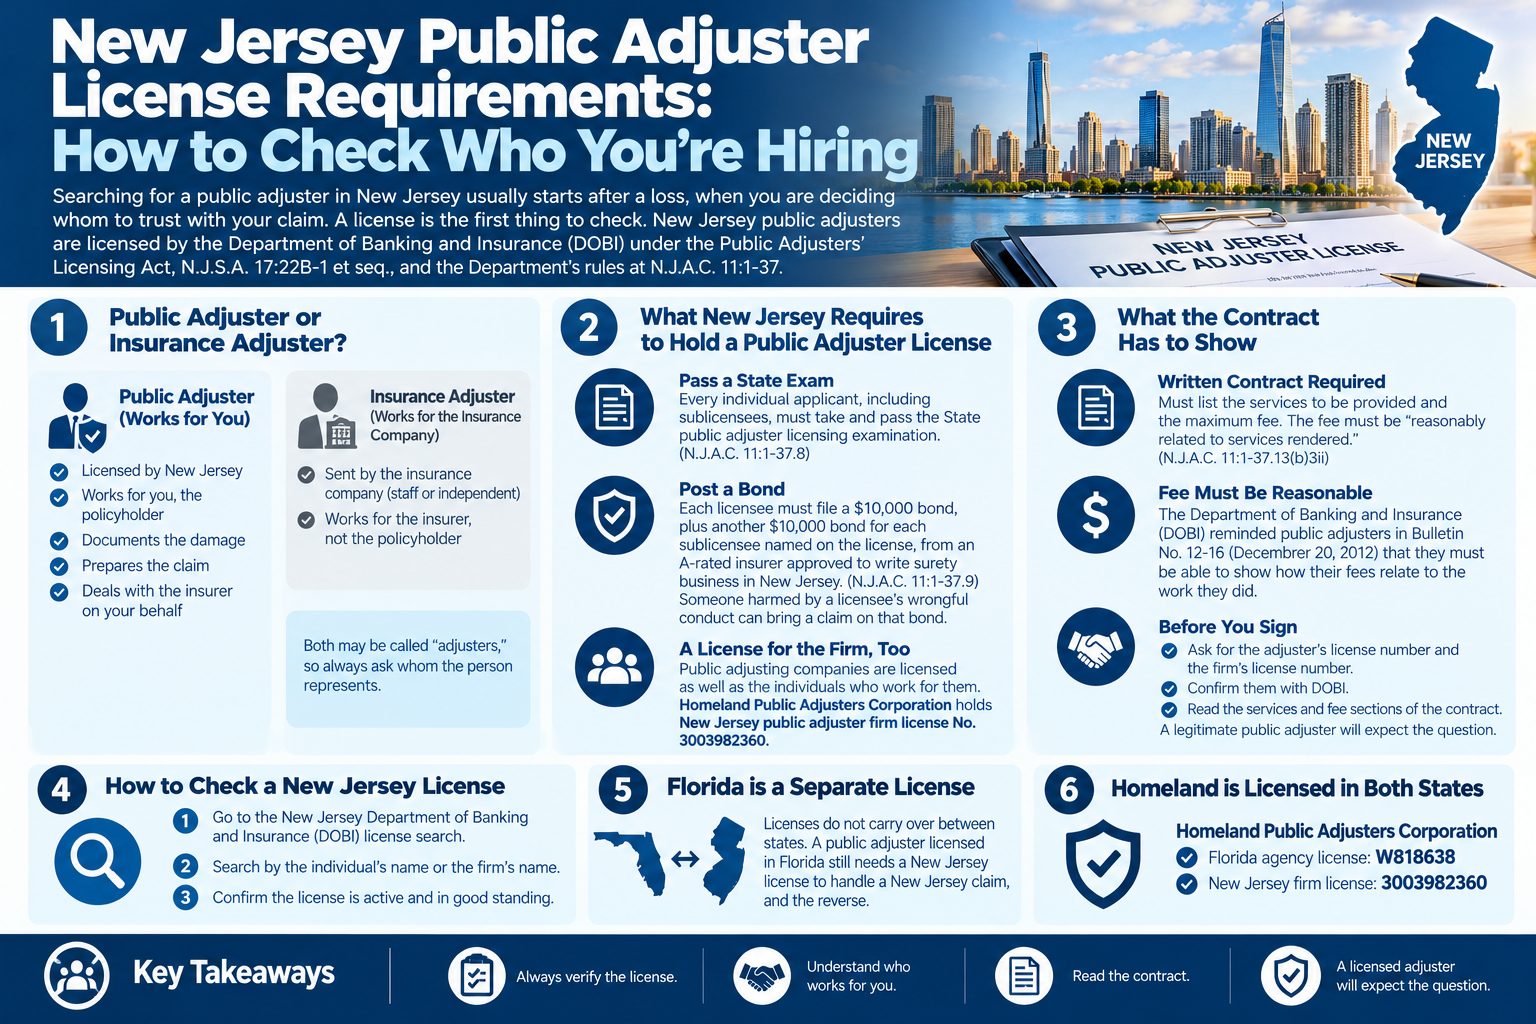
New Jersey's rules (N.J.A.C. 11:1-37.2) define a public adjuster as anyone who, for compensation, acts on behalf of an insured in negotiating or settling a claim under a property insurance policy. New Jersey public adjusters and their firms are licensed by the Department of Banking and Insurance; see our guide to New Jersey public adjuster license requirements.
What a public adjuster actually does
Inspects and documents the loss, including damage that isn't obvious at the first look: water inside walls, roof damage visible only from above, smoke damage rooms away from a fire.
Reads your policy and identifies the coverages that apply, such as additional living expenses, ordinance-or-law coverage or loss of rents.
Prepares the estimate and the claim, itemized to the standard insurers use.
Handles the insurer: the notice of loss, inspections, requests for documents, and the negotiation, through settlement.
Pursues what was missed on a denied, delayed or underpaid claim, within the deadlines.
What a public adjuster cannot do
A public adjuster is not a lawyer and cannot give legal advice, sue the insurer or represent you in court. A public adjuster also cannot change what your policy covers. When a dispute turns on a legal reading of the policy, an accusation of fraud, or bad faith, an attorney is the right call; see every option for a disputed claim, compared.
What it costs
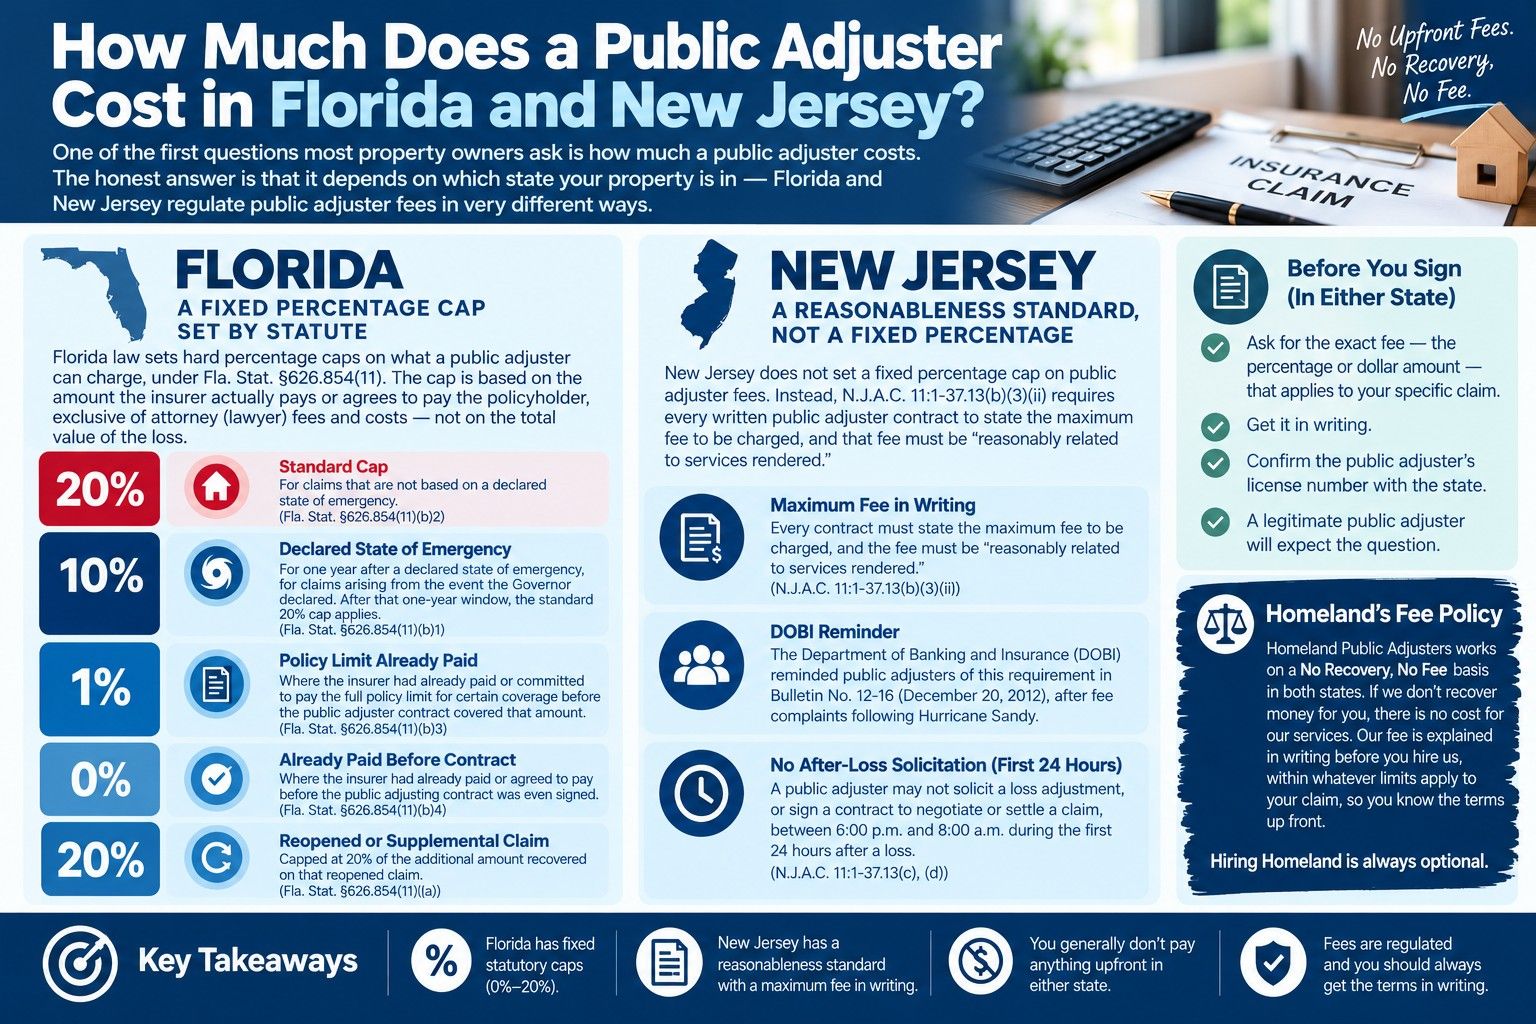
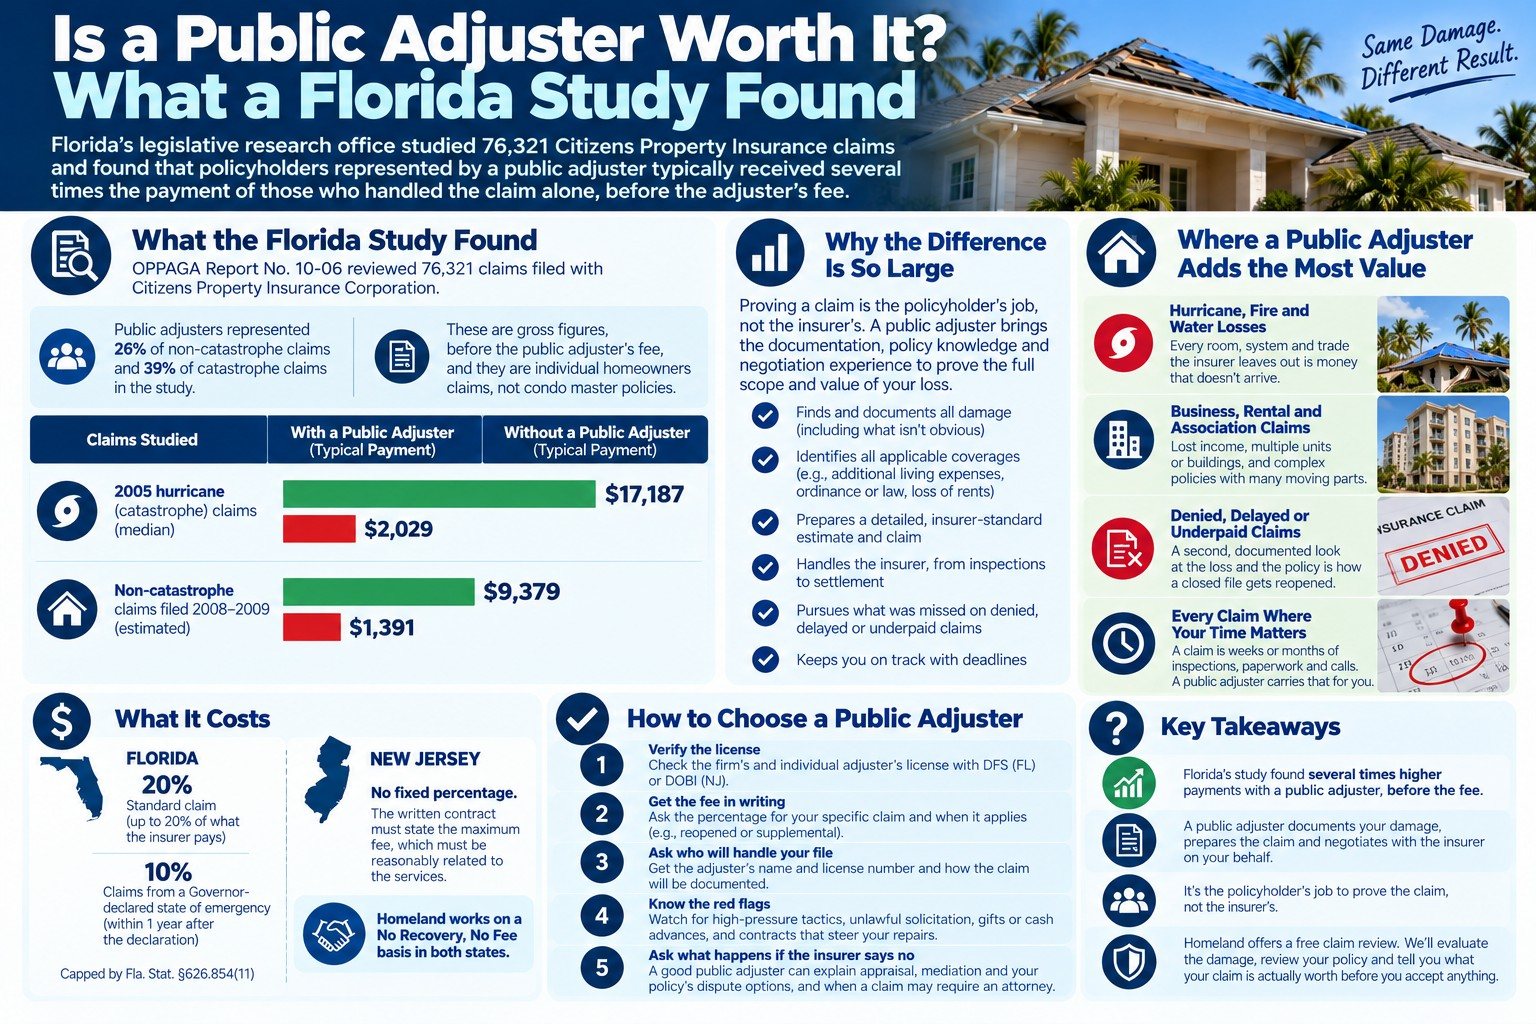
In Florida, fees are capped by §626.854(11): 20% of the insurance payments for a standard claim, and 10% for claims from an event under a Governor-declared state of emergency, for claims made during the year after the declaration. New Jersey has no fixed percentage; the written contract must state the maximum fee, which must be reasonably related to the services. Details in our fees article. Homeland works on a No Recovery, No Fee basis in both states.
How to choose a public adjuster in Florida or New Jersey
Most people hire a public adjuster once, after a loss, under time pressure. Five checks separate a licensed professional from the people who show up after a storm.
1. Verify the license before anything else. Florida public adjusters are licensed by the Department of Financial Services; look up the name or license number in the DFS Licensee Search. New Jersey public adjusters are licensed by the Department of Banking and Insurance; use the DOBI Licensee Search. A firm's license and the individual adjuster's license are both searchable. Homeland's are listed in the footer of every page on this site.
2. Get the fee for your claim in writing. In Florida the cap is 20% of what the insurer pays, or 10% for a claim from a declared state of emergency made during the year after the declaration (§626.854(11)). New Jersey requires the written contract to state the maximum fee, which must be reasonably related to the services rendered. Ask what the percentage is for your specific claim and whether it changes if the claim is reopened or supplemented.
3. Ask who will actually handle your file. The person who signs you up isn't always the person who inspects, writes the estimate and negotiates. Ask for that adjuster's name and license number, how the loss will be documented (a line-item estimate, photographs, moisture readings), and how often you'll hear from them.
4. Know the red flags. Florida law for residential and condo-unit policies spells several out: solicitation outside 8 a.m. to 8 p.m., Monday through Saturday (§626.854(5)); gifts worth more than $25 or any loan or cash advance as an inducement to sign (§626.854(9), (10)); a contract or power of attorney that lets the adjuster choose who does your repairs (§626.854(18)); and no written contract at all (§626.854(6)). New Jersey bars soliciting or signing a contract between 6 p.m. and 8 a.m. during the first 24 hours after a loss (N.J.A.C. 11:1-37.13(c), (d)). Anyone who pressures you to sign on the spot should know that a Florida policyholder can cancel a public adjuster contract without penalty within 10 days, or within 30 days of the loss during a declared emergency, whichever is longer (§626.854(7)).
5. Ask what happens if the insurer says no. A public adjuster should be able to explain appraisal, mediation and the policy's own dispute provisions before you need them, and should tell you plainly when a claim has become a legal matter.
When you also need a lawyer
A public adjuster handles the claim: the damage, the estimate, the policy and the negotiation. An attorney handles the dispute when the insurer denies coverage outright, when the issue is the insurer's conduct rather than the amount, or when a lawsuit deadline is approaching. The two roles work together on many files. Homeland is a public adjusting firm, not a law firm, and refers clients to counsel when a claim calls for it. Our article on Florida's attorney-fee law changes explains why that distinction matters more now than it used to.
Homeland serves policyholders in Miami, Orlando and Newark, with local lines across both states.
Frequently asked questions
What is a public adjuster in simple terms?
Is a public adjuster the same as an insurance adjuster?
Do public adjusters need a license?
How much does a public adjuster charge?
How do I choose a public adjuster in Florida?
How do I verify a public adjuster's license?
Do I need a lawyer or a public adjuster?
If you're deciding whether to hire one, Homeland offers a free claim review: we look at the damage and the policy and tell you what we see, with no obligation.
This article is for general information only and is not legal or insurance advice. Statutes, regulations and policy wording change, and how they apply depends on your own policy and the facts of your claim. Homeland Public Adjusters is a public adjusting firm, not a law firm.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Public Adjuster Near Me page to get connected with the Homeland adjuster covering your area.