Business Interruption: What Counts as Lost Income After a Claim

Homeland Public Adjusters · Last reviewed: October 2026
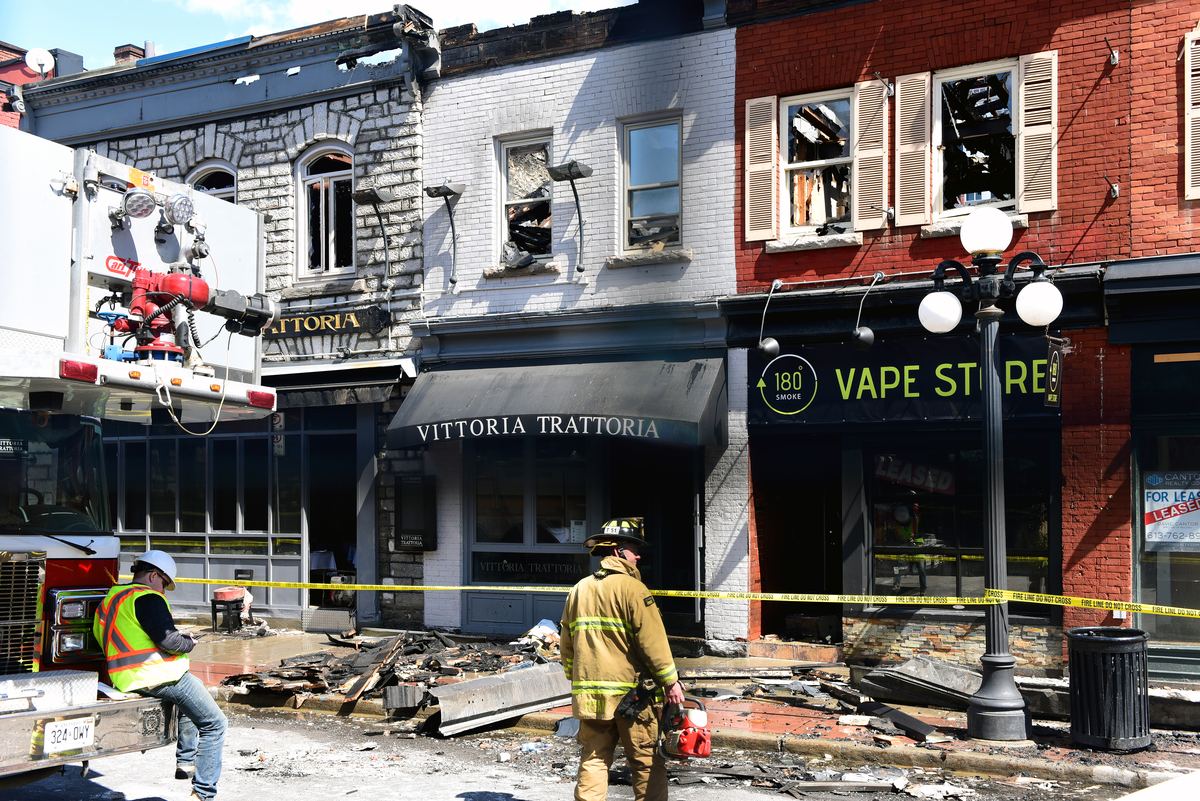
Business interruption coverage, sometimes called business income coverage, is meant to replace the income a business would have earned if the loss hadn’t happened, for the period it reasonably takes to resume normal operations. It’s attached to a covered property loss — it doesn’t stand alone.
What it typically covers
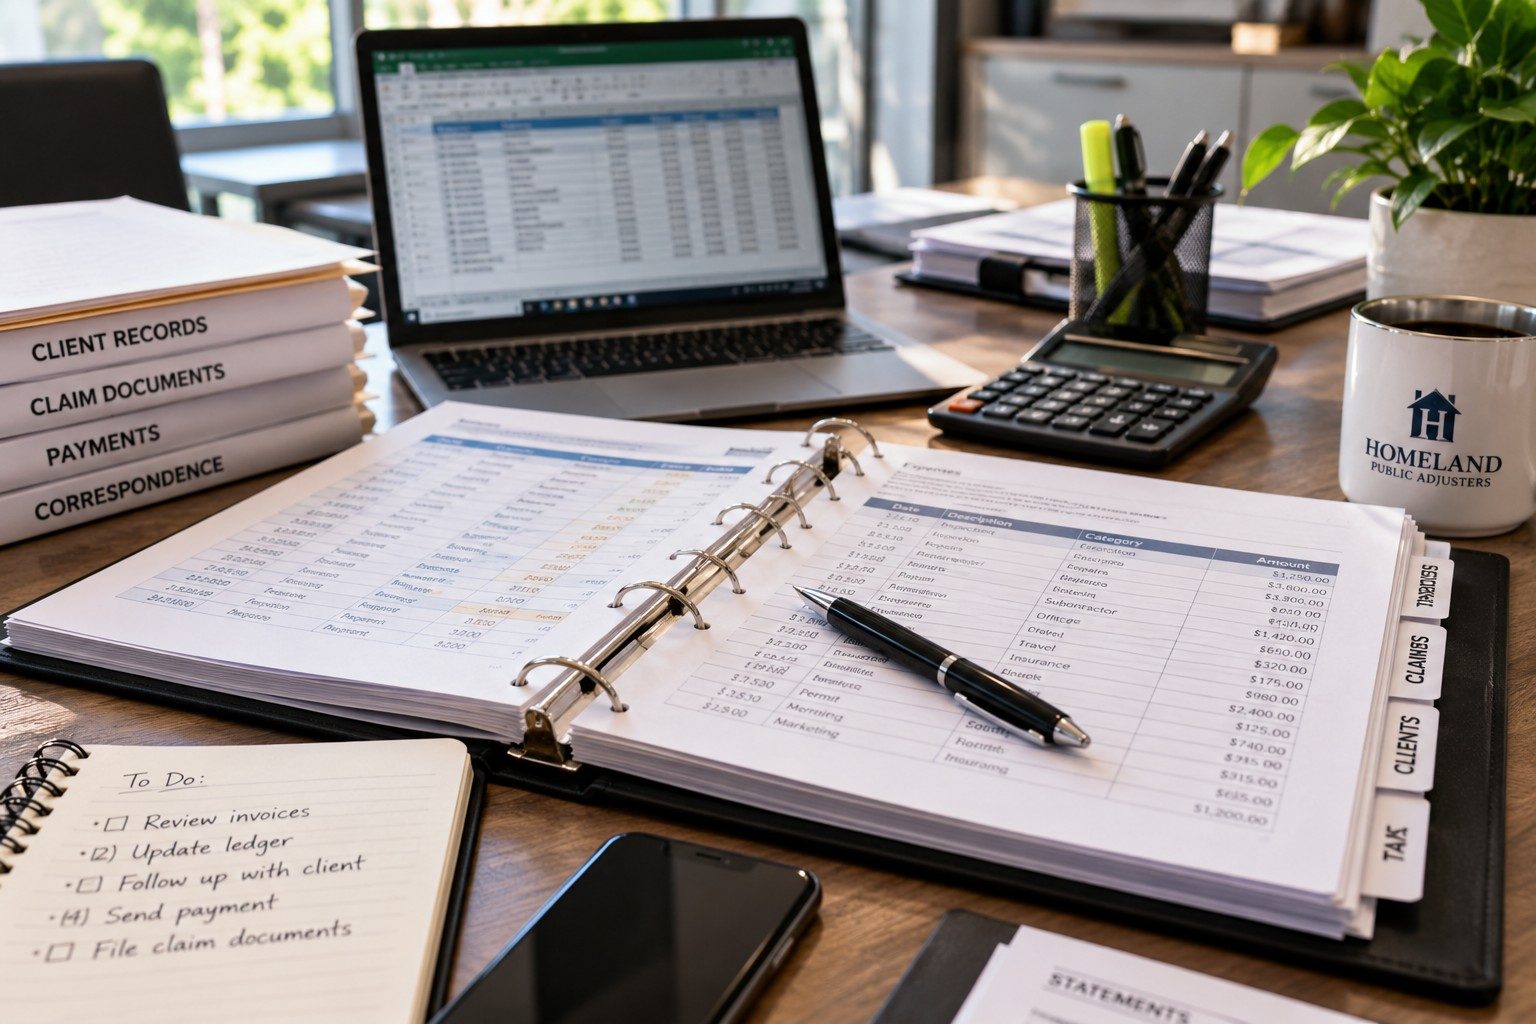
Lost net income, plus continuing normal operating expenses the business still has to pay even while closed or operating at reduced capacity, and sometimes extra expenses incurred to speed up reopening or keep operating from a temporary location.
What it depends on
Your actual financial history before the loss, the “period of restoration” — how long it reasonably takes to get back to normal, not how long you choose to take — and any sub-limits or waiting periods specific to your policy.
If a covered loss is interrupting your business, call Homeland before you speak with the insurance company. The business-interruption piece of a claim is often the most valuable part and the easiest to undervalue without someone building the case for it properly.
Business interruption losses are part of Homeland's commercial work in Orlando, Tampa and Newark.
Frequently asked questions
What does business interruption insurance cover?
Does business interruption coverage apply without property damage?
Why do insurers dispute business interruption claims?
This article is for general information only and is not legal or insurance advice. Every policy and every claim is different — always review your own policy language or speak with a licensed public adjuster about your specific situation.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewThis topic often comes up alongside Keeping Your Business Records Ready for a Claim. If your situation involves this kind of loss, see our Business & Commercial page for how Homeland can help with the claim itself.