When a Supplier or Neighboring Business Closure Hits Your Bottom Line

Homeland Public Adjusters · Last reviewed: October 2026
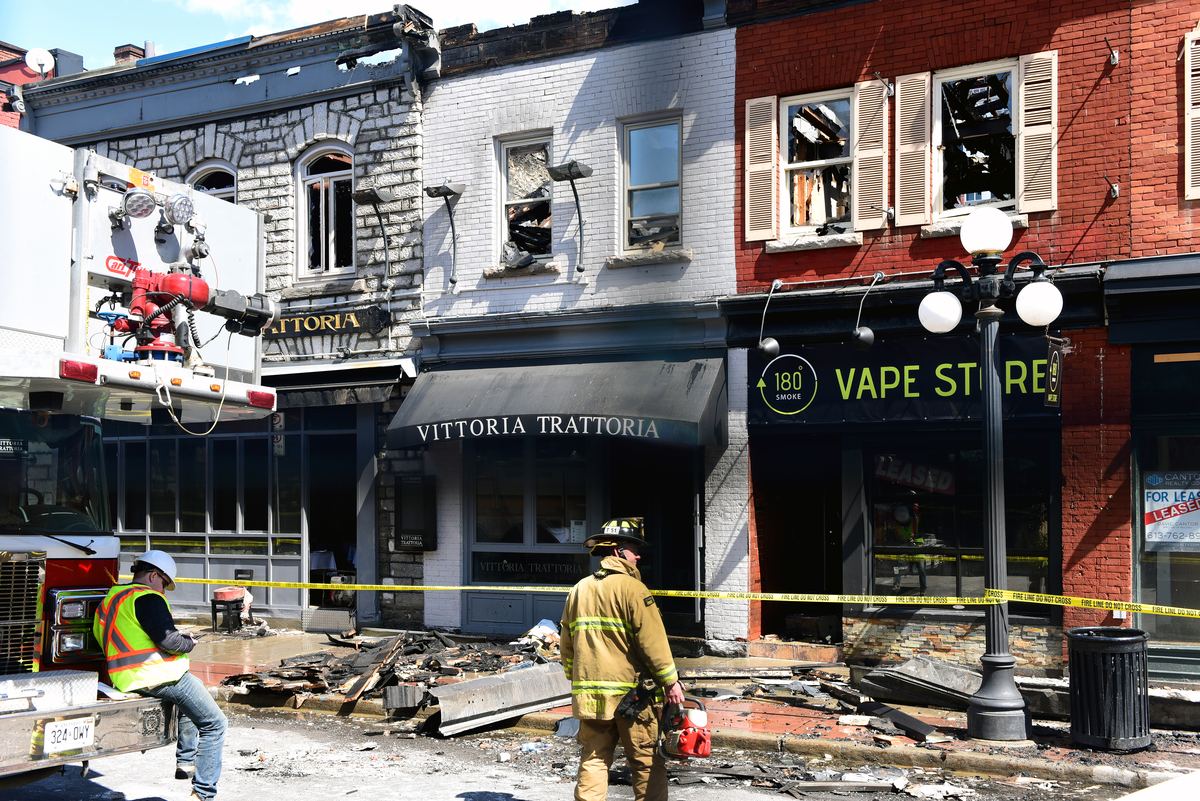
Most business interruption coverage responds to damage at your own location. A separate, less commonly understood coverage, contingent business interruption, can respond when a loss happens somewhere else: a key supplier’s facility, a business that drives foot traffic to yours, or a location you depend on that isn’t yours at all.
Have a property claim anywhere in Florida? A licensed Homeland public adjuster comes to you within hours — no need to visit an office. Call (305) 783-3777 (Florida) or (732) 517-3777 (New Jersey), 24/7.
Where this shows up in practice
Short answer: Contingent business interruption coverage can pay lost income when the damage happens somewhere else, such as a key supplier’s facility or an anchor business that drives your foot traffic. It is not automatic on every commercial policy, and the claim has to show a documented link between the other loss and your lost income.
A supplier’s fire or storm damage disrupts your ability to get inventory or materials; a major anchor tenant or neighboring business in a shopping center closes after its own loss and your foot-traffic-dependent business suffers as a result; a utility or access-road closure outside your property keeps customers away.
Why it's often missed
This coverage isn’t automatic on every commercial policy, and even where it exists, it usually requires showing a direct, documented connection between the other business’s loss and your own lost income, not just that business was slower during the same period.
If your business took a hit from someone else’s loss rather than your own, call Homeland before assuming nothing can be done. Whether contingent business interruption coverage exists and applies depends on your specific policy, and it’s easy to overlook without someone checking for it.
Homeland handles commercial losses, including contingent claims, for businesses in Miami, Fort Lauderdale and Jersey City.
Frequently asked questions
Can I claim lost income if a supplier’s or neighboring business’s loss hurt my business?
What do I need to show for a contingent business interruption claim?
This article is for general information only and is not legal or insurance advice. Every policy and every claim is different — call Homeland. We review your policy language with you at no cost.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewThis topic often comes up alongside Keeping Your Business Records Ready for a Claim. If your situation involves this kind of loss, see our Business & Commercial page for how Homeland can help with the claim itself.