A Neighbor's Fire Damaged My Belongings. Now What?

Homeland Public Adjusters · Last reviewed: October 2026
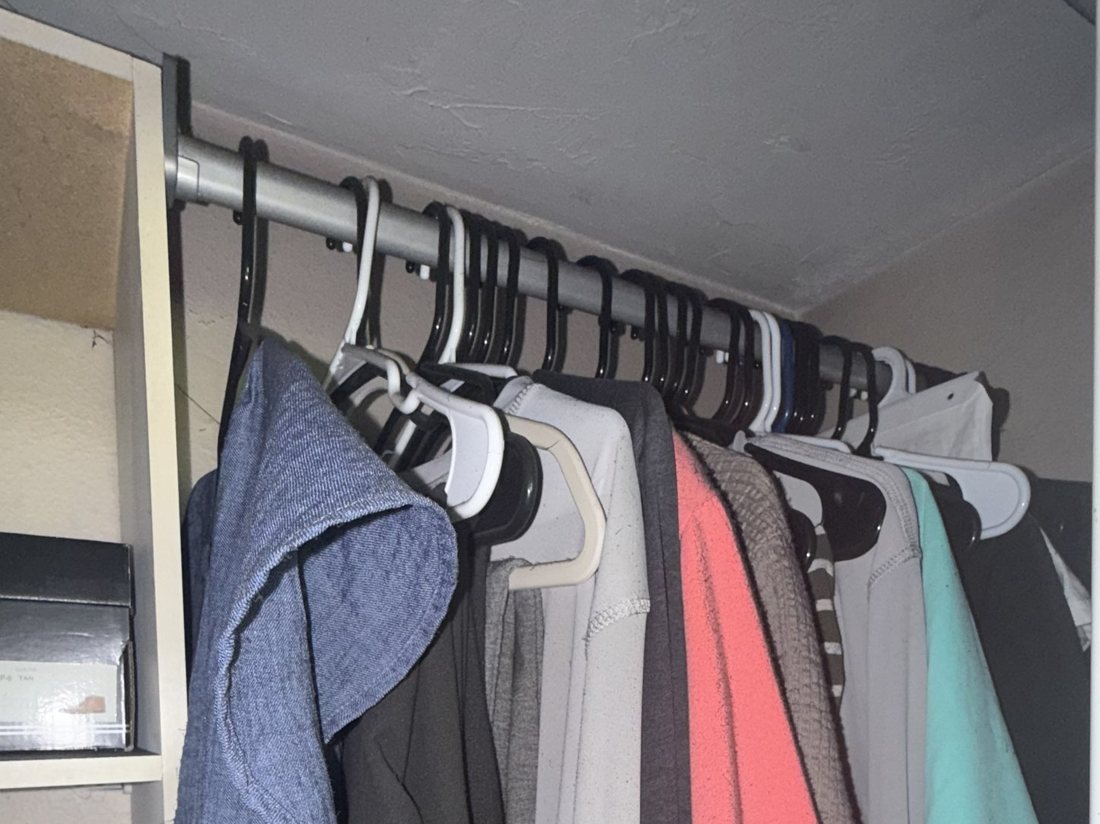
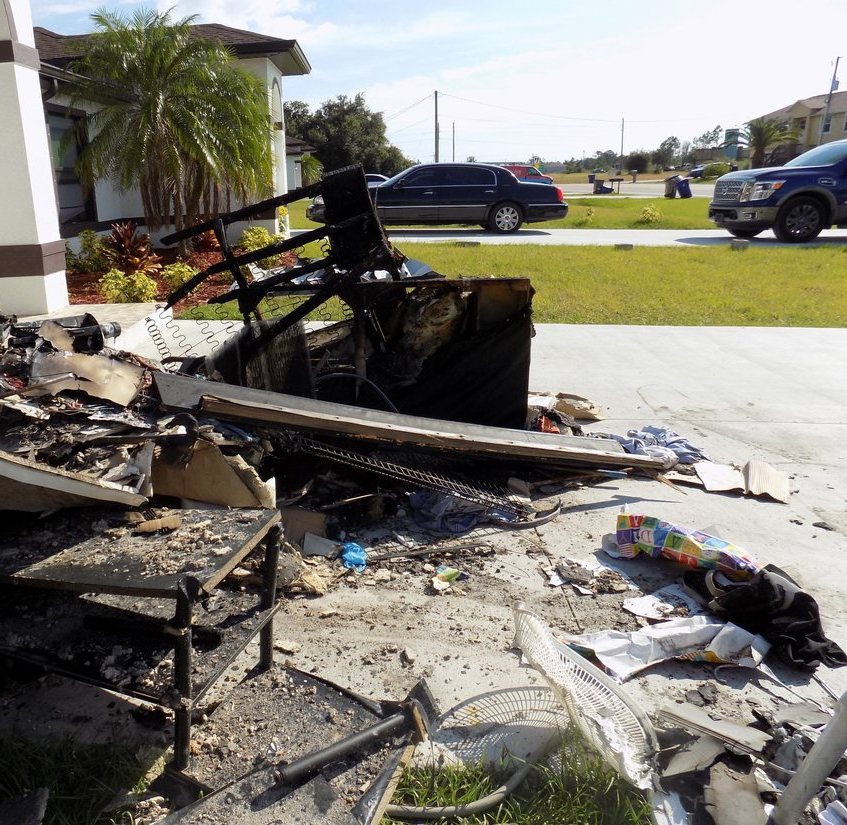
A fire two apartments down can still leave your unit with smoke-stained walls, soot on every surface, and belongings that smell like smoke even if the flames never reached your door. Renters are often told the building owner’s insurance “will handle it,” and then find out that policy only covers the building itself — not what was inside their apartment.
Have a property claim anywhere in Florida? A licensed Homeland public adjuster comes to you within hours — no need to visit an office. Call (305) 783-3777 (Florida) or (732) 517-3777 (New Jersey), 24/7.
The landlord's policy has a narrow job
Short answer: If a neighbor’s fire damages your belongings, the building owner’s policy generally covers only the building, not what was in your apartment. Your own renters policy covers your belongings against fire and smoke wherever the fire started, plus loss of use, and your insurer can pursue whoever caused the fire separately.
A landlord or property owner’s insurance policy is built to protect the structure: the walls, roof, plumbing and the owner’s own fixtures. It generally has no obligation to replace a tenant’s furniture, electronics or clothing, regardless of which unit the fire started in. That gap is exactly what renters insurance is designed to fill, and it’s why a fire that wasn’t your fault can still leave you without coverage if you don’t carry a policy of your own.
If you have renters insurance
A renters policy typically covers your personal property against fire and smoke damage regardless of where the fire started, plus loss-of-use expenses if the apartment becomes temporarily unlivable. Call Homeland first: a claim on your own renters policy is usually the fastest way to get reimbursed, and your insurer can pursue the party actually responsible for the fire separately, through subrogation, without that process slowing down your own claim.
If you don't have renters insurance
Without your own policy, options are more limited but not necessarily zero. If the fire was caused by another tenant’s negligence — an unattended stove, a cigarette, faulty wiring they installed themselves — their liability coverage, if they have any, may be a path to recovery. Document everything you lost with photos, receipts or any proof of value you can find, and keep a written account of what happened while it’s fresh.
Renters in Jersey City, Miami and Orlando can call Homeland for a free review of their renters claim.
Frequently asked questions
Will my landlord’s insurance pay for my belongings after a neighbor’s fire?
Should I file with my own renters insurance if a neighbor caused the fire?
Should I throw away smoke-damaged items after a fire?
This article is for general information only and is not legal or insurance advice. Every policy and every claim is different — call Homeland. We review your policy language with you at no cost.
- Renters: Is Your Property Covered After a Loss?
- My Renters Claim Was Denied or Underpaid
- Dryer Fire Insurance Claims: Lint, Vents, Who Pays
- Smoke Damage Insurance Claims: How to Prove the Loss
 Nelson Avila
 Yeni Martinez
 Alberto Enriquez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewThis topic often comes up alongside Renters: Is Your Property Covered After a Loss?. If your situation involves this kind of loss, see our Renters page for how Homeland can help with the claim itself.