Florida Property Insurance Claims by the Numbers: What the State’s 2026 Report Shows

Homeland Public Adjusters · Last reviewed: October 2026
Short answer: Florida insurers closed 456,200 residential property claims in 2025 and paid $10 billion in indemnity on them. 12.1% of those claims were litigated, and litigation ran at 27.3% in Broward, Miami-Dade and Palm Beach counties. The median claim was reported 10 days after the loss and closed 30 days after that. Every figure on this page comes from the Florida Office of Insurance Regulation’s Property Insurance Stability Report (July 1, 2026), filed under §627.7154.
Where these numbers come from
Since 2022, every insurer writing residential property insurance in Florida has had to file an annual Property Claims Lifecycle Report under §624.424(11) covering every claim it closed in the calendar year. OIR compiles the filings into a report to the Legislature twice a year. The July 1, 2026 report covers claims closed during 2025: 600 companies were noticed, 170 filed data, and OIR fined four insurers a total of $40,500 for filing late. Individual claim data is confidential; what follows are the statewide figures the report publishes.
The 2025 claims year in six numbers
| Measure | 2025 figure (claims closed in 2025) |
|---|---|
| Claims closed | 456,200 |
| Litigated claims | 53,413 (12.1% of claims with a known litigation status) |
| Non-litigated claims | 387,931 |
| Indemnity paid | $10 billion |
| Loss adjustment expense (LAE) paid | $1.7 billion |
| Average LAE per claim | $15,257 on litigated claims; $2,044 on non-litigated claims |
How long a Florida claim takes
Across all perils, policyholders reported their loss to the insurer an average of 65 days after it happened; the median was 10 days. Insurers then took an average of 66 days to close the claim, with a median of 30 days. §627.70131(7)(a) requires an insurer to pay or deny a claim, or part of it, within 60 days of receiving notice, unless factors beyond its control intervene, and to explain in writing the basis for any payment, denial or partial denial.
Litigation rate by peril
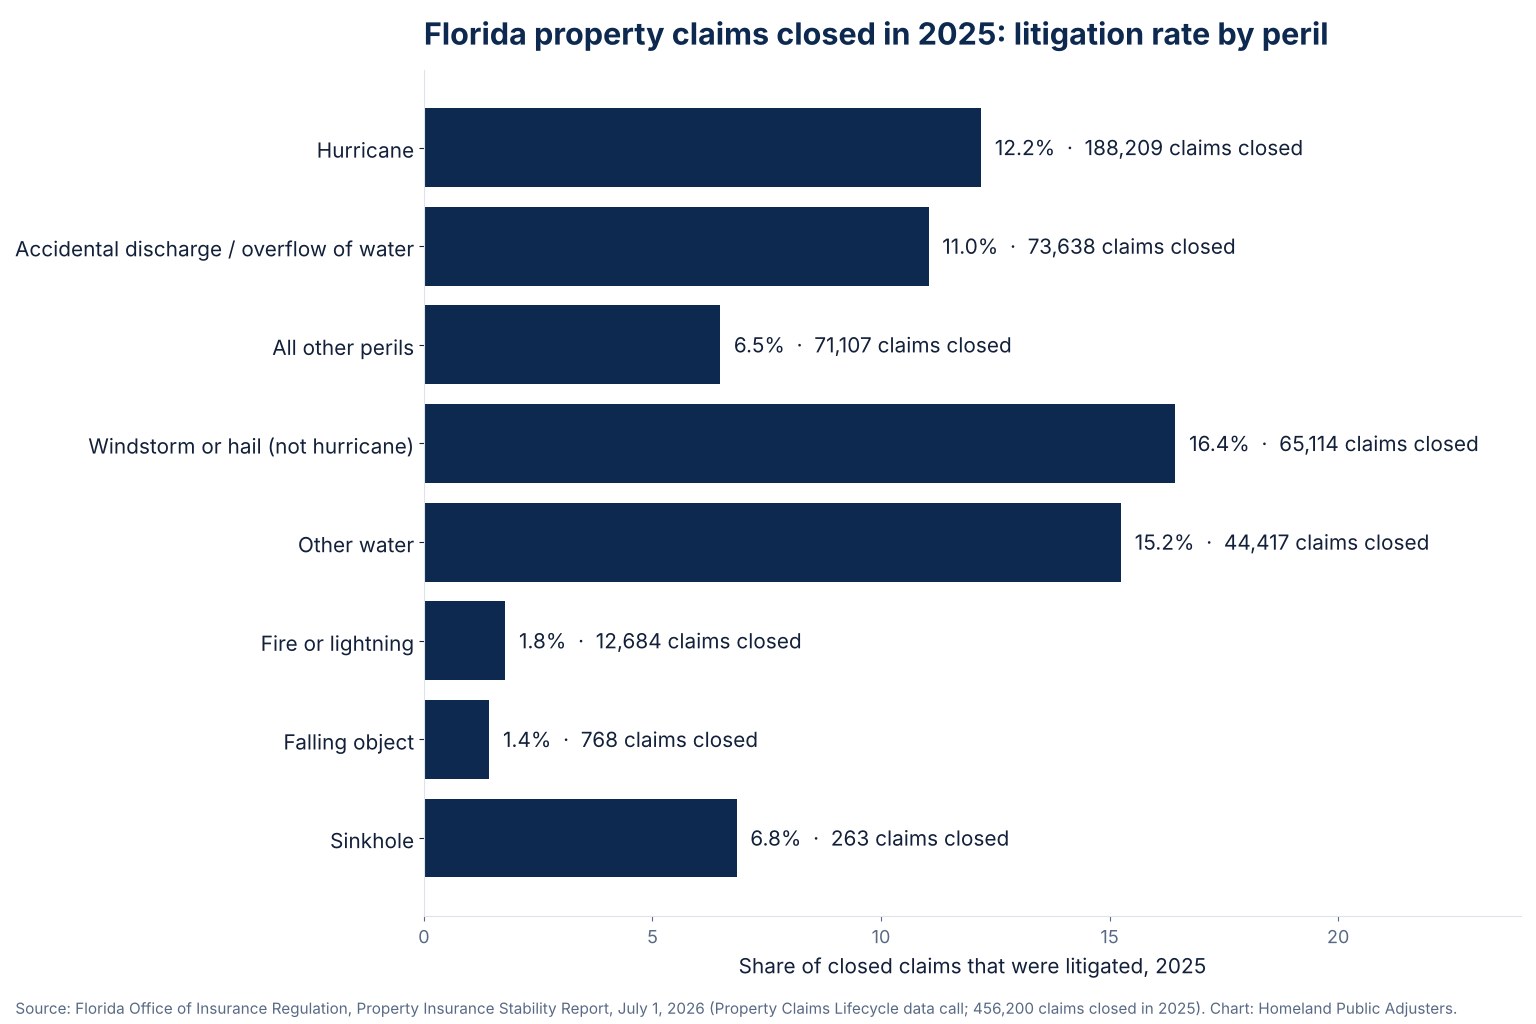
The share of closed claims that ended in litigation varied widely by the cause of loss:
| Peril | Claims closed in 2025 | Litigated | Not litigated |
|---|---|---|---|
| Hurricane | 188,209 | 12.19% | 84.87% |
| Accidental discharge or overflow of water | 73,638 | 11.04% | 84.85% |
| All other perils | 71,107 | 6.48% | 89.69% |
| Windstorm or hail (other than hurricane) | 65,114 | 16.44% | 80.65% |
| Other water | 44,417 | 15.25% | 82.55% |
| Fire or lightning | 12,684 | 1.78% | 93.23% |
| Falling object | 768 | 1.43% | 90.63% |
| Sinkhole | 263 | 6.84% | 91.25% |
The remainder in each row had an unknown litigation status. Hurricane claims were 41% of everything closed in 2025, a reflection of the 2024 storms still working through the system; the report notes that many hurricane claims from current and prior years were reported in the 2025 closed-claims data.
Litigation by region
| Region | Policies in force | Litigated claims | Non-litigated claims | Litigated share |
|---|---|---|---|---|
| Palm Beach, Broward and Miami-Dade counties | 1,687,888 | 20,407 | 54,422 | 27.27% |
| Seminole, Orange, Lake and Osceola counties | 959,900 | 7,436 | 45,639 | 14.01% |
| All other counties | 5,059,264 | 25,570 | 287,870 | 8.16% |
| Statewide | 7,707,052 | 53,413 | 387,931 | 12.10% |
South Florida’s three counties hold 22% of the state’s policies and produced 38% of its litigated claims. A claim in Miami-Dade, Broward or Palm Beach was more than three times as likely to end in a lawsuit as a claim elsewhere in the state.
What litigated claims paid, compared with non-litigated ones
The report breaks average indemnity down by peril, by whether the claim was litigated, and by how long it took to close. For claims closed within 60 days, the gap is consistent:
| Peril (closed in under 61 days) | Average indemnity, litigated | Average indemnity, not litigated | Average LAE, litigated | Average LAE, not litigated |
|---|---|---|---|---|
| Hurricane | $47,391 | $19,424 | $15,277 | $2,160 |
| Accidental discharge / overflow of water | $24,945 | $8,510 | $15,731 | $984 |
| Other water | $32,750 | $8,952 | $9,693 | $1,748 |
| Windstorm or hail (not hurricane) | $29,863 | $10,858 | $10,256 | $1,113 |
| Fire or lightning | $97,470 | $31,961 | $12,342 | $1,460 |
| All other perils | $37,239 | $5,475 | $11,622 | $1,331 |
Who insures Florida homes: the voluntary market and Citizens
As of March 31, 2026, voluntary insurers wrote 98.07% of Florida homeowners policies and Citizens Property Insurance Corporation wrote 1.93%. The split is very different for wind-only coverage:
| Policy type, Q1 2026 | Voluntary market | Citizens | Total policies |
|---|---|---|---|
| Homeowners multi-peril | 4,111,620 (98.95%) | 43,473 (1.05%) | 4,155,093 |
| Homeowners wind-only | 28,245 (42.67%) | 37,953 (57.33%) | 66,198 |
| Condominium unit owners multi-peril | 916,479 (98.35%) | 15,413 (1.65%) | 931,892 |
| Condominium unit owners wind-only | 4,900 (25.47%) | 14,340 (74.53%) | 19,240 |
The report also notes that Florida domestic property insurers’ 2024 claims developed about $377 million favorably after one year, which OIR reads as a sign the 2022–2023 legislative reforms are reducing claim costs.
Average homeowners and condo premiums in every Florida county
OIR calculates the average premium by county from the Market Intelligence Report: total premium divided by policies in force, separately for policies with and without wind coverage. These are averages across all companies, insured values and deductibles; your own premium will differ. Data as of March 31, 2026. The average homeowners premium with wind coverage fell in 51 counties from the January 2026 report.
| County | Homeowners, incl. wind | Homeowners, excl. wind | Condo unit owners, incl. wind | Condo unit owners, excl. wind |
|---|---|---|---|---|
| Alachua | $2,525 | $1,804 | $977 | $606 |
| Baker | $2,346 | $2,913 | N/A | N/A |
| Bay | $3,465 | $1,577 | $1,393 | $928 |
| Bradford | $2,623 | $1,950 | $1,005 | N/A |
| Brevard | $3,532 | $1,975 | $1,454 | $994 |
| Broward | $6,136 | $3,008 | $1,816 | $1,317 |
| Calhoun | $3,122 | $2,649 | N/A | N/A |
| Charlotte | $3,160 | $1,661 | $1,394 | $933 |
| Citrus | $2,456 | $1,560 | $1,105 | $614 |
| Clay | $2,540 | $2,047 | $962 | $563 |
| Collier | $5,534 | $3,169 | $2,271 | $1,566 |
| Columbia | $2,557 | $2,118 | $971 | $331 |
| DeSoto | $3,421 | $2,167 | $1,088 | $547 |
| Dixie | $2,748 | $1,559 | $1,117 | $499 |
| Duval | $2,786 | $2,095 | $1,054 | $1,047 |
| Escambia | $3,702 | $1,670 | $1,836 | $1,060 |
| Flagler | $2,488 | $1,641 | $1,310 | $1,039 |
| Franklin | $5,221 | $1,954 | $1,563 | $1,400 |
| Gadsden | $2,723 | $2,226 | N/A | N/A |
| Gilchrist | $2,513 | $1,872 | N/A | N/A |
| Glades | $3,477 | $2,019 | $1,117 | N/A |
| Gulf | $3,752 | $1,612 | $1,747 | $886 |
| Hamilton | $2,711 | $2,044 | N/A | N/A |
| Hardee | $3,376 | $2,246 | N/A | N/A |
| Hendry | $2,999 | $1,983 | $1,329 | $878 |
| Hernando | $2,360 | $1,985 | $1,063 | $630 |
| Highlands | $2,736 | $1,599 | $1,082 | $615 |
| Hillsborough | $3,525 | $2,676 | $1,353 | $799 |
| Holmes | $2,942 | $2,560 | N/A | N/A |
| Indian River | $4,334 | $2,744 | $2,086 | $1,424 |
| Jackson | $2,851 | $2,300 | N/A | N/A |
| Jefferson | $2,782 | $2,083 | N/A | N/A |
| Lafayette | $2,903 | $1,649 | N/A | N/A |
| Lake | $2,650 | $1,988 | $1,092 | $768 |
| Lee | $3,576 | $2,119 | $1,494 | $1,061 |
| Leon | $2,538 | $1,710 | $846 | $441 |
| Levy | $2,698 | $1,634 | $1,437 | $637 |
| Liberty | $2,880 | $1,872 | N/A | N/A |
| Madison | $2,735 | $1,482 | N/A | N/A |
| Manatee | $3,181 | $1,859 | $1,368 | $992 |
| Marion | $2,191 | $1,766 | $1,081 | $539 |
| Martin | $5,899 | $2,471 | $1,765 | $887 |
| Miami-Dade | $5,975 | $3,779 | $2,801 | $1,764 |
| Monroe | $7,863 | $1,871 | $3,474 | $1,323 |
| Nassau | $3,051 | $1,608 | $1,809 | $1,209 |
| Okaloosa | $3,889 | $1,889 | $1,729 | $991 |
| Okeechobee | $3,730 | $1,973 | $1,476 | $696 |
| Orange | $3,610 | $2,565 | $1,295 | $838 |
| Osceola | $2,940 | $2,433 | $1,278 | $967 |
| Palm Beach | $6,323 | $3,175 | $2,311 | $1,703 |
| Pasco | $2,756 | $1,917 | $994 | $663 |
| Pinellas | $4,063 | $2,034 | $1,399 | $913 |
| Polk | $2,767 | $2,185 | $1,149 | $787 |
| Putnam | $2,621 | $1,768 | $995 | N/A |
| Santa Rosa | $3,512 | $1,951 | $1,872 | $927 |
| Sarasota | $3,457 | $1,482 | $1,759 | $1,052 |
| Seminole | $3,545 | $2,372 | $1,202 | $785 |
| St. Johns | $2,883 | $2,055 | $1,329 | $1,047 |
| St. Lucie | $3,491 | $1,932 | $1,582 | $1,060 |
| Sumter | $2,105 | $1,352 | $1,025 | N/A |
| Suwannee | $2,749 | $1,783 | $683 | N/A |
| Taylor | $2,698 | $1,300 | $1,090 | N/A |
| Union | $2,667 | $3,475 | N/A | N/A |
| Volusia | $2,808 | $1,637 | $1,170 | $873 |
| Wakulla | $2,292 | $1,956 | $1,087 | $907 |
| Walton | $5,409 | $1,891 | $2,031 | $1,208 |
| Washington | $2,871 | $2,628 | N/A | N/A |
Monroe County (the Keys) has the highest average homeowners premium with wind coverage at $7,863, followed by Palm Beach ($6,323), Broward ($6,136), Miami-Dade ($5,975) and Martin ($5,899). Sumter ($2,105) and Marion ($2,191) are the lowest. N/A means no policies of that type were in force in the county.
What this means if you have a claim
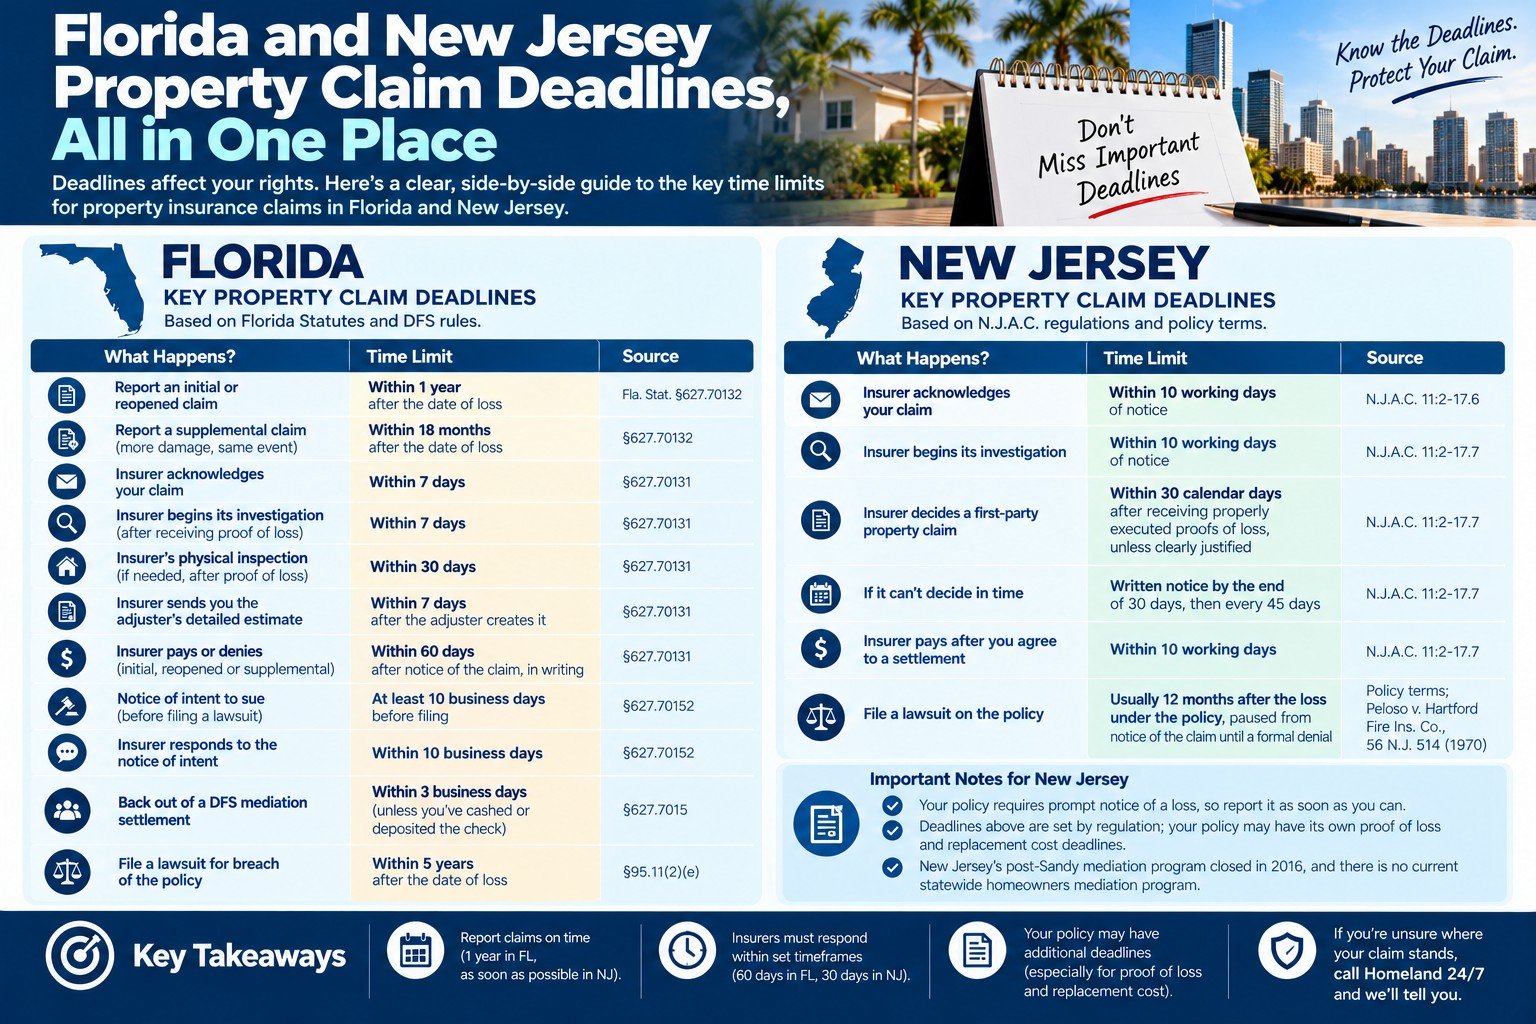
Three things in this data matter to a policyholder. First, the 60-day clock in §627.70131 is real and insurers mostly meet it: the median claim closes in 30 days, so a claim that is dragging past 60 days without a written explanation is outside the norm and worth a written inquiry. Second, the one-year reporting deadline catches the long tail: if you suspect damage from a storm months ago, report it now. Third, litigation is the expensive path for everyone; the supplemental claim, DFS mediation (§627.7015) and appraisal usually come first, and a documented claim is what makes each of them work. Homeland handles that documentation for policyholders across Florida; if you have an open or closed claim, a review is free.
Homeland handles property claims in Miami, Broward County, Palm Beach County and Orlando, the regions where this report shows disputes are most common.
Frequently asked questions
How many property insurance claims were filed in Florida in 2025?
What percentage of Florida insurance claims are litigated?
How long does an insurance claim take in Florida?
What is the average homeowners insurance premium in Florida by county?
What share of Florida homeowners are insured by Citizens?
This article is for general information only and is not legal or insurance advice. Statutes, regulations and policy wording change, and how they apply depends on your own policy and the facts of your claim. Homeland Public Adjusters is a public adjusting firm, not a law firm.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Public Adjuster Near Me page to get connected with the Homeland adjuster covering your area.