Does Homeowners Insurance Cover Animal Damage? Rodents, Raccoons, Bears, Deer and Iguanas

Homeland Public Adjusters · Last reviewed: October 2026
Short answer: Usually not, for the animals that cause most of it. The standard homeowners policy excludes damage caused by birds, rodents, insects and vermin, and by any animal’s nesting, infestation or waste, so rats in the attic, squirrels in the soffit and raccoons in the insulation are generally not covered. Damage by a large wild animal such as a deer or a bear generally is, and the fire or water that follows a chewed wire or line is usually covered as a separate, ensuing loss.
What the policy excludes, in its own words
The ISO special form lists, among the causes it will not pay for, loss caused by “birds, rodents or insects” and by “nesting or infestation, or discharge or release of waste products or secretions, by any animals.” Earlier editions said “birds, vermin, rodents, or insects,” and carriers still read raccoons, squirrels, opossums and skunks as vermin. Progressive’s own explanation is representative: homeowners insurance may cover wildlife damage from animals such as deer or bears, while damage from squirrels, mice, rats, raccoons, skunks and opossums typically is not covered.
| Animal and damage | Covered? | Why |
|---|---|---|
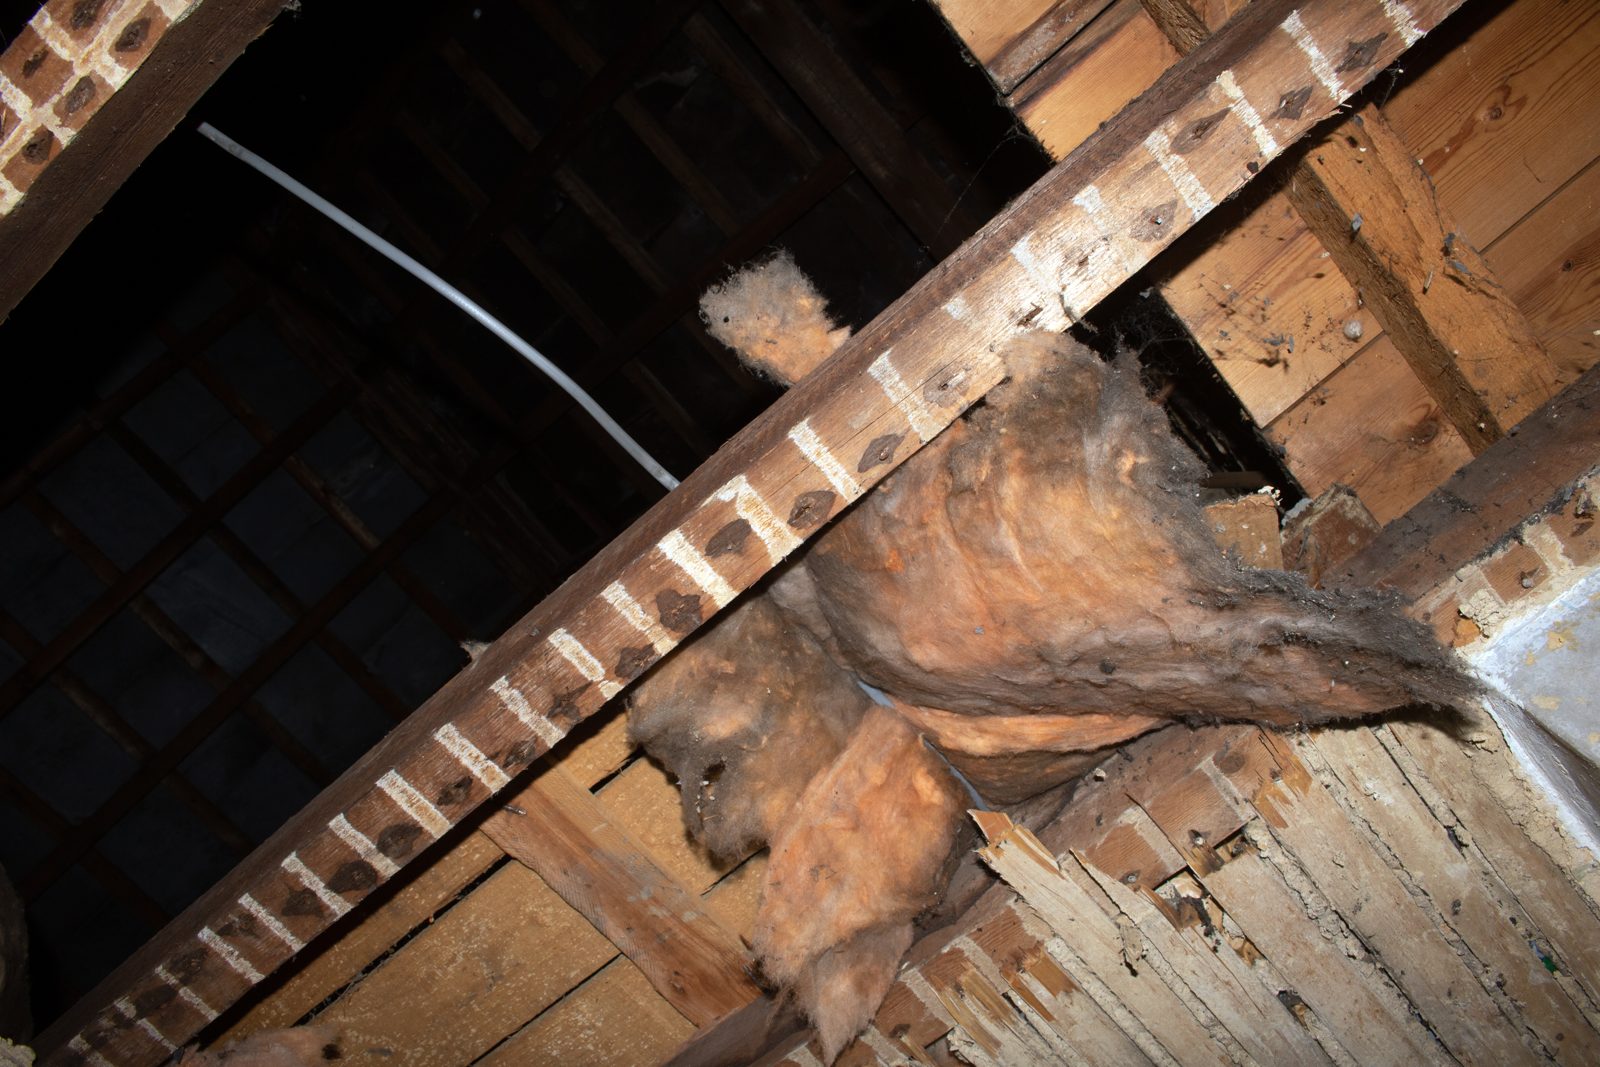
| Rats or mice chew wiring, ducts and insulation | No | Rodents excluded |
| Squirrels or raccoons tear into the soffit and nest in the attic | Usually no | Vermin and nesting/infestation excluded |
| Bats, pigeons or woodpeckers | No | Birds excluded; guano is “waste products” |
| Termites, carpenter ants, bees | No | Insects excluded; hidden insect damage that causes an abrupt collapse is the exception |
| A deer through a sliding door, a bear through a kitchen, a wild hog through a fence | Generally yes | Not an excluded class of animal; a sudden, accidental physical loss |
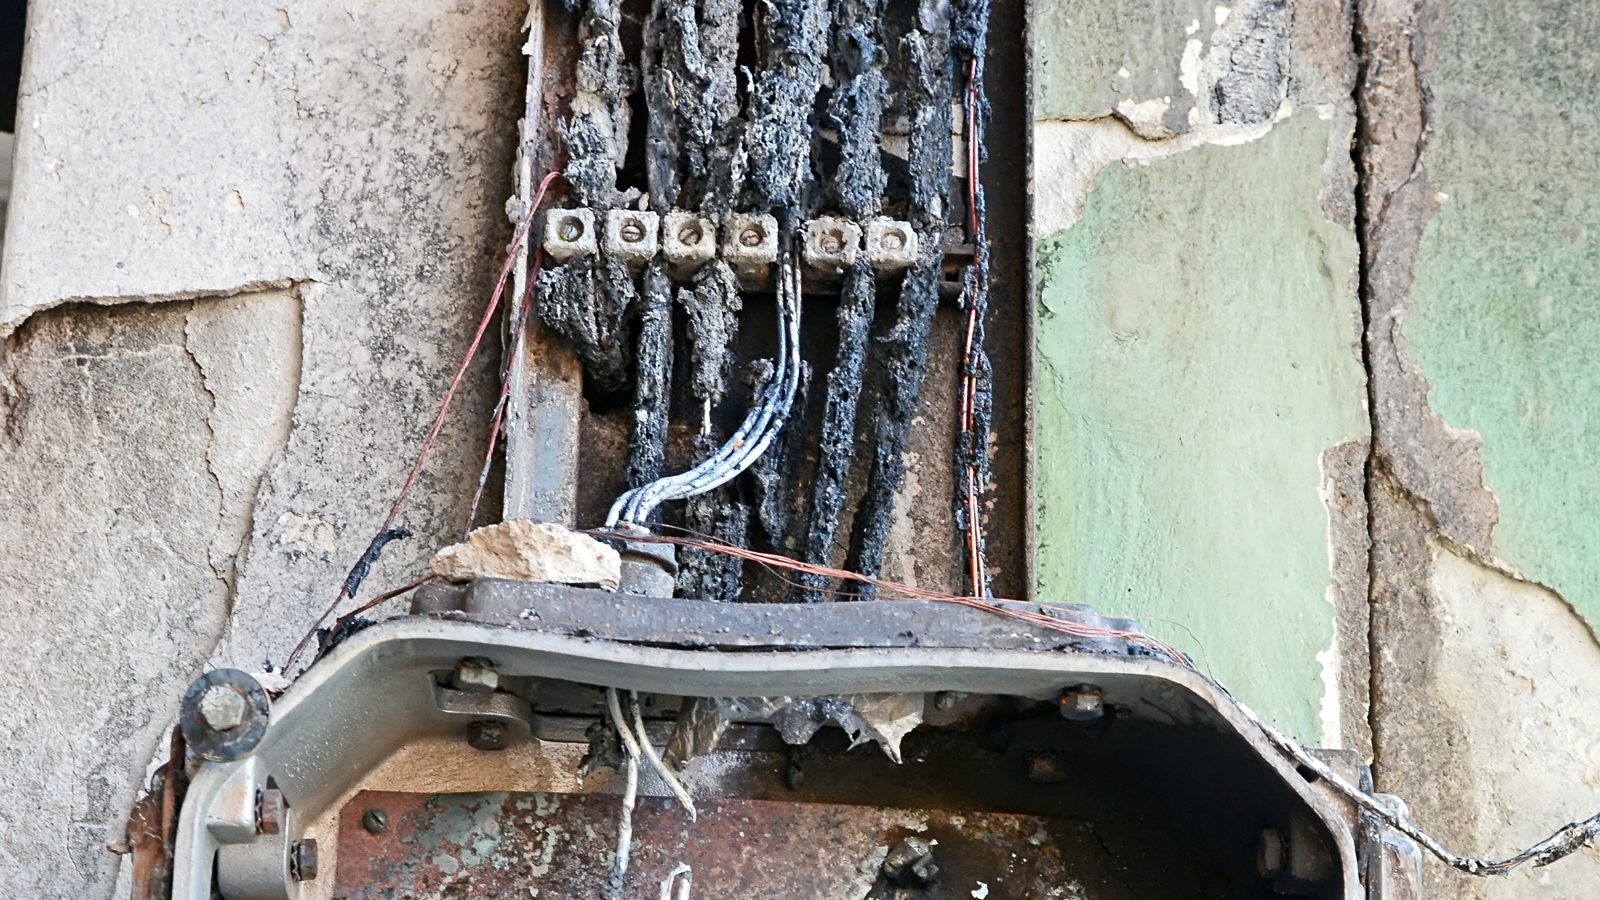
| Fire after a rodent chews a wire | Usually yes | Ensuing fire is a covered peril even when the cause was excluded |
| Water damage after a rat chews a supply line or an icemaker line | Usually yes | Sudden discharge of water is covered; the line itself is not |
| Iguana burrows undermine a seawall, pool deck or foundation | Disputed | Reptiles are not listed; carriers argue earth movement and “vermin”; the structure type matters |
| Removal, trapping, exclusion work | No | Not property damage |
The ensuing-loss rule is where the money is
The exclusion stops at the animal’s own damage. When a rodent chews through a wire and the attic catches fire, the fire is a covered peril and the fire damage is paid; when it chews through a refrigerator line and the kitchen floods, the sudden discharge is covered. The carrier pays for the fire or the water, not for the chewed wire, the nest or the exclusion work. The same logic runs the other way: a carrier that denies a fire because “rodents caused it” has misread its own form. Our guides to electrical fires and sudden water losses cover those claims.
Florida: iguanas and the burrow problem
The Florida Fish and Wildlife Conservation Commission describes green iguanas digging burrows that erode and collapse sidewalks, foundations, seawalls, berms and canal banks. Iguanas are not birds, rodents or insects, so the exclusion does not name them, and carriers fall back on two other arguments: that the loss is earth movement, which is excluded on most forms, and that a collapsed seawall is an “other structure” with its own limit and its own list of excluded causes. These claims are decided on the policy’s exact wording and on an engineer’s opinion of why the wall or slab failed; a claim framed as “iguana damage” invites the denial, and one framed as the abrupt collapse of a structure gets read against the collapse coverage.
New Jersey: bears and deer
New Jersey’s Department of Environmental Protection logged 1,196 bear incidents through September 21, 2026, including 14 home entries and 406 nuisance and property-damage reports. A bear that tears off a garage door, breaks a slider or destroys a kitchen is a covered loss on the standard form; a deer through a window is the same. Document the entry point and the animal, call the police or the DEP so there is a report, and photograph before the cleanup.
What to do
- Identify the animal before you describe the loss to anyone. The species decides the coverage.
- Photograph the entry point, the nest or burrow, every chewed line or wire, and every damaged finish.
- If a chewed wire or line caused a fire or a flood, report the fire or the water loss; the animal is background, not the claim.
- Get the pest or wildlife company’s report in writing with dates; it dates the problem and the exclusion work is a separate expense.
- For a structure undermined by burrows, get an engineer’s report before the carrier’s adjuster frames it as earth movement.
- Call Homeland for a free review when the loss is more than the attic insulation; covered ensuing losses are routinely denied under the animal exclusion.
- Report within the policy’s notice clause; Florida’s outside limit is 1 year (§627.70132).
Frequently asked questions
Does homeowners insurance cover rat or mouse damage?
Are raccoons and squirrels covered?
Is bear or deer damage covered?
Is iguana damage covered in Florida?
Is wildlife removal covered?
My carrier denied the attic fire because rats caused it.
Homeland serves policyholders in Jupiter, Fort Lauderdale and Paterson, with local lines and a licensed public adjuster who calls back right away.
If this is your loss, call Homeland before you talk to the insurance company: Florida (305) 783-3777, New Jersey (732) 517-3777, 24 hours. A licensed public adjuster reviews the claim for free and calls you back right away. No Recovery, No Fee.
Sources
- Merlin Law Group, Squirrels damage your home: coverage or not (quoting ISO HO-3 editions)
- Merlin Law Group, Bats in the house (HO-3 exclusion wording)
- Progressive, Does homeowners insurance cover animal damage
- Florida Fish and Wildlife Conservation Commission, Green iguana
- New Jersey 101.5, NJ bear encounters 2026 (NJ DEP data)
This article is for general information only and is not legal or insurance advice. Statutes, regulations and policy wording change, and how they apply depends on your own policy and the facts of your claim. Homeland Public Adjusters is a public adjusting firm, not a law firm.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Public Adjuster Near Me page to get connected with the Homeland adjuster covering your area.