Claim Stalled With No Decision? The Insurer’s Deadlines in Florida and New Jersey

Homeland Public Adjusters · Last reviewed: October 2026
Short answer: In Florida, an insurer must pay or deny a residential property claim within 60 days after it receives notice of the claim, unless something beyond its control prevents it. In New Jersey, the insurer must pay first-party claims within 30 days of proof of loss unless a clear justification exists, and explain any delay in writing every 45 days.
Florida’s claim clock
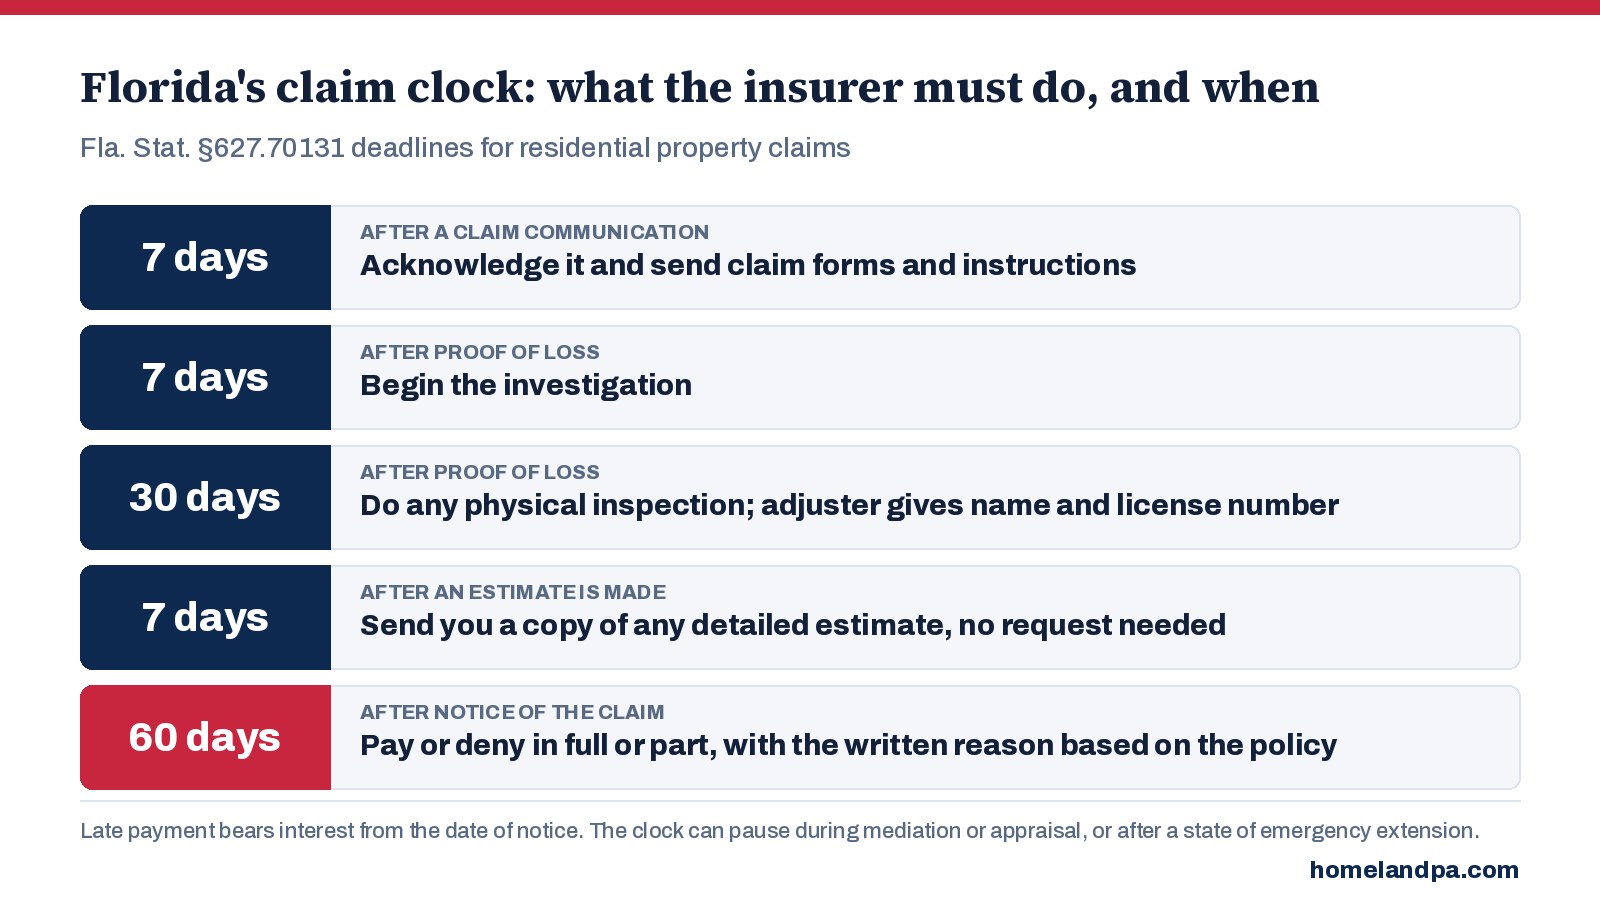
Fla. Stat. §627.70131 sets these deadlines:
- 7 days to acknowledge a communication about a claim (1)(a)
- 7 days after proof of loss to begin the investigation (3)(a)
- 30 days after proof of loss for any physical inspection (3)(b)
- 7 days to send you any detailed estimate, without a request (3)(e)
- 60 days after notice of an initial, reopened or supplemental claim to pay or deny it, in whole or in part, with a written explanation (7)(a)
If payment comes late, it bears interest from the date the insurer received notice of the claim. A missed deadline violates the Insurance Code, though on its own it is not the basis for a private lawsuit. The 60-day rule covers residential claims and commercial claims for structures of 10,000 square feet or less (7)(b).
When the Florida clock pauses
The clock is paused while a DFS mediation or an appraisal or other policy dispute process is pending, and when the policyholder doesn’t provide requested material information within 10 days, as long as the request was made at least 15 days before the deadline (8). After a declared emergency, OIR can extend the deadline by no more than 30 days (5)(a). Answering document requests quickly and in writing keeps the clock running.
New Jersey’s rules
New Jersey insurers must acknowledge a claim within 10 working days (N.J.A.C. 11:2-17.6) and begin investigating within 10 working days (N.J.A.C. 11:2-17.7(a)). First-party claims are paid within 30 calendar days of properly executed proofs of loss, unless a clear justification exists. If the insurer needs more time, it must send written notice stating the reasons, then follow-up notices every 45 days until the claim is paid or rejected (17.7(e)).
What to do about a stalled claim
- Write down every date: notice, inspection, each document request and each response
- Ask in writing for the claim status and for anything still needed, and send what is asked
- In Florida, consider the free DFS mediation program under §627.7015
- Where the insurer is not attempting in good faith to settle, Florida’s civil remedy notice under Fla. Stat. §624.155 gives it 60 days to cure
Frequently asked questions
How long does a Florida insurer have to pay a claim?
Does the 60 days start at proof of loss?
What happens if a Florida insurer misses the deadline?
How often must a New Jersey insurer update me?
Call Homeland first. Before you answer the insurer, sign anything or accept a final number, call us 24/7 at (305) 783-3777 in Florida or (732) 517-3777 in New Jersey. We read the letter against your policy, document the loss and present the claim for you. Hablamos español.
This article is for general information only and is not legal or insurance advice. Statutes, regulations and policy wording change, and how they apply depends on your own policy and the facts of your claim. Homeland Public Adjusters is a public adjusting firm, not a law firm.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewIf you already have an open claim, see What to Do in the First 24 Hours After Property Damage, or visit our Denied and Underpaid Claims page.