
How Homeland Answers the Questions to Ask Any Public Adjuster
- Active individual and firm license
- Firm: Florida W818638, New Jersey 3003982360. Each adjuster’s own license number and DFS record are listed under Verify Homeland.
- Complaints and discipline
- BBB Accredited Business, A+ rating. Look up any license on the DFS licensee search before you sign.
- Who handles your claim
- A licensed Homeland public adjuster handles your file and comes to your property. Our adjusters are named, with their license numbers, under Verify Homeland.
- A documented process
- Five steps, from your call to payment. See How It Works.
- Fee explained in writing
- Our fee is explained in your written agreement before you hire us. Florida law caps public adjuster fees (Fla. Stat. §626.854(11)(b)); see our fees page. No Recovery, No Fee.
- Reachable 24/7
- 24/7 at (305) 783-3777. A licensed Homeland adjuster comes to your property, anywhere in Florida.
- Bilingual
- English and Spanish, on the phone, at your property and in writing.
The Florida law behind each of the 10 tests is on our Florida 10-point test page. Warning signs and common online claims are answered in Public Adjuster Myths vs. Florida Law.
Verify Homeland
Check us before you hire anyone. Every license below links to its public record on the Florida Department of Financial Services licensee search.
- Serves Miami Beach: Yes. Wherever you are in Miami Beach, a licensed Homeland public adjuster comes to your property within hours — no need to visit an office. Call (305) 783-3777, 24/7.
- Homeland Public Adjusters Corporation: Florida public adjusting firm license W818638 · New Jersey public adjuster firm license 3003982360
- Yeni Martinez, President: Florida public adjuster license P103370 (licensed since 2007) · New Jersey 3003714097 · designated primary adjuster
- Alberto Enriquez: Senior licensed public adjuster, Florida P112658
- Yisel Dieguez: Licensed public adjuster and Xactimate estimator, Florida W873884 · New Jersey 3003714335
- Nelson Avila: Florida public adjuster license G332385 · Florida Certified Contractor CRC1331322 · property insurance appraiser and umpire
- Complaints and reputation: 5.0★ on Google · BBB Accredited Business, A+ rating
- Since 2006: Homeland Public Adjusters, Corp. was incorporated in Florida on December 11, 2006. Our President, Yeni Martinez, has held Florida public adjuster license P103370 since 2007. When Florida began requiring adjusting firms to hold their own firm license (a 2021 law, Senate Bill 1598; DFS began licensing adjusting firms in November 2021), Homeland was issued firm license W818638 on January 11, 2022. On November 10, 2026, Homeland became a BBB Accredited Business (BBB Serving Southeast Florida & the Caribbean), with an A+ rating. Each adjuster’s appointment with Homeland appears on that adjuster’s own DFS record.
- English and Spanish. Office: 8004 NW 154th Street, Suite 609, Miami Lakes, FL 33016 (visits by appointment). Florida (305) 783-3777 · New Jersey (732) 517-3777, 24/7.
How It Works: 5 Steps
- Call Homeland first. Call (305) 783-3777 in Florida or (732) 517-3777 in New Jersey, 24/7, in English or Spanish, before you sign anything or throw anything out.
- A licensed adjuster comes to you. A licensed Homeland public adjuster comes to your property and inspects, photographs and measures the damage.
- We document and file the claim. We write a line-item estimate, report the claim for you, or re-open a claim that was denied, underpaid or closed.
- We negotiate with your insurer. We meet the insurer’s adjuster, present the full claim and negotiate it, start to finish. You don’t have to deal with the insurer alone.
- You get paid. Payment goes to you, and our fee is explained in your written agreement before you hire us, within the limits Florida law sets (Fla. Stat. §626.854(11)(b)). No Recovery, No Fee.
What Makes a Miami Beach Claim Different
Towers, associations and assessments
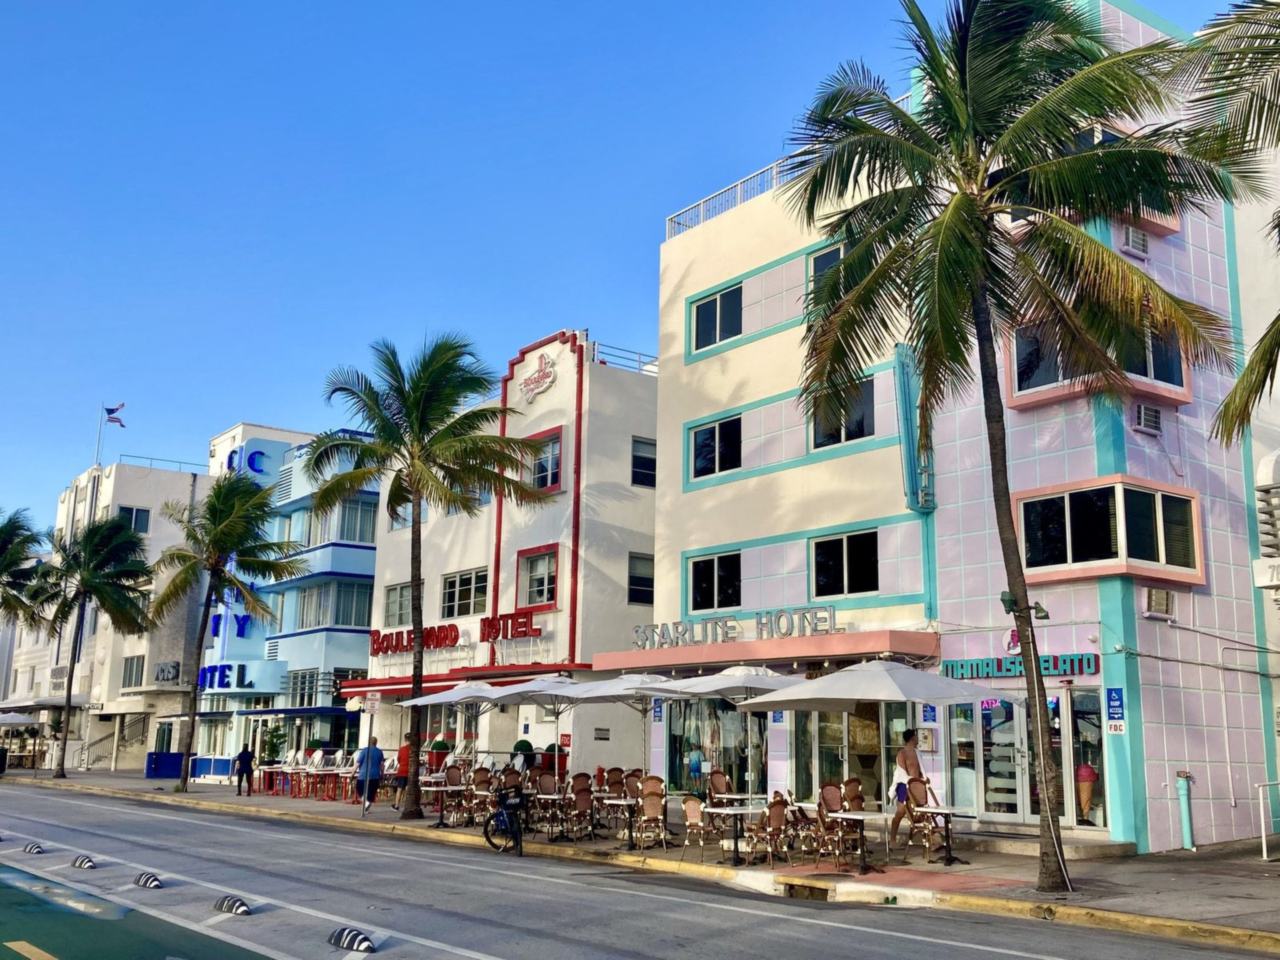
About 65.4% of Miami Beach housing units, 41,334 in all, are in buildings with 20 or more units (ACS 2020-2024), and 40.9% of occupied units are owner-occupied. A tower loss can involve the association's master policy, owners' HO-6 policies and tenants' renters policies at once. When an association's coverage falls short on a large loss, owners may face special assessments.
Two claims on one building
In 2024 the county counted 51,701 Miami Beach buildings in flood zone AE and only 3,939 in zone X. After a storm, one building may need a flood claim for rising water and a separate wind claim for roof and window damage. Each claim has its own deductible and may have its own adjuster, so the damage list has to be split carefully between them.
Older buildings and street flooding
Miami Beach housing has a median year built of 1969, and 12,721 residential structures were built before 1957, the earliest period in the county's flood-regulation milestone table. On August 1, 2017, 1 to 2 feet of water covered several South Beach streets and entered homes, lobbies and garages. Damage to lobbies and garages usually belongs on the association's claim, not the unit owner's.
Miami Beach by the Numbers
| Topic | Fact | Source |
|---|---|---|
| Housing units | Miami Beach has 63,243 housing units with a median year built of 1969 (ACS 2020-2024). | U.S. Census Bureau, ACS 2020-2024 |
| High-rise living | About 65.4% of housing units, 41,334 in all, are in buildings with 20 or more units (ACS 2020-2024). | U.S. Census Bureau, ACS 2020-2024 |
| Owner-occupied homes | 40.9% of occupied housing units in Miami Beach are owner-occupied (ACS 2020-2024). | U.S. Census Bureau, ACS 2020-2024 |
| Flood zones | The county counted 51,701 Miami Beach buildings in FEMA zone AE and 3,939 in zone X in 2024. | Miami-Dade Local Mitigation Strategy (2025 draft) |
| Pre-1957 homes | Miami Beach has 12,721 residential structures built before 1957, the earliest period in the county's flood-regulation milestone table (2024). | Miami-Dade Local Mitigation Strategy (2025 draft) |
| October 2011 rain | Miami Beach recorded 21.34 inches of rain in October 2011, breaking a 1952 record of 18.02 inches. | Miami-Dade Local Mitigation Strategy (2025 draft) |
| Flood rating and repeat losses | Miami Beach holds a FEMA CRS Class 5 rating (December 2024) and had 96 residential and 23 commercial repetitive flood loss properties in 2024. | Miami-Dade Local Mitigation Strategy (2025 draft) |
Questions to Ask Any Public Adjuster About a Miami Beach Claim
- Have you worked claims under both master and HO-6 policies? With 41,334 Miami Beach units in buildings of 20 or more units, tower claims are common here. Knowing where the master policy ends and the unit policy begins can keep damage from being missed.
- How do you handle one building with both wind and flood claims? With 51,701 Miami Beach buildings in zone AE, one storm can trigger a flood claim and a wind claim on the same property. Each needs its own documentation and carries its own deductible.
- Will your estimate show code upgrades on an older building? Miami Beach's median year built is 1969. Repairs on buildings that old may require code upgrades, which are paid only under ordinance or law coverage, so the estimate should list them as separate items.
Guides for Miami Beach Claims
Miami Beach Questions
Is flood covered after a storm in Miami Beach?
Our condo lobby and garage flooded. Is that my claim or the association's?
Does Miami Beach's flood rating affect my claim?
How much does a public adjuster charge in Florida?
Homeland works from its office in Miami Lakes and comes to your property. Call (305) 783-3777, 24/7. Local page: Public Adjuster in Miami Beach, FL.