
How Homeland Answers the Questions to Ask Any Public Adjuster
- Active individual and firm license
- Firm: Florida W818638, New Jersey 3003982360. Each adjuster’s own license number and DFS record are listed under Verify Homeland.
- Complaints and discipline
- BBB Accredited Business, A+ rating. Look up any license on the DFS licensee search before you sign.
- Who handles your claim
- A licensed Homeland public adjuster handles your file and comes to your property. Our adjusters are named, with their license numbers, under Verify Homeland.
- A documented process
- Five steps, from your call to payment. See How It Works.
- Fee explained in writing
- Our fee is explained in your written agreement before you hire us. Florida law caps public adjuster fees (Fla. Stat. §626.854(11)(b)); see our fees page. No Recovery, No Fee.
- Reachable 24/7
- 24/7 at (305) 783-3777. A licensed Homeland adjuster comes to your property, anywhere in Florida.
- Bilingual
- English and Spanish, on the phone, at your property and in writing.
The Florida law behind each of the 10 tests is on our Florida 10-point test page. Warning signs and common online claims are answered in Public Adjuster Myths vs. Florida Law.
Verify Homeland
Check us before you hire anyone. Every license below links to its public record on the Florida Department of Financial Services licensee search.
- Serves Cape Coral: Yes. Wherever you are in Cape Coral, a licensed Homeland public adjuster comes to your property within hours — no need to visit an office. Call (239) 414-3777, 24/7.
- Homeland Public Adjusters Corporation: Florida public adjusting firm license W818638 · New Jersey public adjuster firm license 3003982360
- Yeni Martinez, President: Florida public adjuster license P103370 (licensed since 2007) · New Jersey 3003714097 · designated primary adjuster
- Alberto Enriquez: Senior licensed public adjuster, Florida P112658
- Yisel Dieguez: Licensed public adjuster and Xactimate estimator, Florida W873884 · New Jersey 3003714335
- Nelson Avila: Florida public adjuster license G332385 · Florida Certified Contractor CRC1331322 · property insurance appraiser and umpire
- Complaints and reputation: 5.0★ on Google · BBB Accredited Business, A+ rating
- Since 2006: Homeland Public Adjusters, Corp. was incorporated in Florida on December 11, 2006. Our President, Yeni Martinez, has held Florida public adjuster license P103370 since 2007. When Florida began requiring adjusting firms to hold their own firm license (a 2021 law, Senate Bill 1598; DFS began licensing adjusting firms in November 2021), Homeland was issued firm license W818638 on January 11, 2022. On November 10, 2026, Homeland became a BBB Accredited Business (BBB Serving Southeast Florida & the Caribbean), with an A+ rating. Each adjuster’s appointment with Homeland appears on that adjuster’s own DFS record.
- English and Spanish. Office: 8004 NW 154th Street, Suite 609, Miami Lakes, FL 33016 (visits by appointment). Florida (305) 783-3777 · New Jersey (732) 517-3777, 24/7.
How It Works: 5 Steps
- Call Homeland first. Call (305) 783-3777 in Florida or (732) 517-3777 in New Jersey, 24/7, in English or Spanish, before you sign anything or throw anything out.
- A licensed adjuster comes to you. A licensed Homeland public adjuster comes to your property and inspects, photographs and measures the damage.
- We document and file the claim. We write a line-item estimate, report the claim for you, or re-open a claim that was denied, underpaid or closed.
- We negotiate with your insurer. We meet the insurer’s adjuster, present the full claim and negotiate it, start to finish. You don’t have to deal with the insurer alone.
- You get paid. Payment goes to you, and our fee is explained in your written agreement before you hire us, within the limits Florida law sets (Fla. Stat. §626.854(11)(b)). No Recovery, No Fee.
Homeland Results and Reviews in Cape Coral
- Hurricane Irma · Cape Coral — $221,035
- Hurricane Ian · Cape Coral — $174,346
- Hurricane Ian · Cape Coral — $122,549
- Tornado / Wind · Cape Coral — $22,500
Every claim is different. Results depend on each loss and policy; past results don't guarantee a future outcome.
Amounts are insurance payments obtained on each claim, before Homeland's fee and other costs, rounded to the nearest dollar. Client names are withheld for privacy.
“I’m in Cape Coral and went through a really tough situation after Hurricane Ian. Like most people, I had no idea where to even start with the insurance claim process… Thankfully, I had already signed up for Adjuster Advantage…”
“I’ve worked with other public adjusters before, and in my experience, Homeland Public Adjusters clearly stood out above the rest. After Hurricane Milton in Cape Coral, I thought the claims process was going to be complicated…”
“I live in Cape Coral and have worked with Homeland on more than one occasion. They have always been very professional, responsible, and clear throughout the entire process…”
Nearby areas we serve: Public adjuster in Fort Myers · Public adjuster in Lehigh Acres · Public adjuster in Charlotte Harbor · All Florida cities and counties
What Makes a Cape Coral Claim Different
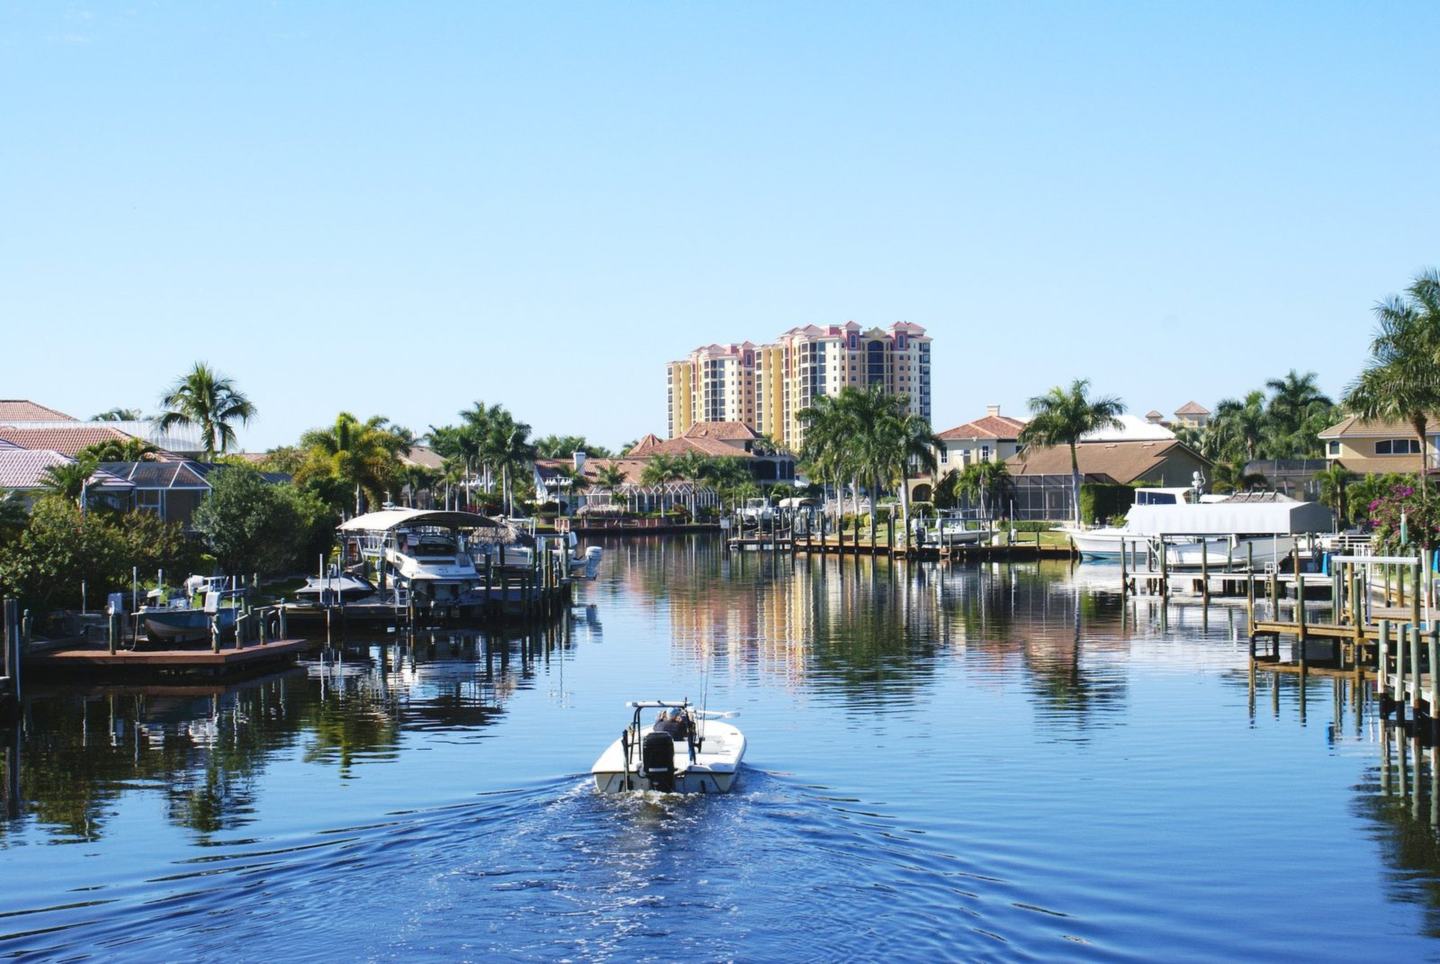
Canal-front homes
The City of Cape Coral says it has over 400 miles of navigable waterways, and the National Hurricane Center found Ian's inundation reached 6 to 9 feet above ground in Cape Coral and nearby communities in 2022. Docks, lifts, pool cages and seawalls are often treated differently from the house in a policy. Some items may be limited or excluded, so each structure should be listed and checked against the policy wording.
The 50% rule and the look-back
If repairs equal or exceed 50% of a structure's market value, the home may have to be rebuilt to current flood and building code. On November 30, 2022, Cape Coral approved Ordinance 96-22, which removed the 5-year cumulative look-back from those reviews. A careful repair estimate matters here, and ordinance or law coverage can help pay code-upgrade costs, but only if the policy carries it.
A city of single-family homes
Only 3.6% of Cape Coral housing units sit in buildings with 20 or more units, and owners occupied 77.2% of occupied homes in the 2020-2024 Census survey. Most claims here are a single owner against a single insurer, with no association to share the load. That means roof, interior, contents and extra living costs all ride on the owner's own documentation and the owner's own policy limits.
Cape Coral by the Numbers
| Topic | Fact | Source |
|---|---|---|
| Housing units | Cape Coral had 100,679 housing units, with a median year built of 2000 (ACS 2020-2024). | U.S. Census Bureau, ACS 2020-2024 (via Census Reporter) |
| Owner-occupied | Owners occupied 77.2% of occupied homes, and 3.6% of units were in buildings with 20 or more units (ACS 2020-2024). | U.S. Census Bureau, ACS 2020-2024 (via Census Reporter) |
| Waterways | The city says it has over 400 miles of navigable waterways (accessed 2026). | City of Cape Coral |
| Ian inundation | Ian's inundation reached 6 to 9 feet above ground in Pine Island, Cape Coral and nearby communities (2022 storm, report updated 2026). | National Hurricane Center |
| 50% rule change | Ordinance 96-22, approved November 30, 2022, removed the 5-year cumulative look-back from substantial-damage reviews. | City of Cape Coral |
| NFIP Ian claims | FEMA NFIP claim records show about 5,894 Ian claims for the City of Cape Coral, with about $450.2 million paid (2026 data). | FEMA OpenFEMA NFIP claims, Homeland tally |
| Flood maps and rating | Current flood maps took effect November 17, 2022, and the city holds Community Rating System Class 5, a 25% high-risk zone discount. | FEMA |
Questions to Ask Any Public Adjuster About a Cape Coral Claim
- How do you handle docks, lifts, seawalls and pool cages? With over 400 miles of waterways in the city, many Cape Coral homes have waterfront structures. Policies often limit or exclude some of them, so ask how the adjuster lists each one and matches it to the policy.
- Can your estimate hold up in a 50% rule review? Cape Coral applies the 50% rule based on market value, and Ordinance 96-22 removed the 5-year look-back in 2022. A detailed, line-item repair estimate helps both the claim and the city's review.
- Who on your team understands construction and code? Ian brought 6 to 9 feet of inundation to Cape Coral and nearby areas, and rebuilding can trigger code upgrades. Nelson Avila is a Florida Certified Contractor, and you should ask any firm what building background it has.
Guides for Cape Coral Claims
Cape Coral Questions
Is my Cape Coral seawall covered by my homeowners policy?
My Cape Coral home may be over the 50% line. What now?
How common were flood claims in Cape Coral after Ian?
How much does a public adjuster charge in Florida?
Homeland works from its office in Miami Lakes and comes to your property. Call (239) 414-3777, 24/7. Local page: Public Adjuster in Cape Coral, FL.
What Cape Coral Clients Say About Homeland
Verbatim reviews from Homeland clients on Google.
“After the hurricane damaged our home in Cape Coral, our insurance company offered us an amount that wasn’t even close to what we needed. Thankfully, we found Homeland Public Adjusters. What A difference! They fought for us and got us a much better settlement. I’m so glad we didn’t accept that first offer. As far as I’m concerned, you won’t find a better public adjuster than Homeland!”
“Homeland is by far the best we've worked with.”
“If you’re looking for the best public adjuster, I highly recommend Homeland.”