
Homeland Public Adjusters handles water damage claims, from burst pipes and plumbing leaks to roof and appliance leaks, for property owners in Florida and New Jersey. We trace and document the damage well beyond the visible leak, prepare the claim, and negotiate it with your insurer. No Recovery, No Fee. Call 24/7.
Last reviewed: October 2026
Water Damage in New Jersey
Cold winters, heavy rain and older plumbing give New Jersey properties plenty of ways to take on water: pipes that freeze and burst, ice dams that push water under a roof, wet basements, and sewer or drain backups. Moisture that lingers can also lead to mold. Homeland represents New Jersey homeowners, businesses and community associations with water losses. Serving New Brunswick, Elizabeth and communities across New Jersey.
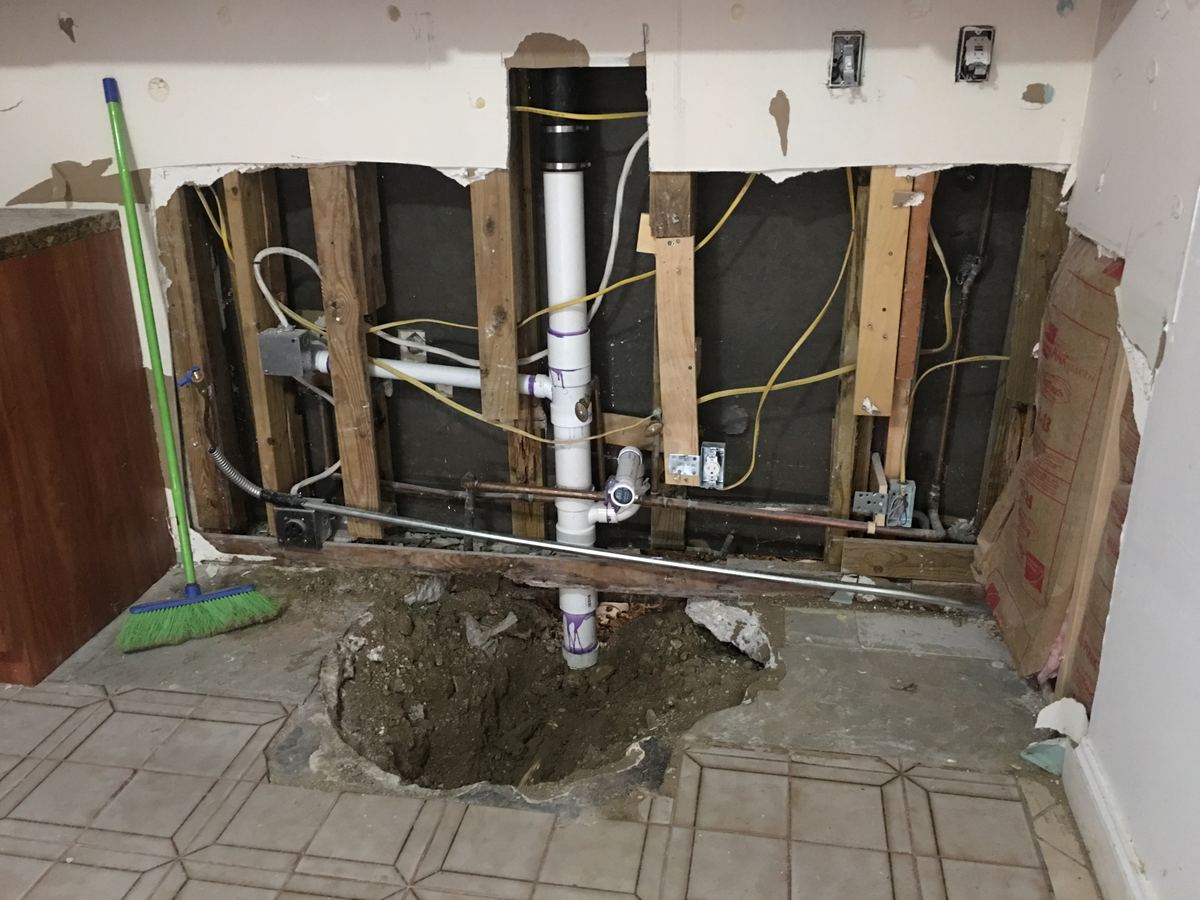
Water Damage in Florida
In Florida, water damage often comes from plumbing leaks, appliance failures, air-conditioner drain lines, and roof leaks after heavy rain. In condominium and HOA buildings, water can travel from one unit to another or through shared plumbing. For water from a storm surge or rising water, see our Flood Damage page; for wind-driven rain after a storm, see Hurricane & Wind Damage.
Navigating a Water Damage Insurance Claim
Not all water losses happen the same way, and the cause of the damage can play an important role in how an insurance claim is evaluated. A burst pipe, plumbing failure, appliance leak, sewer line issue, or storm-related water intrusion can each create different damage patterns and raise different questions about coverage, exclusions, sublimits, and policy conditions. Coverage can also depend on whether the water arrived suddenly or leaked gradually over time, so read your policy closely.
Our team can help establish the scope of damage, review applicable policy provisions, organize estimates and supporting evidence, and communicate with the insurance carrier as the claim moves forward.
Water Damage in a Condo or HOA Association Building
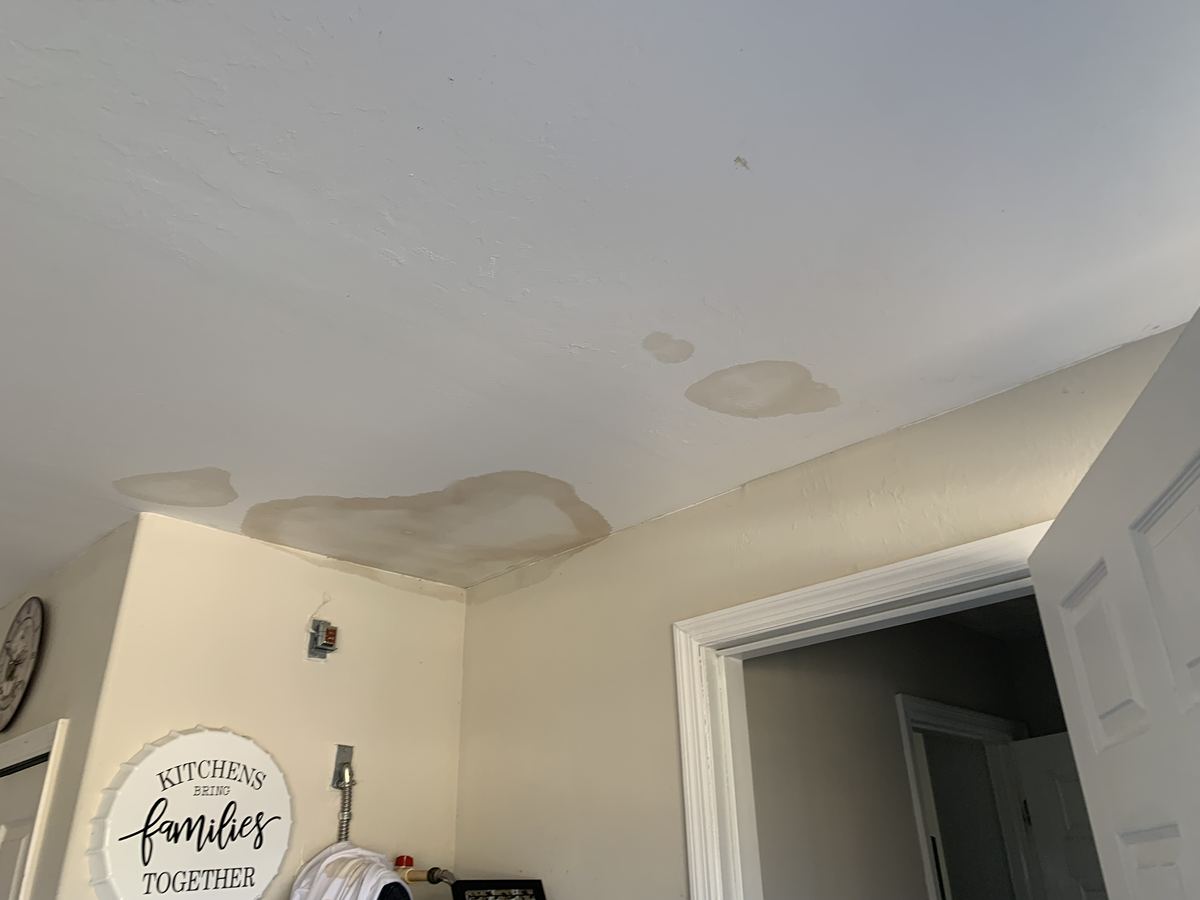
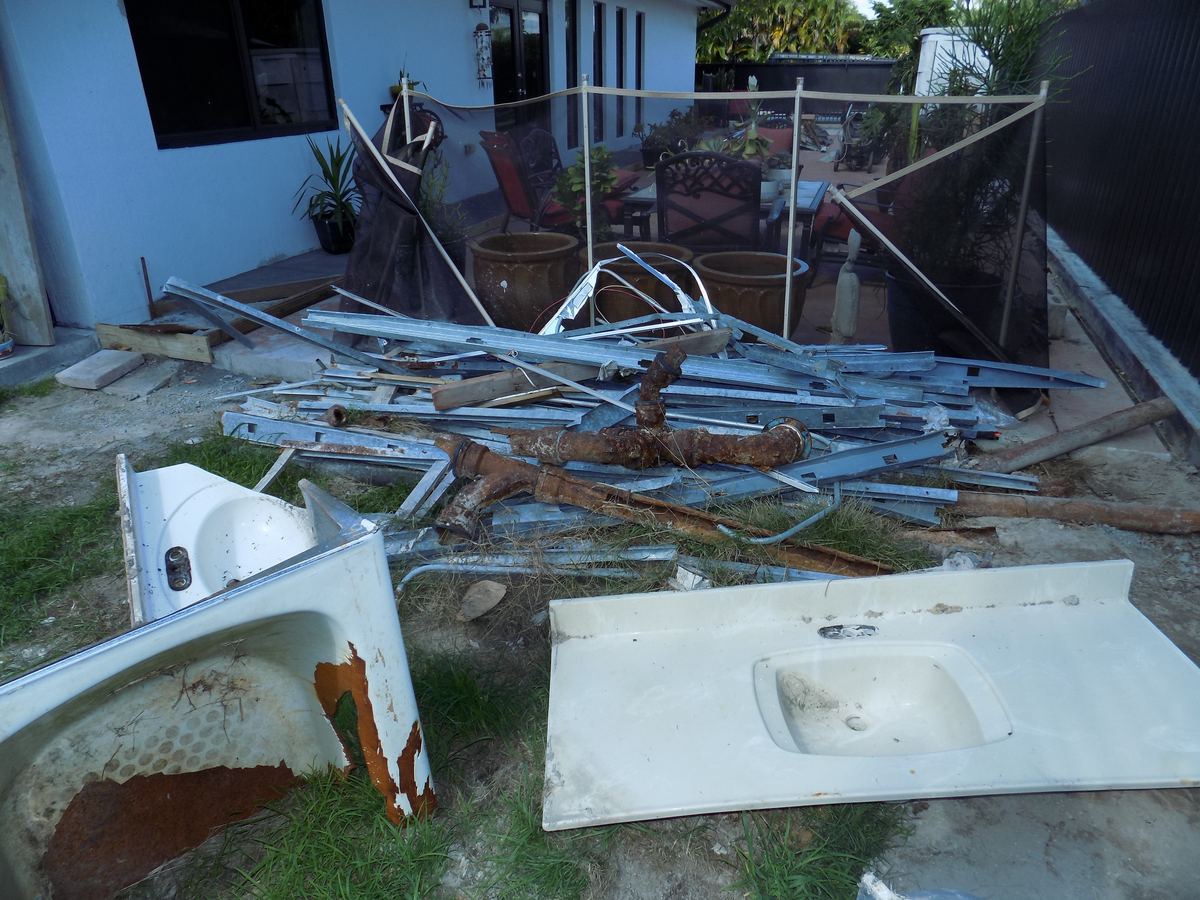
Water damage in a condominium or HOA building can involve both the association’s master policy and an individual unit owner’s own policy. Which one applies often depends on where the water came from and what caused it, so Homeland reviews both before a claim is filed.
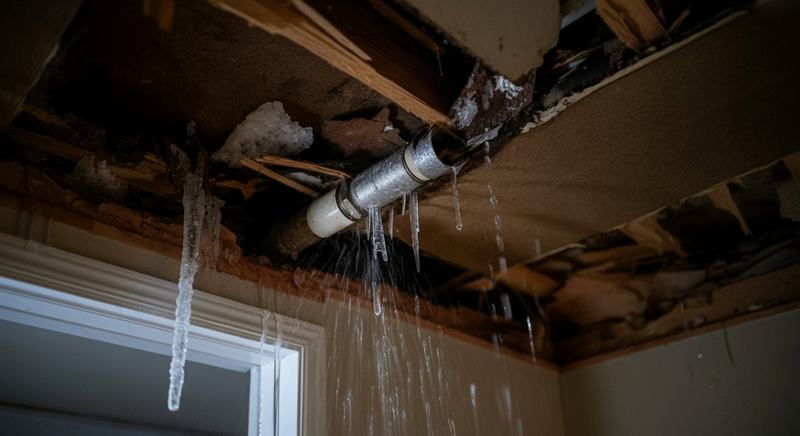
Leaks from shared plumbing, roofs or building systems can affect common areas and are often addressed under the association’s master policy.
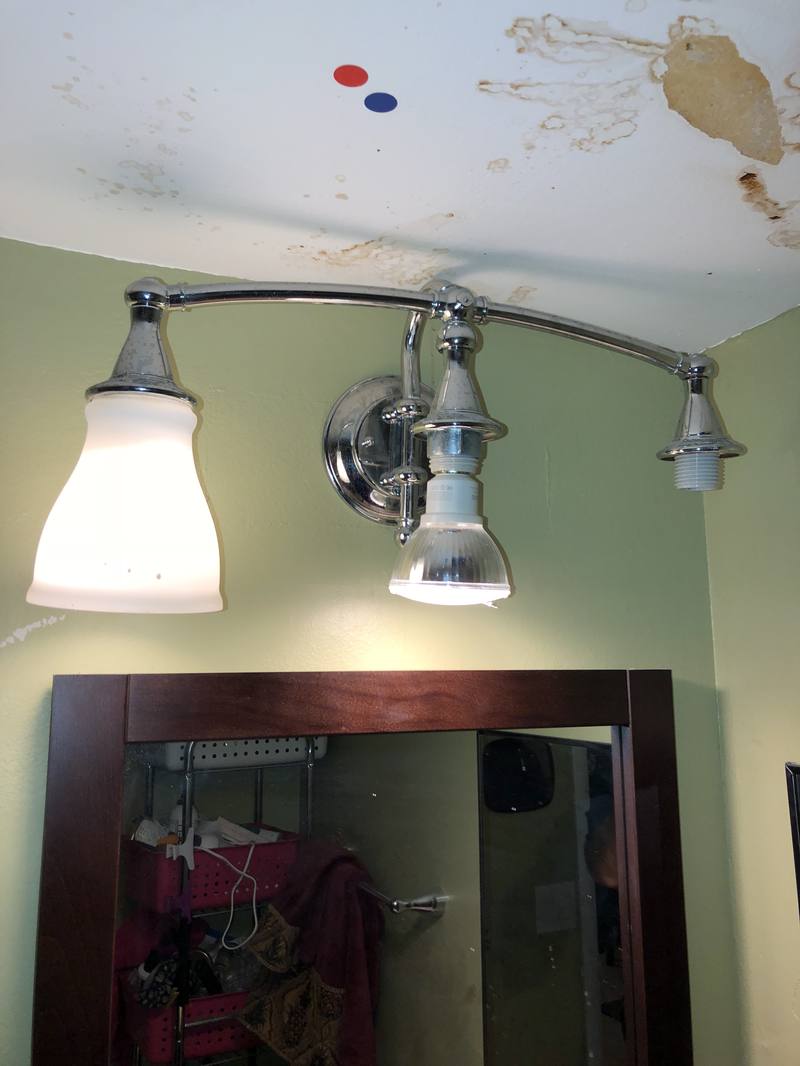
Water from a neighboring unit or the unit above can raise questions about which policy responds, since coverage can depend on the source and cause.
Flooring, cabinetry and personal belongings inside a unit are often the unit owner’s own responsibility to claim.
Unlike some other causes of loss, which policy covers water damage in a condo or HOA building can depend on where the damage is and what caused it, so the association’s master policy and the unit owner’s own policy may both be involved. Homeland can help determine which policy applies to each part of the loss.
See our Condo & HOA Associations claims page for more on master-policy claims.
Types of Property Damage Caused by Water
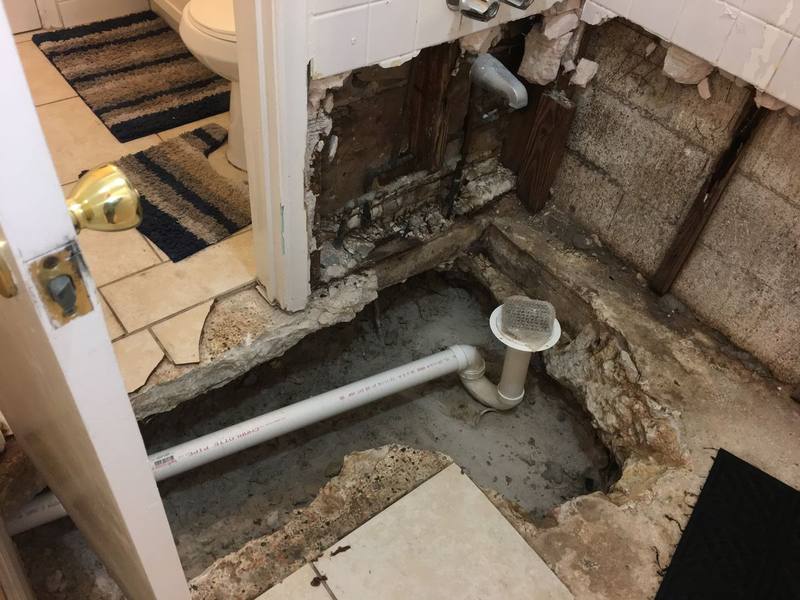
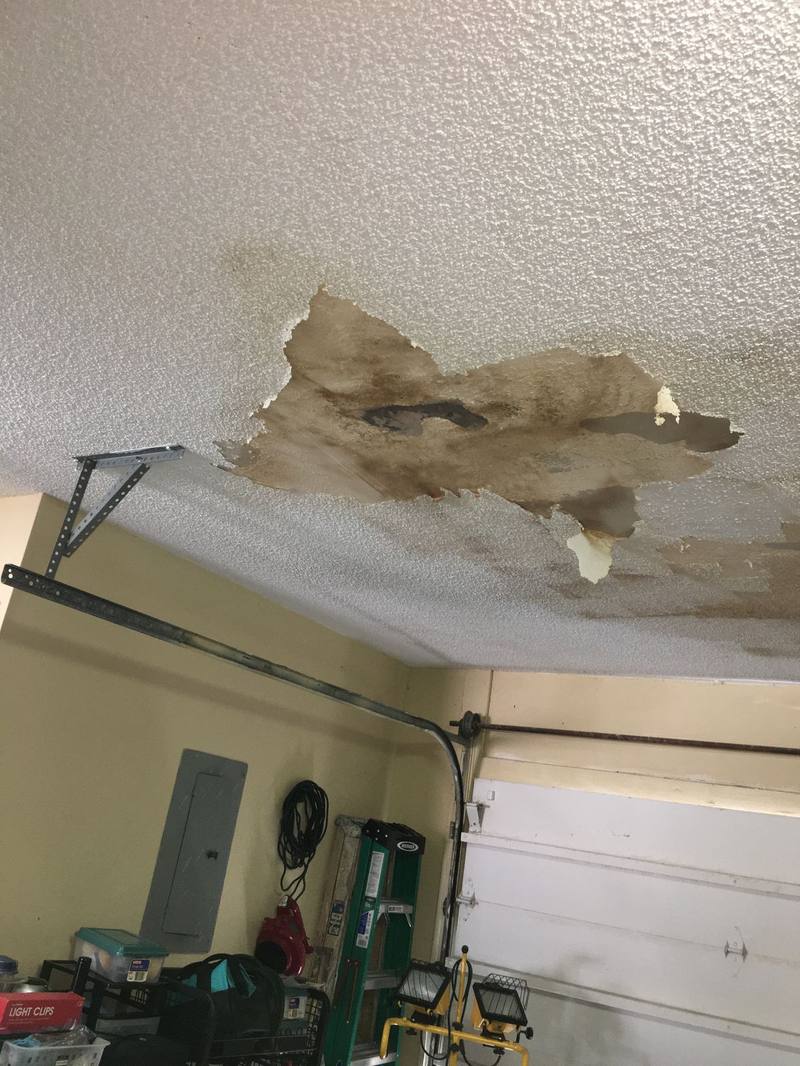
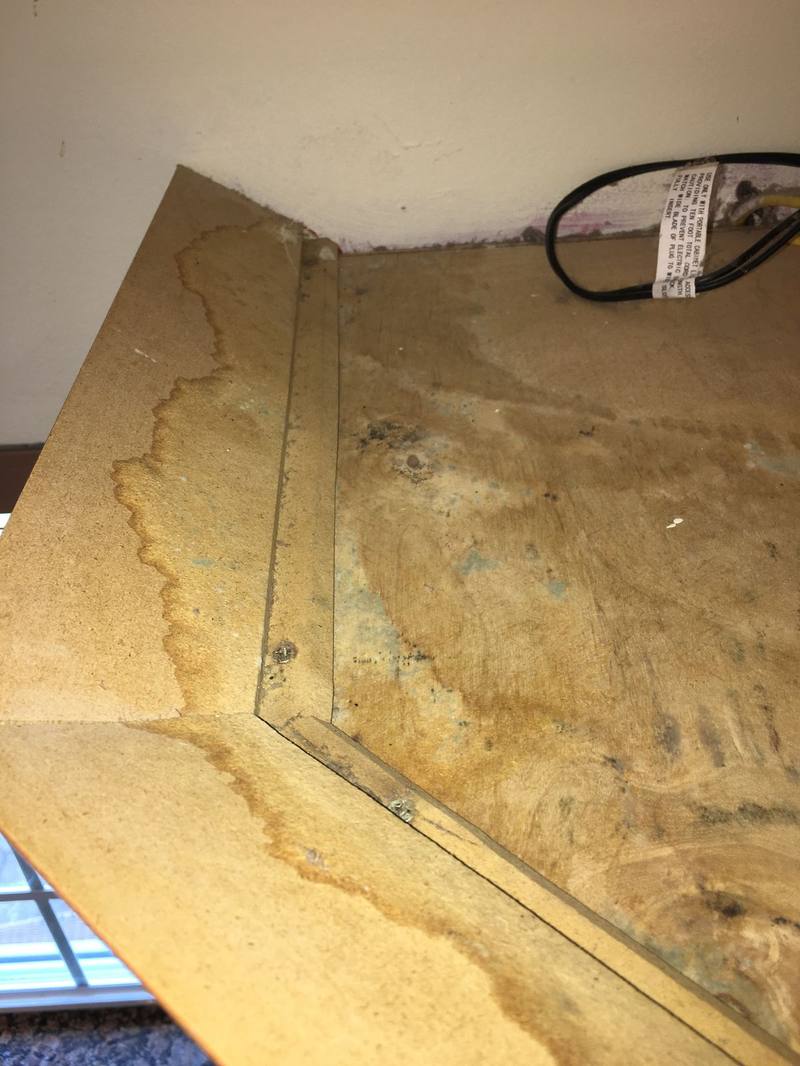
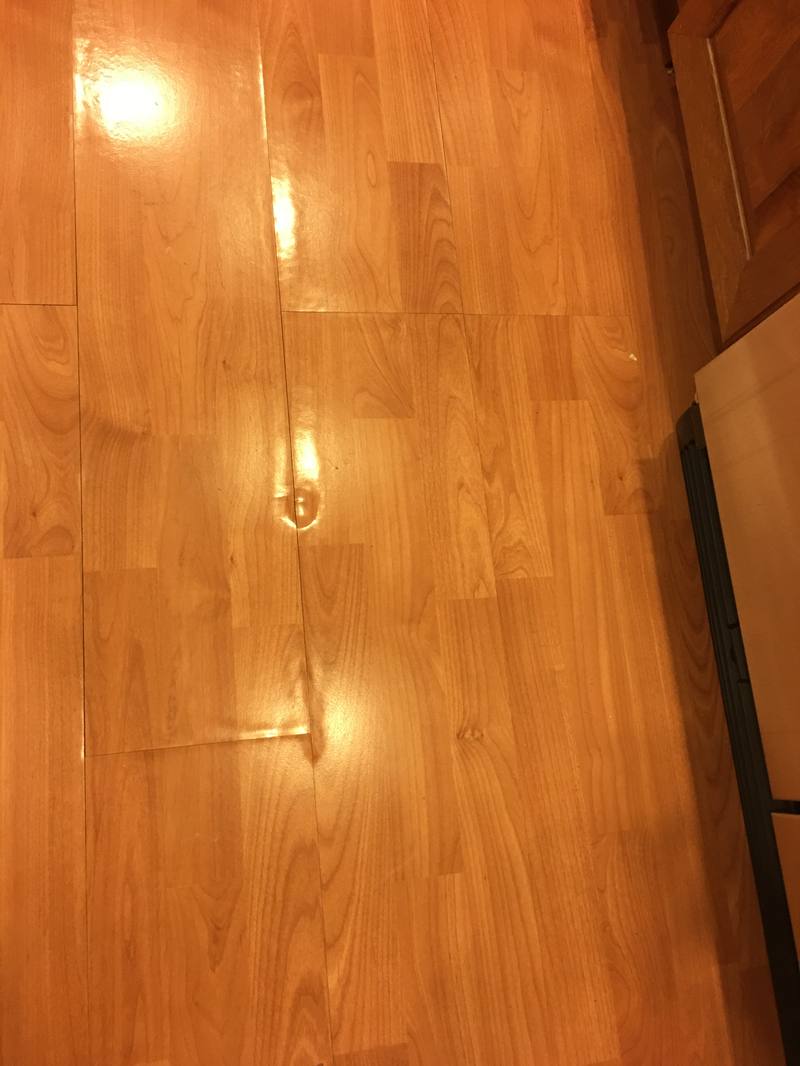
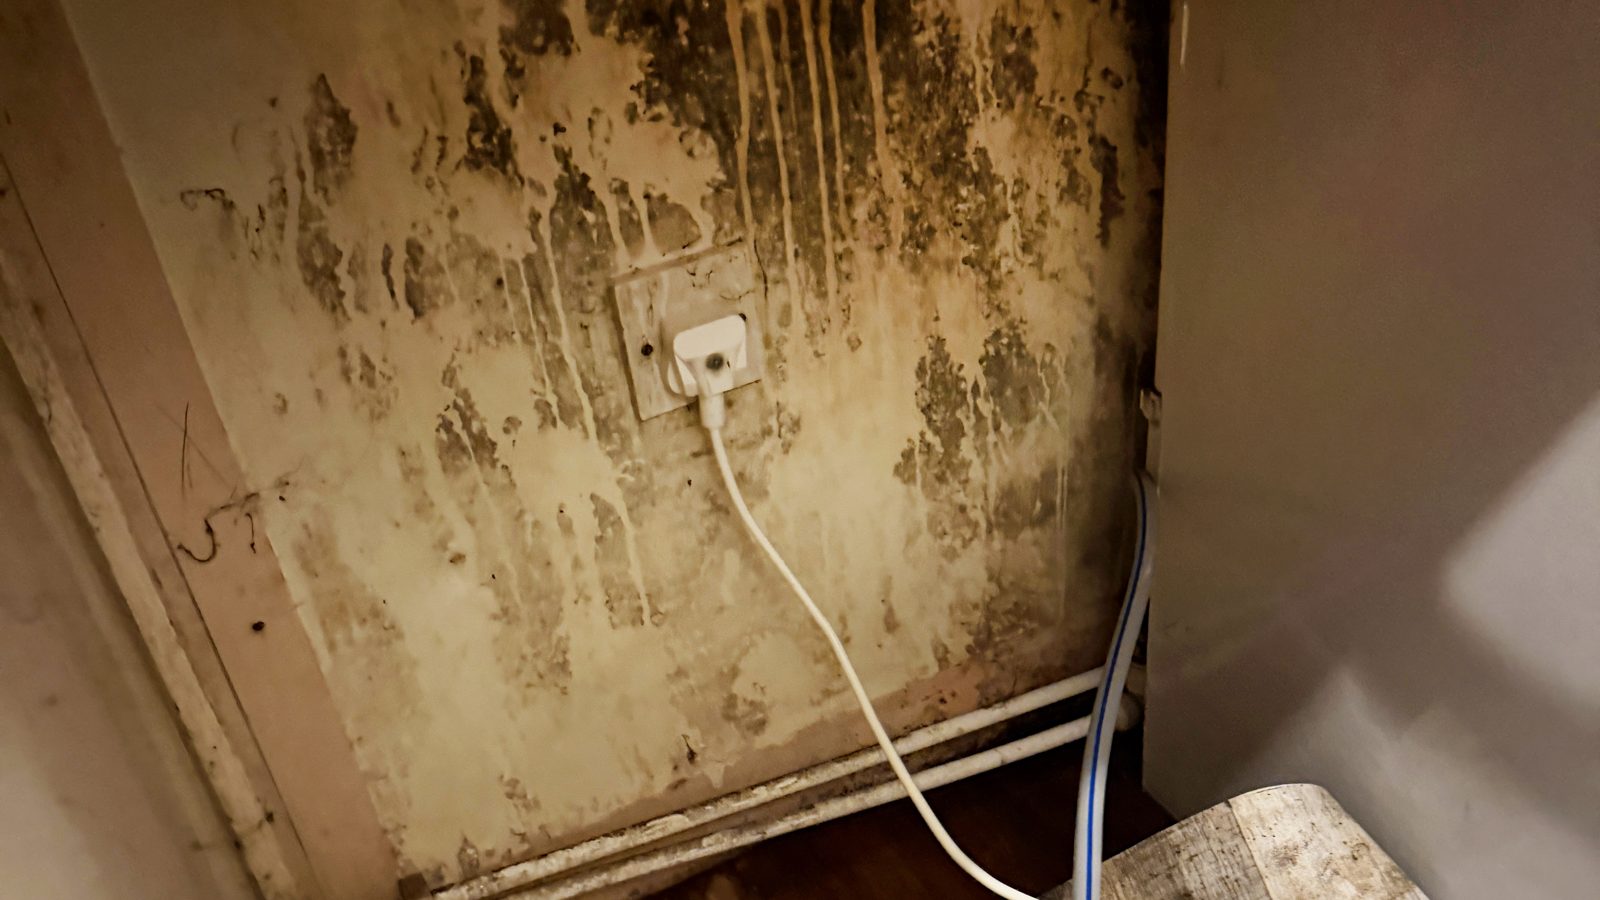
Moisture can travel behind walls, beneath flooring, through ceilings, and into adjoining spaces, meaning the visible wet area may represent only part of the loss. Determining where the water traveled and what materials were affected is an important part of documenting a water damage insurance claim.
Appliance and Plumbing Failures
People search for the appliance, not for “water damage.” These guides cover the failures that produce most non-storm water claims and the sudden-and-accidental test each one has to pass.
Steps to Take After Water Damage
When a water loss occurs, stopping additional water intrusion and protecting people inside the property should take priority. After you address immediate safety concerns, preserving evidence of the original conditions can support your insurance claim.

You Don’t Have to Remember All of This. Adjuster Advantage Has You Prepared.
The best way to prepare for water damage, or any other damage, is a free Adjuster Advantage membership, for property owners and for associations.
Does your building have a record of its equipment and common areas?
AA Associations gives boards and managers the master policy explained in plain words, including what the association insures versus what each owner covers, a dated building record of the roof, exterior, common areas, equipment, clubhouse and amenities, and reminders for the dates you enter. For Florida associations today.
Joining Adjuster Advantage is free and does not create a contract or agreement with Homeland Public Adjusters for any claim. Hiring Homeland is optional and requires a separate written agreement.
When the Water Came From a Neighbor or Another Unit
Water often comes from somewhere else: a neighbor’s home, the unit upstairs, or a shared pipe in the building. Homeland handles claims where the water came from a neighbor or another unit, for property owners with insurance and without. In a condominium or association building, which policy responds can depend on where the damage is and what caused it, so the master policy and the unit owner’s own policy may both matter. If you have no coverage of your own, see our Third Party Uninsured Damage Claims page (Florida).
Water Damage Claims by the Numbers
The Coverages That Decide a Water Damage Claim
Water claims are the most frequently argued claims in Florida. These are the clauses the argument is about:
| Provision | What it does | Where claims go wrong |
|---|---|---|
| Sudden and accidental discharge | Covers water released from plumbing, HVAC, appliances or a water heater when the release is sudden | “Long-term seepage” or “constant leakage over a period of time” is excluded; carriers reach for it on every slow leak discovered late |
| Limited water damage endorsement | Caps non-weather water losses, commonly at $10,000, in exchange for a lower premium; Citizens’ OIR-approved form is the best-known example | Owners discover the cap after the loss; the cap does not apply to ensuing mold, tear-out or weather-driven water if the policy is read correctly |
| Tear-out and access | Pays to open walls, floors and slabs to reach the failed pipe, even though the pipe repair itself is excluded | Plumber’s repair bill denied and the tear-out denied along with it |
| Mold sublimit | Mold remediation is usually capped by a separate limit, often $10,000, when it results from a covered water loss | Remediation and the rebuild of what remediation removed both charged against the mold cap |
| Plumbing age and maintenance | Florida carriers may exclude or limit losses from pipes beyond a stated age (cast iron, polybutylene) on specific forms | Blanket denials for “wear and tear” on a sudden break; the cause of the break is the question, not the age of the pipe |
| Notice of claim | Initial or reopened claim within 1 year, supplemental within 18 months (§627.70132); the policy also requires prompt notice | Late notice argued on leaks found months after they began; the date of discovery and the mitigation steps need to be documented the same day |
Terms in this table, defined: Water Damage Categories and Classes, Policy Exclusions, Date of Loss, Recoverable Depreciation, Supplemental Claim and Reopened Claim. See the full claims glossary.
Deadlines to Know
New Jersey. New Jersey regulations require insurers to begin an investigation within 10 working days of notice of a claim, and set a 30-calendar-day period, running from receipt of a properly executed proof of loss, for first-party claims. If more time is needed, the insurer must explain why in writing, with updates every 45 days, unless a clear justification or other law provides otherwise.
Why Choose Homeland for Your Water Damage Claim?
Water losses can change quickly as moisture moves through a building, so early, detailed documentation matters. Homeland Public Adjusters works from the policyholder’s side to evaluate the affected areas, organize evidence of the loss, and present a documented claim to the insurance carrier.
In the News: A Real Water Damage Claim
Water Damage FAQs
Is water damage covered by my insurance?
What is the difference between water damage and flood damage?
The water came from my neighbor or the unit above me. Can Homeland help?
What if mold appeared after the water damage?
How long do I have to file a water damage claim?
My water damage claim was denied or underpaid. Can Homeland still help?
Insights
 By Alberto Enriquez
 By Nelson Avila
Water Damage Claims We Handle Across Florida & New Jersey
Homeland handles water damage claims throughout Florida and New Jersey. Wherever your property is in either state, call us 24/7.
Talk to a Public Adjuster
Tell us about your loss. We’ll call you back.
Claims We Handle
Hurricane & Wind Damage→Flood Damage→Fire Damage→Winter Storm & Roof Damage→Theft & Vandalism Damage→Vehicle Impact Damage→Business & Commercial→Other Claims→Denied & Underpaid→Join Adjuster Advantage™
Know your policy and keep your records ready, before the next leak.
Join FreeOther Property Damage Claims We Handle
Water damage can have many causes, from a failed pipe to a storm. Homeland Public Adjusters also assists with other types of property damage claims when applicable to the loss and available coverage.
