What to Do in the First 24 Hours After Property Damage

Homeland Public Adjusters · Last reviewed: October 2026

Safety comes first. If there’s active fire, standing water near electrical, or structural damage that makes part of the home unsafe, get everyone out and stay out until it’s been checked. Once the immediate danger has passed, the next 24 hours set the tone for the whole claim.
Document before you touch anything
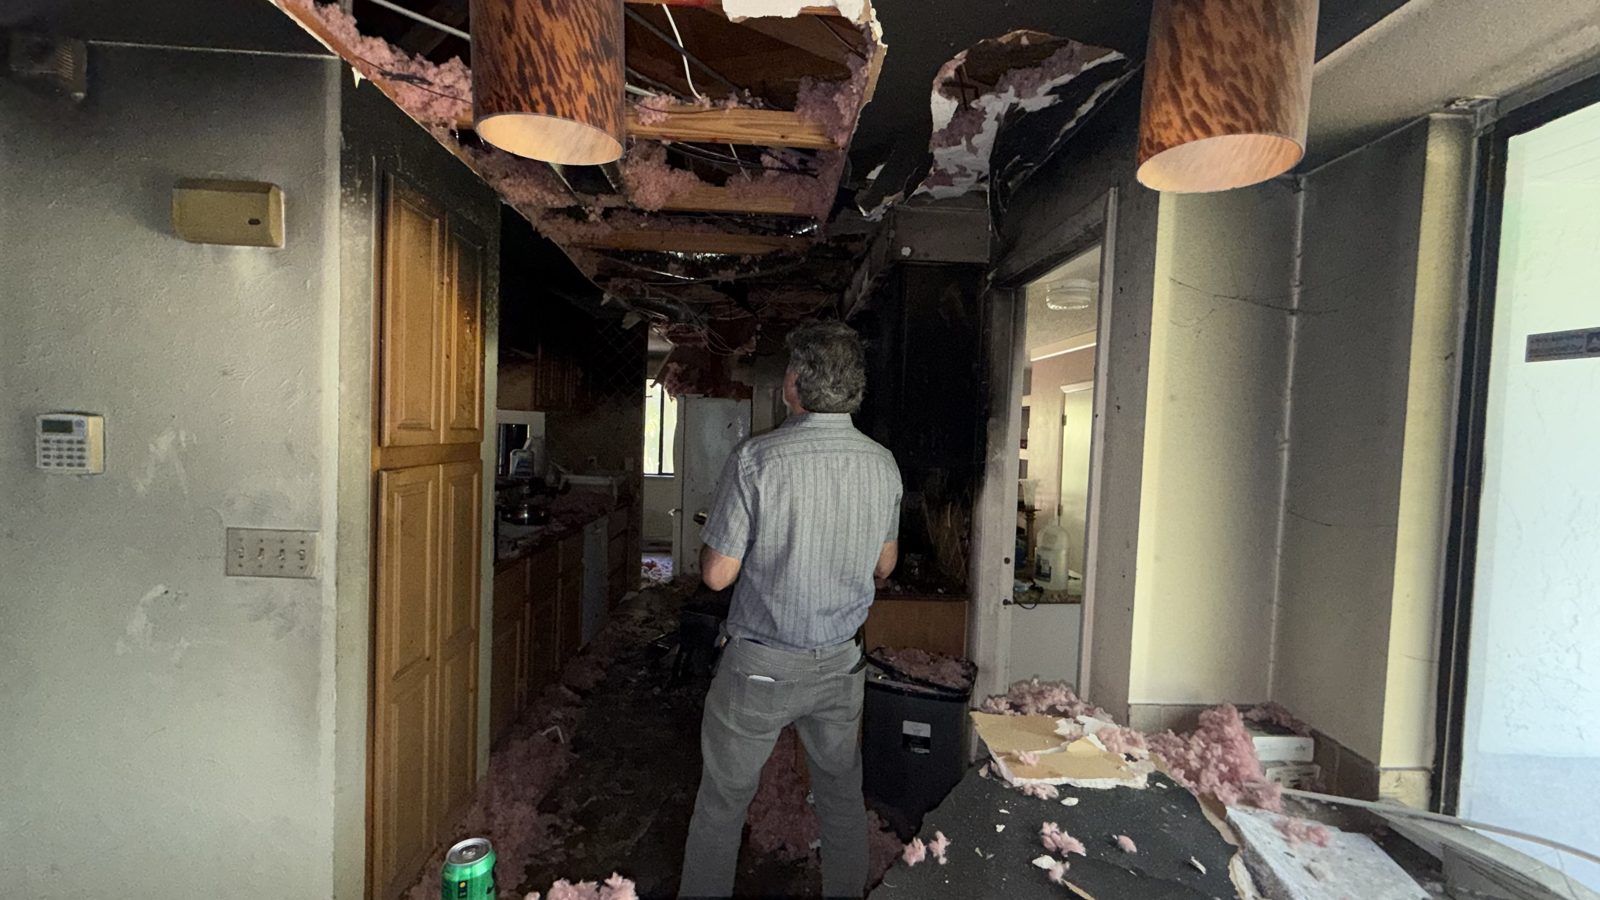
Photos and video of the damage, from multiple angles, before any cleanup or repair starts — including things that seem minor. Water spreads, smoke travels, and damage that looks contained on day one often isn’t.
Protect the property from getting worse
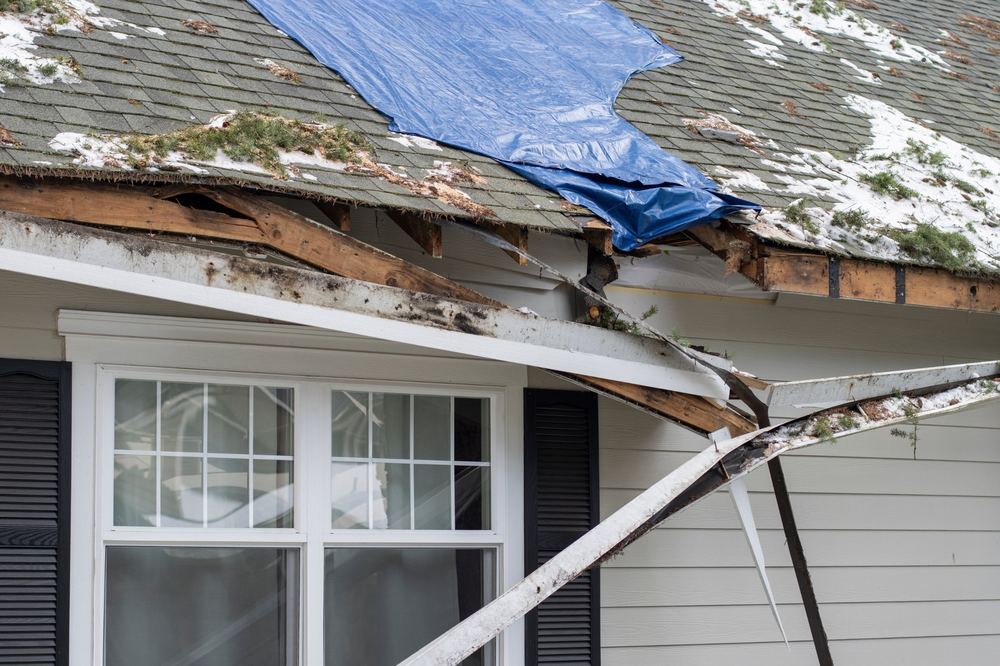
Tarping a hole in the roof, shutting off water at the source, boarding a broken window — reasonable steps to prevent additional damage are expected and usually reimbursable, but photograph the “before” condition and keep receipts first.
Keep a simple log
Who you spoke to, when, and what was said — for any contractor, restoration company or inspector who comes through, not just the insurance side.
Homeland's local lines answer 24/7 in Miami, Tampa and Jersey City, and anywhere else in Florida or New Jersey.
Frequently asked questions
What should I do first after property damage?
Will my insurance pay for emergency repairs like tarping a roof?
Should I call my insurance company right away after damage?
This article is for general information only and is not legal or insurance advice. Every policy and every claim is different — always review your own policy language or speak with a licensed public adjuster about your specific situation.
- Surprising Things Your Policy Covers
- Neighbor's Condo Fire: Who Pays?
- Damaged Tile or Laminate: A Claim?
- Barn, Stable & Outbuilding Coverage
- Wind and Tornado Risk on the Farm
- Crop Insurance vs. Property Insurance
 Yeni Martinez
 Alberto Enriquez
 Yisel Dieguez
Homeland Public Adjusters represents policyholders, not insurers. Get a free review of your claim.
Get a Free Claim ReviewThis topic often comes up alongside Surprising Things Your Homeowners Policy Might Actually Cover. If your situation involves this kind of loss, see our Homeowners page for how Homeland can help with the claim itself.